|
RETIREMENT SECURITY MATTERS
A forum for retirement innovation information sharing
focused on states, supporters, and service providers.
Vol 81 | June 29, 2023
| | |
Greetings! Lisa, welcome to Retirement Security Matters – where we talk about retirement readiness innovation by states, supporters, and service providers. | |
In this edition we’ll explore the latest developments in retirement savings innovations, including state retirement plan mandates. Discover how these programs complement, rather than compete with the private sector market. So, grab something cold and read on:
-
Things heard in rooms - wrapping up the spring conference season
-
State metrics - OregonSaves crosses $200 million asset milestone 🥂
-
Updates from Colorado, Hawaii, Illinois, Maine, New Jersey, Oregon, and Virginia
-
How do firms respond to state retirement plan mandates? INSIGHTS from new research
-
Hot Sauce! Some Cool Stuff for you ✅
-
And … PIX of the Week!
| Comments or content suggestions? We welcome both. Have something about your program you’d like to share? We are all ears. | |
|
RSM wants your support! Be seen.
Click to grab this space for your brand.
| |
Things Heard in Rooms: Charting the Course Towards a Secure Retirement - Wrapping the Spring Conferences Season | |
|
As the smell of freshly brewed coffee fills rooms and a chorus of chairs squeak and shuffle to find their places, discussions on retirement savings spring to life. Gathered in these rooms are a diverse set of minds - private sector innovators, state officials, Treasury officers, legislators, policy makers - each prepared to offer their piece to the puzzle that is the future of retirement security in the United States.
First on our list: the Retirement Savings Sitch. By 2030, it's projected that one in five Americans will be at retirement age, and an increasing number of households will have to navigate the challenges of maintaining their quality of life post-retirement.
These are real people, with real needs. Their lives are being affected by inequalities in retirement plan access, participation, and savings. From everyday expenses to unexpected long-term care costs, today’s retirees are feeling the squeeze.
In these rooms, we heard about barriers that employers face in offering retirement plans. But contrary to what these challenges might suggest, these rooms are buzzing with energy, optimism, and innovation.
What we're seeing is clear evidence of success. Take a closer look at the pioneering state auto IRA programs like OregonSaves, Illinois Secure Choice, and CalSavers – joined over the last 12 months by MyCTSavings (Connecticut), Maryland$aves, Colorado Secure Savings, Virginia Retirepath, and eight other states with authorizing legislation making their way through the launch process. These trailblazing initiatives have created new avenues for workers to save for retirement, circumventing traditional obstacles and breaking down barriers for employers.
As we look to the future, one thing is clear: the landscape of retirement security is changing, shaped by the conversations happening right now, in these very rooms. And trust us, it's a future worth staying tuned for. So, grab another cup of coffee, pull your chair in a little closer, and join the conversation. Because when it comes to the future of retirement security, we're all in this together, and the things being heard in these rooms are reshaping the retirement of tomorrow.
In recent years, policy and market innovation have taken center stage. Their target? A staggering 57 million American workers who lack access to workplace retirement savings. They're not aiming for small changes, either. We're talking about seismic shifts in the retirement savings landscape, and they're aiming to drive that 57 million figure down to zero. Let’s (just) do it.
| |
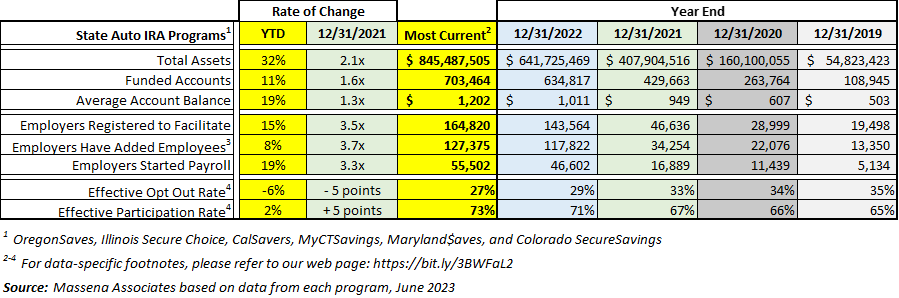
*Fresh!* State Auto IRA Program Metrics | |
|
What’s up! Colorado SecureSavings – welcome to the fold, and thank you for sharing your progress!
Assets. Saver assets are up 32% year-to-date and 2.1x since December 2021 to $845 million, as OregonSaves reaches the significant $200 million milestone. Average account balances across the programs are over $1,200. Longer term balances are higher.
Funded accounts. The six programs shown here now aggregate to over 703,000 funded accounts. For comparison, funded accounts are up 1.6x since December 2021, up about 2.7x since December 2020 and up about 6.5x since December 2019 – and up in 2023.
Facilitating employers. Over 164,000 employers are now registered to facilitate a state Auto IRA. Of that number, more than 55,500 have begun forwarding payroll contributions for savers.
| |
State Facilitated Retirement Programs - Fresh Highlights | |
|
Colorado (workforce 3.2 million) – The Colorado SecureSavings Program Board met on June 26, 2023. The agenda included an update from Executive Director Hunter Railey and team on staffing updates, NAST (new states getting involved), the last wave deadline on June 30, 2023, and CDLE outreach for enforcement (not to start until 2024). Provider Vestwell presented an overview on enrollment/outreach and the initiation of monthly metrics reporting. In advance of the 3rd employer deadline, the program had over 9,000 employers registered, 19,000 funded savers accounts - totaling almost $5 million in saver assets. Average account balances are over $250 and monthly contributions are $135. Segal Marco Advisors provided a performance and allocation update. Finally, ED Railey presented a partnership update with Maine’s Executive Director Beth Bordowitz - the discussion included aligning statutory language, and a proposed pilot timeline of October 2023, in preparation of a full launch in early 2024,
| |
|
Hawaii (workforce 676,000) - The Hawaii Retirement Savings Program Board met on June 27, 2023, to progress its planning. Key items on the agenda included overview of appropriations and approval for the DLIR to expend program funds to initiate and administer the program, hiring staff including Executive Director and Program Specialist. The agenda also included discussion of pursuing a feasibility study.
| |
|
Illinois (workforce 6.4 million) - The Illinois Secure Choice Board met on June 15, 2023. Key items on the agenda included two action items - authorization to amend the Secure Choice Program Manager Agreement and approval of administrative rule changes.
| |
|
Maine (workforce 677,000) – The Maine Retirement Savings Board met on June 21, 2023. Key items on the agenda included a summary report from Executive Director Beth Bordowitz, Board discussion and approval of the procurement and website privacy policies as well as authorization to enter into agreements with Colorado SecureSavings, Vestwell and related parties.
| |
|
Oregon (workforce 2.2 million) - OregonSaves has reached a significant milestone - $200 million saved for retirement, coinciding with the rollout of the program to Oregon’s smallest businesses. Launched with a pilot phase in July 2017, OregonSaves became the nation's first state auto-IRA and the first program to roll out to business with four or fewer employees. “OregonSaves is delivering, and it's more than a visionary Oregon idea - it has served as inspiration for other states - with more than $800 million saved nationally for a secure future,” said State Treasurer Tobias Read in an official statement.
| |
|
Virginia (workforce 4.3 million) – *Very exciting* RetirePath opened to all eligible employers on June 20, 2023 (see official statement here). About 8,700 Virginia businesses will receive their first registration notice by July 1, 2023. For employers covered by the program in 2023, the RetirePath registration deadline is February 15, 2024. To encourage early participation, RetirePath is providing recognition to Virginia businesses that register before September 18, 2023.
| |
|
Thank you to our friends at the Georgetown Center for Retirement Initiatives for an informative webinar on the passage of this year’s latest new state programs, along with an update on the progress of existing programs. Here’s the scoop!
This legislative session was not only intensely busy, but extremely productive. At least 22 states have introduced bills to establish new retirement savings programs, amend existing programs, or form study groups to explore their options. As of June 2023, three new programs have been passed by legislatures: Minnesota (auto-IRA), Missouri (a voluntary Multiple Employer Plan or MEP), and Nevada (auto-IRA), which brings the total number of state programs to 19. In addition, one existing program – Vermont – changed its program from a voluntary MEP to an auto-IRA program. States also are now actively exploring interstate partnerships, which can only help to make these programs even more efficient and low cost.
| |
|
C O M I N G U P
-
Oregon (workforce 2.2 million) – The next meeting of the OregonSaves Board is tentatively scheduled for August 15, 2023.
-
Virginia (workforce 4.3 million) – The next meeting is tentatively scheduled for August 23, 2023.
-
Massachusetts (workforce 3.6 million) - The next meeting is tentatively scheduled for August 28, 2023.
-
Maryland (workforce 3.2 million) – The next meeting of the Maryland$aves Board is scheduled for September 11, 2023.
| |
How Do Firms Respond to State Retirement Plan Mandates: What We’re Learning | |
|
We take a look at a recent working paper from Adam Bloomfield, Kyung Min Lee, Jay Philbrick, and Sita Slavov, published by the NBER this month. Thank you to our friend Jack Vanderhei for highlighting this new research.
This work shows that state auto-IRA programs appear to be having a positive impact on retirement security both in the form of their own extension of coverage, and in the takeup of private sector plans – by both employers and by covered employees. Very interesting. Read on.
The paper explores how state auto-IRA legislation influences employer decisions regarding employer-sponsored retirement plans (ESRPs). Auto IRA legislation requires employers to either offer ESRPs or facilitate automatic payroll deductions into individual retirement accounts (IRAs) established for workers by the state. The research found that auto-IRA policies increased the probability of an individual working for a firm with an ESRP by about 3%, and the probability of the individual participating in the ESRP by 33%. The policies also led to a 3-5% rise in the number of ESRP participants at the average firm.
Contextualizing these findings, over the past few years, state auto-IRA programs have been increasingly adopted. Since 2015, fifteen states have authorized, and seven states have implemented, these programs to provide retirement savings options for workers without access to workplace plans. As our readers know, the programs are primarily privately managed and automatically enroll workers, though employees can opt out. One concern by the existing community has been whether these state programs might "crowd out" the private market for plans, leading businesses to avoid adopting their own 401(k)s or even terminate existing plans.
However, real-world observations, particularly from early adopters like California, Illinois, and Oregon, indicate that auto-IRAs are not competing with the private retirement plan market but complementing it. Despite the economic impact of COVID-19, these states continued to create new plans in 2020 at rates comparable to or even higher than the national average, without significantly increasing the rate of plan terminations.
A previous survey suggested that among businesses with existing retirement plans, only 13% said they would switch to a state-facilitated program if available. On the contrary, 51% of small employers without plans stated they would start their own plan rather than enroll workers in the state-facilitated program. Recent data shows that the rate of new plan creation remains high in states with auto-IRAs, indicating that these programs are more of a catalyst than a substitute for private retirement plans.
It’s early days and the numbers are small, but state auto-IRA legislation appears to be positively influencing the provision of ESRPs and encourages employee participation. The evidence thus far indicates that these programs complement rather than compete with the private sector market for retirement plans, especially for businesses that cannot afford their own plans. As more states adopt these programs, ongoing research will be crucial to understanding their long-term impacts and how employers respond to such initiatives.
Read the original paper here: Bloomfield, Adam, Kyung Min Lee, Jay Philbrick, and Sita Slavov. 2023. "How Do Firms Respond to State Retirement Plan Mandates?" NBER Working Paper Series, No. 31398. Cambridge, MA: National Bureau of Economic Research. http://www.nber.org/papers/w31398.
| |
We’ve got cool stuff for you this week - take a gander: | |
|
Top of the List: Aspen’s Financial Security Program has just released The New Wealth Agenda: A Blueprint for Building a Future of Inclusive Wealth. In it, the program proposes an audacious, achievable goal: “By 2050, we must increase by ten-fold the wealth of households of color and those in the bottom half of the wealth distribution in the United States.” In the report, our friends identify eight objectives, proven solutions and promising innovations. The New Wealth Agenda is intended to be a catalyst for the critical work to come. Read. Adopt. Progress.
Want to know when each of the state programs launched? Here's a great view from our friends at the Georgetown Center for Retirement Initiatives on state program employer registration timelines (by wave). An excellent resource - thank you Angela Antonelli.
What Can Welfare Reform Teach Us? Don’t miss out on this insightful post by Geoffrey Sanzenbacher. Most of us weren’t around when Aid to Families with Dependent Children (aka Welfare) was first developed. Many of us, though, remember the Welfare reforms of the 1990s. Did they work? Yes. and No. It depends on your perspective. Geoff provides a useful analysis.
Discover the significant impact of place on health and happiness in the upcoming Longevity Book Club Conversation on July 13th. Author Ryan Frederick explores the importance of place – where you live – especially in the second half of your life. We care. A lot. Check out the pix at the bottom of this edition! And to learn more for work and pleasure, catch this opportunity to engage with the author and have your questions answered. Register here.
| |
What an Amazing Newsletter, and, We Need Pix! | |
Not sure this qualifies as a Pic of the Week, but we’re at the candy stand so let’s get some TAFFY! It’s our new favorite way to talk about retirement savings with anyone under the age of 40. TAFFY - tax advantaged financial freedom for YOU. #getsome #welovetaffy | |
|
And when you need a break in the action, this works - and this - and this.
Have a great week (end)!
| |
|
That’s it for this edition. ❤️ Hug your people and change the world.
If you like this piece, please stick with us. We’ll be back in about two weeks. If you don’t like it, please unsubscribe below. Comments for us? Please let us know. Want your own subscription? Request one here. All information shared is from public sources or used with express permission.
| |
Massena Associates provides process, policy, and implementation consulting on retirement savings programs and products.
Our clientele includes public entities, policy organizations, and private sector providers. Our specialty – efficient, targeted results. We are an active speaker on retirement security topics, including state-facilitated programs, MEPs and more.
If you’d like to explore working together, we welcome the conversation. Connect with us here, and at 339-236-0684.
| |
|
Looking for a great retirement savings innovation resource? Led by Dr. Alicia Munnell, the Center for Retirement Research at Boston College develops and hosts terrific content and proprietary research related to states, financial security, social security, and more.
The Defined Contribution Institutional Investment Association (DCIIA) is dedicated to enhancing the retirement security of America’s workers. To do this, DCIIA fosters a dialogue among the leaders of the defined contribution community who are passionate about improving defined contribution outcomes. DCIIA's site provides a range of public and member-specific resources.
The Georgetown Center for Retirement Initiatives, Exec Angela Antonelli, provides excellent information on state-based and other retirement security innovation and policy.
Pew’s Retirement Savings Project studies the challenges and opportunities for increasing retirement savings and is another great resource - check out the work of John Scott and his terrific team.
If you want a great source of broad-based, consumer-focused retirement news, Jeffrey H. Snyder’s The Morning Pulse is your ticket. You can subscribe here.
| | | | |