|
RETIREMENT SECURITY MATTERS
A forum for retirement savings innovation, together.
Vol 102 | May 21, 2026
| | |
Greetings! Greetings! welcome to Retirement Security Matters—where we talk about retirement readiness innovation across public and private spaces. | |
Before we go deep, take a beat, grab an iced coffee. Retirement policy debates are heating up, and there’s no shortage of perspectives flying around Washington and the states. We love the smart conversations, fresh ideas, and genuinely cool developments. Got that joe and a moment for yourself? This week bring you Teresa Ghilarducci, updates from the states, insights from the just-held Aspen Leadership Forum on Retirement Savings, and, of course, a fresh batch of Hot Sauce! and Pix of the Week to keep things lively:
| | Wealth is Dignity: Teresa Ghilarducci on TrumpIRAs and Evidence-Based Design | | |
One of the nation's sharpest minds on retirement security talks universal access, automatic enrollment, the new TrumpIRA executive order—and why she believes every worker deserves a batch of future Saturdays.
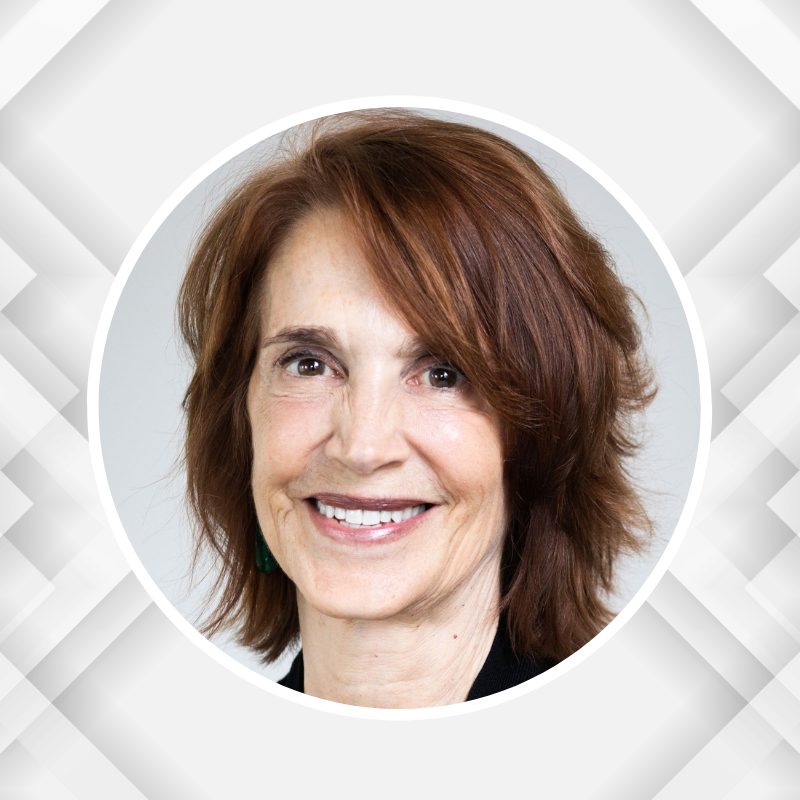
Teresa Ghilarducci has spent four decades asking one question: how do we build a system where every worker gets to cash in their deferred Saturdays? Retirement, she told us, is really just paid time off—deferred paid time off. And whether or not you get to cash those Saturdays in depends almost entirely on whether the system was built to include you.
We sat down for an extended conversation. Here’s where we started—and the key ideas that followed.
Lisa Massena: Teresa, you've dedicated your life's work to retirement savings, access, and outcomes. Where do you see us today?
Teresa Ghilarducci: I got truly interested in negotiating pension plans when I was a graduate student at Berkeley, working with the labor center. One of the unions that came to us happened to be my own mother's union. I helped negotiate her defined benefit plan, and also one at Stanford University.
I started my career helping improve defined benefit plans and creating defined contribution plans to sit on top of them. But it became clear pretty quickly that linking someone's retirement security to one or two employers was never going to be stable. People move. Work changes. So, I always looked ahead to a system that broke the link between the employer and someone's old-age security—while keeping the link between work and old-age security.
We’re just getting started – and don’t miss the TrumpIRA part! pick up the rest of our conversation HERE.
Key ideas from our chat:
- On the power of long term saving: "Start at 25 and save 3%—along with Social Security—and you can maintain your lifestyle in retirement. Wait until 40 and you'll need to save 15%. That's the power we're trying to unlock for everyone."
- On automatic enrollment: "It's absolutely necessary. It's vital—just like automatic enrollment is vital to Social Security. Everybody loves their Social Security, but nobody would have signed up for it voluntarily."
- On state and federal programs: After 20 years of state innovation it may be time for a federal solution, just as it was when Social Security lifted programs from Wisconsin and Minnesota into a national framework.
- On the TrumpIRA executive order: A meaningful step. TrumpIRA.gov will launch in early 2027 as a marketplace where workers can compare and enroll in low-cost IRAs linked to the Saver's Match. The open question is whether automatic enrollment follows—because without it, we've built the door but left it up to people to walk through on their own.
- On age justice: The longevity gap by socioeconomic class is growing. Providing for people's old age is a step toward age justice—if you have some savings when you are forced out of the workforce, you can make a real transition.
- On the future: "In the next five years, I would like to see everyone who is contributing to Social Security also contributing to their own retirement account. Just like that—as a matter of course, as part of the infrastructure of being a worker in America."
| | "We're not just helping individuals who haven't been able to save — we're bringing whole groups into the system who have been structurally left out." | | |
You’ll want the details – jump HERE.
A labor economist and holder of the Bernard and Irene Schwartz Chair at The New School for Social Research, Ghilarducci has championed (more) universal retirement security for decades. Her most recent book, Work, Retire, Repeat (University of Chicago Press, 2025), landed as the retirement policy conversation reached a new peak. In 2021, she co-authored a landmark white paper with economist Kevin Hassett—now Director of the White House National Economic Council—proposing that all workers gain access to a retirement savings plan modeled after the federal Thrift Savings Plan. That paper laid the intellectual groundwork for the executive order President Trump signed on April 30, 2026.
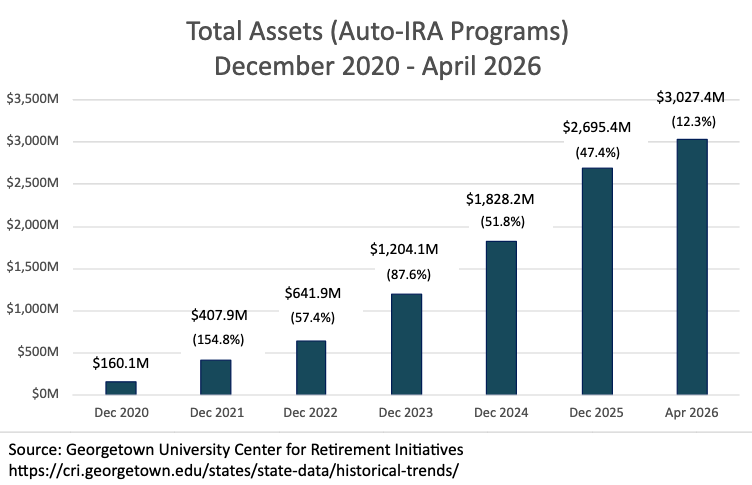
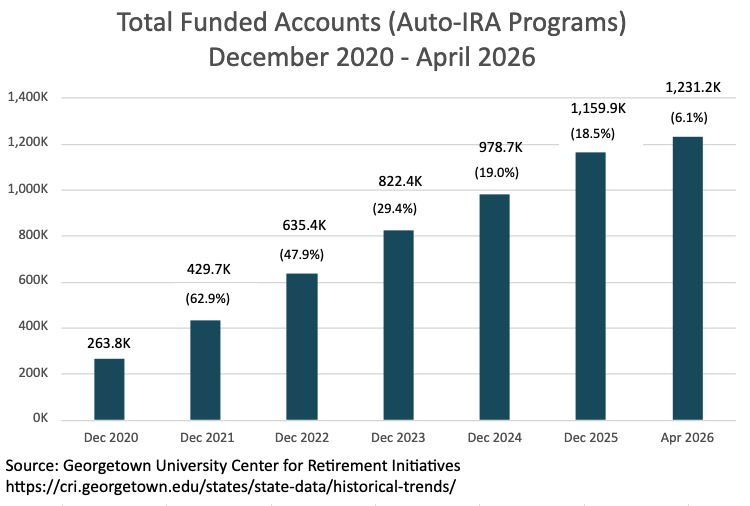
| | State Auto IRAs: Get Smart Here | | The numbers keep moving—fast. For your use, here is the latest snapshot. LOOK AT THOSE TOTAL ASSETS. We’ve popped over the $3 billion line. | | … and you know here at RSM what we care about EVEN MORE is the level of funded accounts. We’ve been hovering around the 1.2 million funded account level most of this year. We’re now at 1,231,200—up 71,000 accounts from year end 2025, and up 20% from a year ago. | | |
Please read these charts for me! We got you:
- $3 billion+ in total assets across state-facilitated retirement savings programs—the latest milestone in a rapid growth curve.
- 1.2 million+ funded saver accounts across all programs, a 20%+ increase in one year.
- 22 enacted state programs (20 states + 2 cities), with 17 fully open to all eligible employers and workers as of April 2026.
- 15 are auto-IRA programs (CA, CO, CT, DE, IL, ME, MD, MN, NJ, NV, NY, OR, RI, VT, VA); 2 others are MA (MEP) and WA (Marketplace).
- CalSavers leads with $1.6B+ in assets, 629,000 accounts, 281,000 participating employers.
- Two new programs enacted in 2026: Utah Retirement Exchange (March 24) and Mississippi Work and Save Program (April 8).
- Two states amended their programs in 2026 to lower employer coverage thresholds: New Jersey and Virginia.
- Hawaii and Washington are in active implementation, targeting 2026 and 2027 launches respectively.
- Growth pace: it took 6 years to reach $1B, 18 months to reach $2B, and only 11 months to reach $3B.
A special thank you to Angela Antonelli and the Georgetown Center for Retirement Initiatives for the program metrics data shared above. You’ll find more detailed metrics and information on their site here. Additional sources include 401k Specialist, May 15, 2026; Pew Charitable Trusts, 2026.
| | States in Action - What to Watch | | |
These three are worth a minute of your time:
MISSISSIPPI (MS)
-
Work and Save Program enacted April 8, 2026—the 22nd state program enacted nationwide.
- Opt-out auto-enrollment structure; phased implementation targeting full rollout by July 1, 2028 (workers contributing by August 1, 2028).
- Exchange platform must be set up no later than November 2, 2026, and begin accepting applications from plan providers.
- Would help an estimated 492,000 Mississippi workers save for retirement.
-
More color here—and thank you to our friends from ASPPA for this piece
-
Why it matters: we see the more conservative states looking for ways to serve their uncovered workers. This bill, while emphasizing the voluntary nature of the program for employers and workers, also uses a lot of traditional Auto IRA language, and references automatic enrollment—a key feature for broad adoption and use. The program is not required to launch until 2028—a very long time in the future—time to learn from and then contribute to the Auto IRA body of knowledge.
NEW YORK (Secure Choice)
-
Launched October 2025; mandatory for employers with 10+ employees. The program rolls out fully by July 15 of this year. Friday May 15 was the deadline for employers with 15 or more employees to register or confirm exemption.
- Default contribution rate: 3%. Auto-enrollment with opt-out option.
- New York City's separate program was absorbed into the state program.
-
Why it matters: size. Sheer size. New York’s private sector workforce is about 8.5 million people – with about 3.5 million uncovered. It always takes time but we expect to see a significant number of new funded accounts established in 2026. Are you a betting person? We’d love to see your estimates!
COLORADO (SecureSavings / Partnership for a Dignified Retirement)
- Lead state in the PDR partnership, which now includes ME, DE, VT, NV, MN—six states total.
- Program fully active. Partners' combined assets exceed $144M from 100,000+ savers.
-
Why it matters: One, the partnership programs of Colorado and Connecticut allow states—both large and small—to launch and get busy with minimal muss and fuss. And two, it’s getting others busy as well. April 2026 Pew research confirms that Colorado is among seven states where new plan formation kept pace with or exceeded national averages post-auto-IRA. In fact, Colorado had outstanding numbers—with new plan formation of 18.4% in 2023 vs. 12.6% in 2022.
… and a bonus state. We can’t leave out our favorite and the OG:
OREGON (OregonSaves)
- $445M+ in assets at year-end 2025; 190,877 payroll-contributing accounts.
-
Why it matters: Steady, mature growth. Oregon has seen it all—they were first into the pool. Oregon established a core design that suits the state and, we think, the nation. The program has been live under three state treasurers, two program administrators, and one pandemic. And they just keep ticking, and enrolling, and supporting retirement security. #welldone Oregon ❤️
| | Aspen Leadership Forum on Retirement Savings: view from the room | |
For the retirement nerds—a dispatch from the 10th annual gathering of retirement security leaders—where TrumpIRAs, automaticity, and the design of enrollment pathways took center stage.
The Aspen Institute Financial Security Program convened its 10th Leadership Forum on Retirement Savings. The annual event brings together leaders from industry, government, consumer advocacy, and academia under Chatham House Rules to work through some of the toughest problems in the field. This year's forum landed in the middle of one of the most consequential federal moments for retirement policy in a generation.
President Trump signed the TrumpIRA executive order on April 30, 2026, just weeks after the forum. And much of what participants wrestled with at the gathering—about enrollment pathways, design choices, automaticity, and who gets left out—turned out to be precisely the right set of questions.
IYKYK: What the Executive Order Does
At its core, the EO establishes TrumpIRA.gov, a federally facilitated IRA marketplace expected to launch in 2027, where workers can compare and enroll in private-sector IRAs. Providers listed must maintain low administrative costs (annual expense ratio capped at 0.15%) and may not impose minimum-contribution or balance requirements. The platform integrates with the Saver's Match—up to $1,000/year for eligible lower-income workers—which goes into effect in tax year 2027.
The order also references charitable contributions to retirement accounts by tax-exempt organizations (Section 4)—a wrinkle that raises questions about IRA rules. It also prompts a central design question: how do you move from a voluntary marketplace to the full TSP-like experience the President referenced—namely, automatic enrollment into a plan with a meaningful employer contribution?
What We Heard:
-
Section 530A/Trump Account enrollment uptake offers a useful preview: as of April 2026, millions of children (4 million? 5 million?) had been signed up for accounts, with 1.2 million qualifying for the $1,000 pilot contribution. Even forum participants were surprised by the numbers. The lesson: awareness and incentives. May we say, our Leader-in-Chief is also an excellent marketer?
-
Does the Saver's Match need to reach more people? Under current rules, workers earning roughly $20,000 or less, who also make retirement savings contributions, qualify. 1 – that’s a very low earnings level to be able to afford to save. Should the threshold be higher to include a wider swath of Americans living on low incomes. 2 – millions of qualifying Americans currently lack an account in which to receive it. Their employer doesn’t offer a retirement plan; they’re in a non-Auto IRA state; their state Auto IRA hasn’t reached them yet. See our lead story for more thinking here.
-
Participants wrestled with alternatives to traditional employer-based auto-enrollment for a federal option, including pathways through tax filing, payroll systems, and other government touchpoints.
-
The affordability tension is real: workers who need retirement savings most are also navigating the highest costs for housing, childcare, and education in recent memory. Incentives must feel possible, not punitive.
-
Asset limits in means-tested programs can actively work against retirement savings accumulation—a structural contradiction the forum flagged and that policy design needs to resolve.
| "Federal action toward addressing the access gap is significant, even if the initial design falls short of what we know to be true about the importance of automatic enrollment." | |
Read Aspen's excellent take on these convos: Trump IRAs Are Coming. Let's Make Them Work for Those Who Need Them Most.
Why it matters: We appreciated seeing policy wonks, retirement security nerds, and deep thinkers from all walks attempt to lay down their preconceived thinking and get outside their own heads into fresh thinking. Ourselves included. Good things are coming. They will not be perfect. It’s time to push, pull, and get out of the way.
| Hot Sauce! Cool Stuff - Just for you. | |
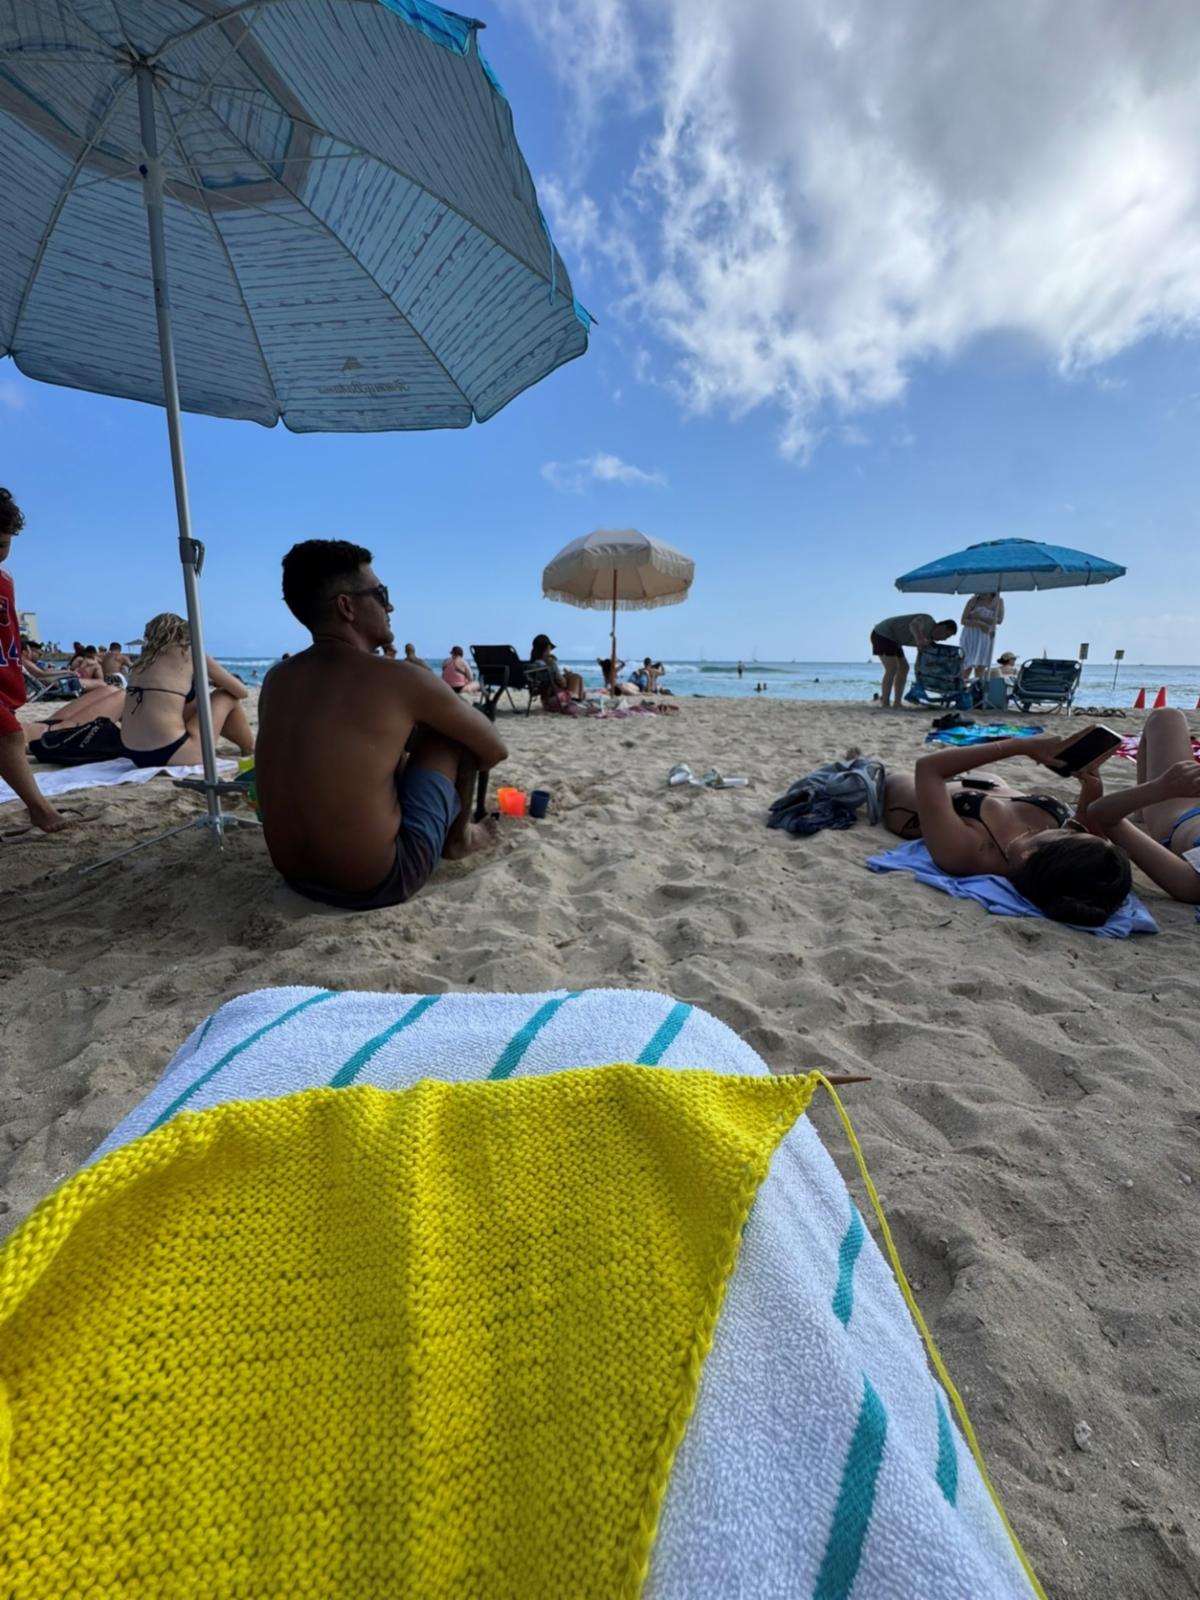
Curation today -- some good research and a few favorite reads and listens. Were we oceanside while we were thinking of you? 🌊Yes, yes we were. Just trying to set a good example!
5. Morningstar: A Simulation of Universal Retirement Plan Coverage
Morningstar models what federal auto-enrollment would mean for retirement wealth—and the numbers are striking. An estimated 32.3 million workers would enter the retirement savings system under a federal auto-enrollment plan, even after accounting for opt-outs. With Congressional action, the research suggests U.S. retirement wealth could grow by as much as 77%. This is the quantitative case for automaticity—and it maps directly to the TrumpIRA design question. Required reading. Read on →
4. DCIIA: What Do Plan Consultants and Advisors Think About the Future of DC Innovation?
The Defined Contribution Institutional Investment Association asked plan consultants and advisors what they think is coming—and the results are illuminating. If you work anywhere near the institutional DC space or the intermediary channel, this is your pulse check. Pairs nicely with the state auto-IRA story: as the public sector expands coverage, the private sector is rethinking its DC architecture too. Read on →
3. Boston College CRR: Can Service Providers Convince More Small Firms to Offer 401(k)s?
By Anqi Chen at the Center for Retirement Research at Boston College—a welcome private-sector complement to the public-program coverage conversation we've been having. Small firms are the coverage gap. Can the 401(k) industry close it from the private side? Chen digs into what service providers can actually do. Worth a read alongside the state auto-IRA data—different levers, same problem. Read on →
2. Into Our Brain: Leonard: My Fifty-Year Friendship with a Remarkable Man
By David Fisher and William “Captain Kirk” Shatner. We loved this book for its quiet Hollywood moments and a walk down memory lane in the company of two screen heroes. For a Trekkie treat: listen to the audio version. We got ours using the Libby app—free with a library card. Highly, highly recommend. Get your own →
1. 🎵 In Our Ears: Apple Music
We are absolutely in love with Apple Music's The Works playlist. It helps us work and think better—and it might just do the same for you. Put it on. Let your brain breathe. Check it out →
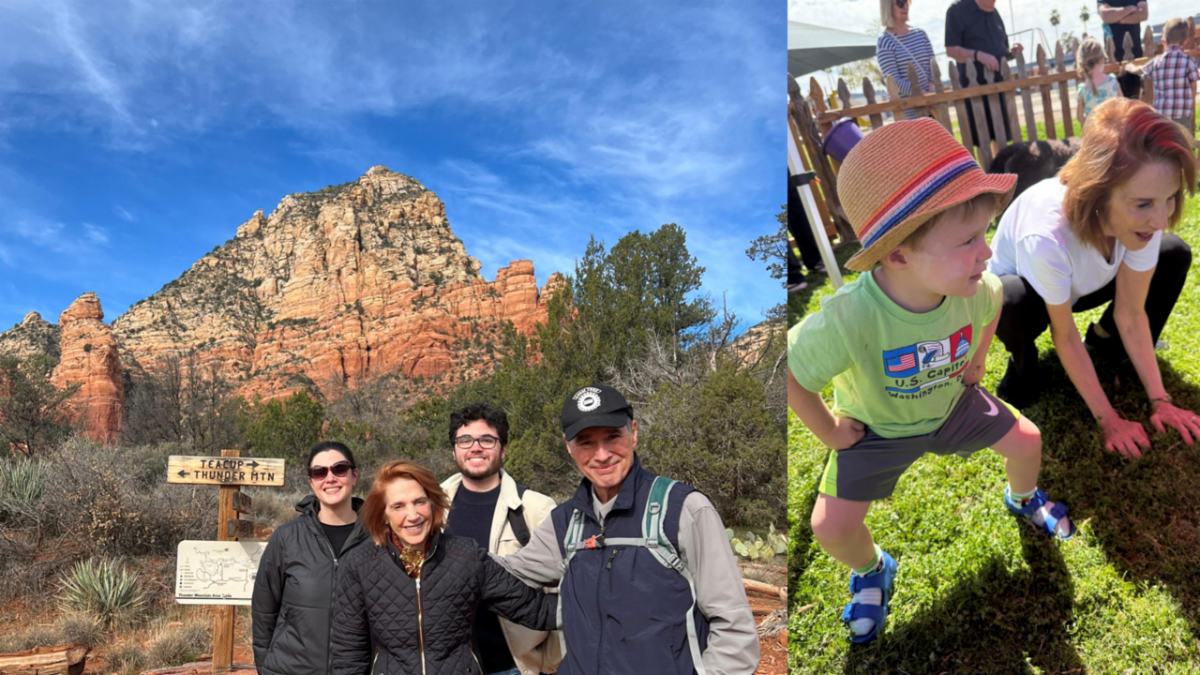
| Pix of the Week! Moments that Matter | | Red rocks, blue skies, and good company. Teresa Ghilarducci with husband Rick McGahey, step-daughter Genevieve McGahey and her boyfriend Tommy Rust pause for a family photo along the trail—with Teresa and grandson Julian fully embracing their inner bunnies. 🐇 LOVE! | | |
… and, yes, this is Retirement Security Matters—the Ocean Series.
We were thinking of you, we promise.
| | |
That’s it for this edition. ❤ Hug your people and change the world.
| | |
Massena Associates provides process, policy, and implementation consulting on retirement savings programs and products.
Our clientele includes public entities, policy organizations, and private sector providers. Our specialty – efficient, targeted results. We are an active speaker on retirement security topics, including state-facilitated programs, MEPs and more.
If you’d like to explore working together, we welcome the conversation. Connect with us here, and at 339-236-0684.
| | |
Looking for a great retirement savings innovation resource? The Center for Retirement Research at Boston College develops and hosts terrific content and proprietary research related to states, financial security, social security, and more.
The Defined Contribution Institutional Investment Association (DCIIA) is dedicated to enhancing the retirement security of America’s workers. To do this, DCIIA fosters a dialogue among the leaders of the defined contribution community who are passionate about improving defined contribution outcomes. DCIIA's site provides a range of public and member-specific resources.
The Georgetown Center for Retirement Initiatives, Led by Angela Antonelli, GCRI provides excellent information on state-based and other retirement security innovation and policy.
Pew’s Retirement Savings Project studies the challenges and opportunities for increasing retirement savings and is another great resource - check out the work of John Scott and his terrific team.
If you want a great source of broad-based, consumer-focused retirement news, Jeffrey H. Snyder’s The Morning Pulse is your ticket. You can subscribe here.
| | | | |