|
RETIREMENT SECURITY MATTERS
A forum for retirement savings innovation, together.
Vol 96 | November 20 2025
| | |
Greetings! Greetings! welcome to Retirement Security Matters—where we talk about retirement readiness innovation across public and private spaces. | |
It’s almost THANKSGIVING 🦃 here in the US—are you ready? Grab a cocoa—we’ve got a fire crackling in the little cabin and we invite you to join us for a few minutes of pure brain pleasure. Read on.
We got you today with:
- Michael Kreps on 2025's Quiet Retirement Revolution
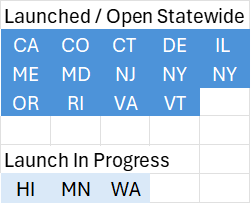
- States by the Numbers—Where We At?
- And What Else—Auto IRAs in the News
- Reporting from the Road—Our Favorite Academics Share Spice
- Hot Sauce, Cool Stuff—SS, ESA, PFML and Jimmy Buffett … and
- Pix of the Week! ❤️ Pup Style
| | What's Next for Retirement?
Michael Kreps on 2026's Make-or-Break Moments | | |
The retirement savings landscape is undergoing perhaps its most significant regulatory shift in 15 years—and 2026 could determine whether two landmark programs transform the system or falter at the starting line.
In a candid conversation, Michael Kreps, Chair of Groom Law Group's Retirement Services Group, reveals why the Department of Labor's pivot from aggressive enforcement to innovation-friendly regulation marks a "pretty radical change," how Trump accounts and the Saver’s Match represent make-or-break tests for public-private infrastructure, and why lifetime income may finally be ready for its moment after two decades of groundwork.
But Michael doesn't shy away from concerns: the intense politicization of plan investments wastes energy on "fringe issues," while the retirement system struggles with mission creep—being asked to serve as emergency fund, disaster relief, college savings, and everything in between.
His prescription? "Let's stop trying to make 401(k)s into everything for all people—or if we want that, then let's make them into a savings account that's better suited."
Spicy! 🌶️
| |
Quick Nav: Here’s what we cover
-
The 2025 Regulatory Revolution — Why this DOL shift is different from Trump's first term
-
2026's Dual Challenge — Trump accounts and Saver’s Match face critical implementation tests
-
Lifetime Income's Long-Awaited Moment — After 15-20 years, the dam may finally break
-
The Politicization Problem — How ESG debates distract from real retirement challenges
-
The Big Picture — Progress on coverage and portability vs. the "manic" policy problem
-
The Tontine Surprise — Why collective defined contribution deserves fresh attention
| |
READ THE FULL INTERVIEW
Why This Matters Now
With over 600,000 retirement plans navigating new regulatory waters, plan sponsors face a unique moment: the chance to become true retirement hubs for participants across their entire lives—not just the accumulation phase. Kreps observes that sophisticated employers increasingly design plans "for all stages of life," from 20-year-olds just starting to save to 80-year-olds needing guaranteed income streams.
The infrastructure decisions made in 2026—particularly around the clearinghouse systems needed for Trump accounts and the Saver’s Match—could either unlock unprecedented portability and participant reunification, or represent a missed opportunity to solve longstanding system fragmentation.
| "If you wanted to ship materials from Philadelphia to New York, you might build a road to do that. But then lots of stuff can go down those roads—you might build it to ship beds, but couches and fruit can go down those roads too." — Michael Kreps on building retirement infrastructure that serves multiple purposes | |
READ THE FULL INTERVIEW
Explore Michael Kreps' insights on regulatory shifts, emerging products, tontines, and what plan sponsors should be thinking about as we head into a pivotal year for retirement policy.
Like this piece? Let us know! Want to connect with Michael? Follow his work here. You can also reach him on LinkedIn. Or reach out by email for an even faster chat.
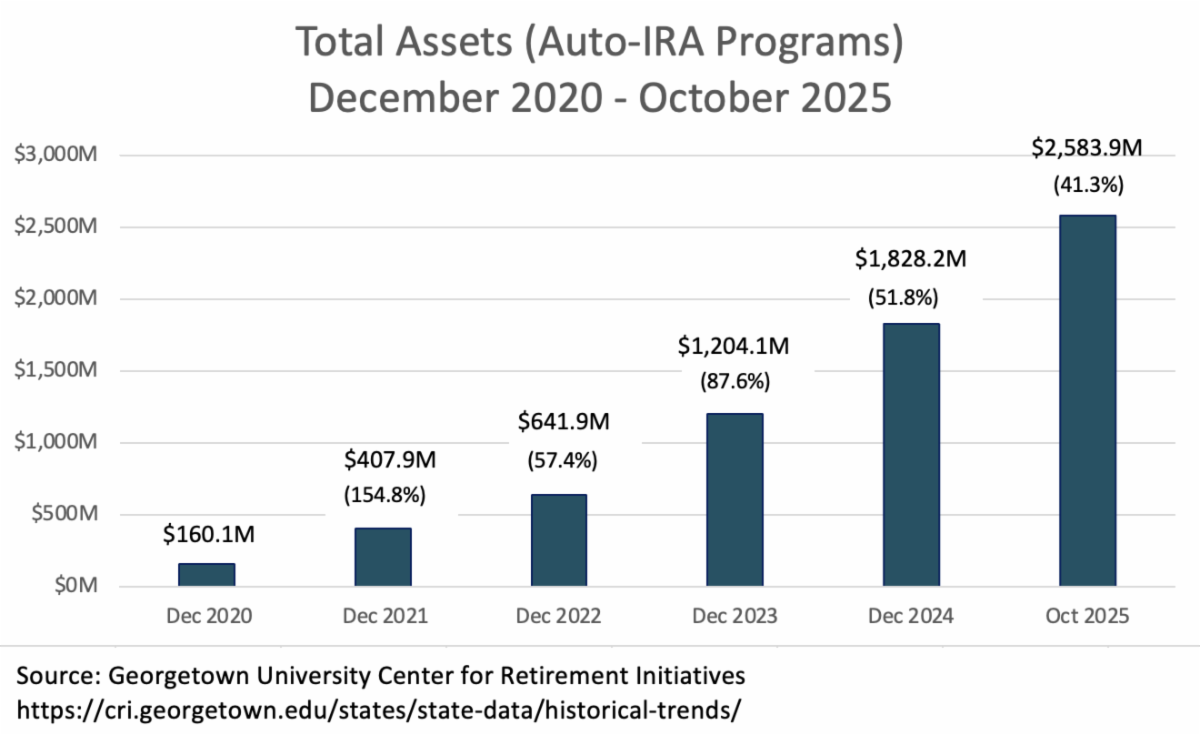
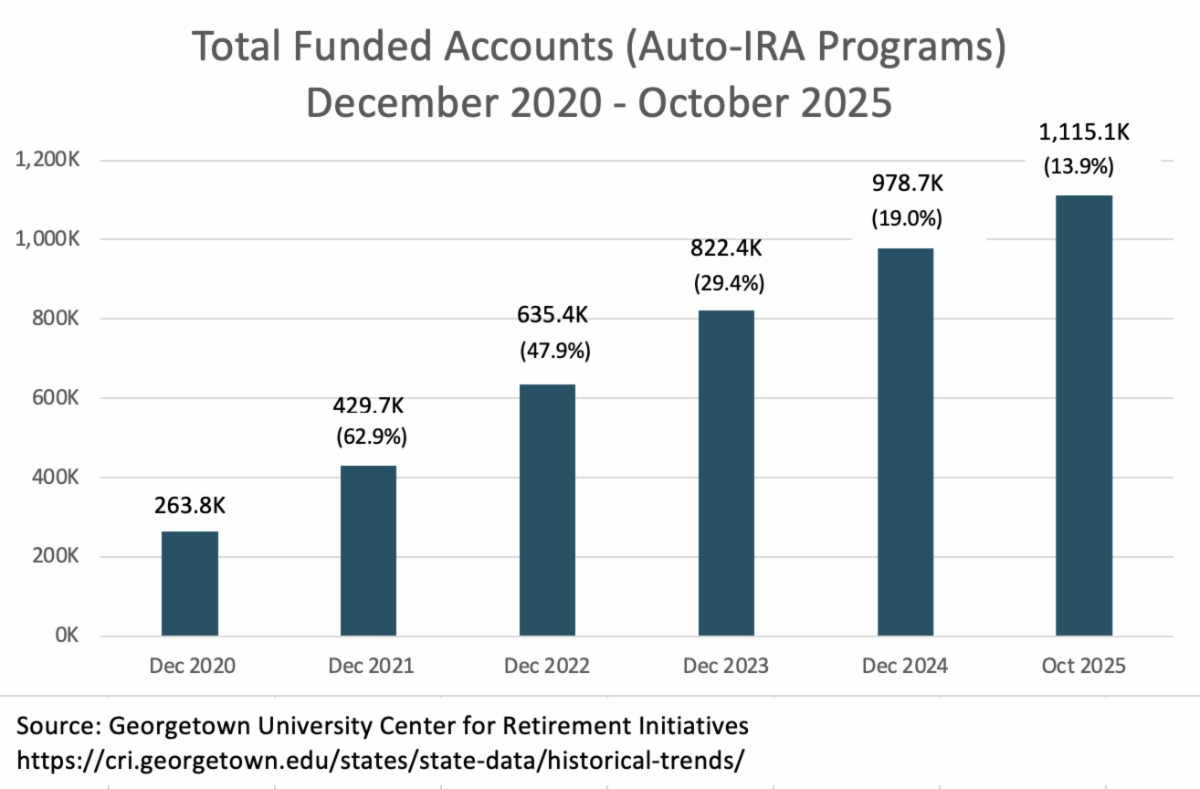
| | By the Numbers: State Auto IRAs Today | | The Trend is our Friend—Folks, we can’t unsee that in the short five-year period from late 2020 to today, Auto IRA assets have grown from about $160 million to nearly $2.6 billion. And funded accounts are up more than four-fold. We started 2021 with about 264,000 funded accounts, and by October of 2025 Auto IRA programs across the country are serving more than 1.1 million savers. | | |
A very crude estimate across the programs puts average account balances at $2,317—although many are higher, and many—especially newer accounts—are lower.
We expect another strongly steady year in 2026 as states of various sizes pursue their program launches in earnest. New York State is big.
A special thank you to Angela Antonelli and the Georgetown Center for Retirement Initiatives for this data. You’ll find more detailed metrics and information on their site, here.
| | What Else I Up: State Auto IRAs in the News. | | Where We Are / Fall 2025. | |
*FANZONE*—New State Programs Open for Savings and Making Progress:
New York Secure Choice Launch—with the support of an array of state officials, New York Governor, Kathy Hochul, announced the launch of the New York State Secure Choice Savings Program on October 8. The program provides retirement savings access to over 1.5 million New Yorkers who lack employer-sponsored plans. Employers with at least 10 employees, in business for two years or more, and without a qualified retirement plan are now required to register and facilitate employee participation. Compliance dates come in three waves: employers with 30+ employees must register by March 18, 2026; those with 15-29 employees by May 15, 2026; and those with 10-14 by July 15, 2026.
Rhode Island—RISavers Opens—Connecticut and Rhode Island announced the finalization of their partnership agreement on September 24, 2025, supporting the launch of the new RISavers program, which opened to all eligible employers on October 21, 2025. Provider Vestwell will run the program in coordination with Connecticut's treasury, and you can check out the program’s new website here.
Nevada NEST—Registration Deadline—Nevada's Employee Savings Trust (NEST) program launched on July 1, 2025, with employers required to register by September 1, 2025. By the September 1 deadline, businesses with six or more employees were required to either offer their own retirement plan or enroll their employees into NEST. As of October, the program has accumulated over $2 million in more than 11,000 funded accounts.
Want more goodies? We recommend the Georgetown site for the most current daily details and news across the states.
| |
Key Trends 🍂 This Fall:
-
Accelerating Growth: The last few months have seen unprecedented growth in assets and participation, with the fastest $500 million asset increase in program history. We like using the word unprecedented in positive ways.
-
Geographic Expansion: Rhode Island's launch brings the Northeast more fully into the Auto IRA ecosystem, while Nevada represents significant Western expansion. We’re still looking for our first Southern state … who will it be?
-
Partnership Progress: The Colorado-led partnership model continues to attract new states, demonstrating cost-effectiveness and fast time-to-market for partner (and sometimes smaller) states. And we’ve seen the formation of a new partnership—as Rhode Island joins forces with Connecticut this season.
-
Maturing Programs: Established programs like CalSavers, OregonSaves, and Illinois Secure Choice showed stable growth with increasing average account balances. The OGs continue to pave the Auto IRA road.
| Reporting from the Road—Academics Ahoy | | |
We had the pleasure of joining Lew Minsky, Nikki Pirrello, Katie Selenski, and a cast of … hundred/s for DCIIA’s 2025 Academic Forum in Minneapolis last month. We may have seen you there!
Why we love this event? It’s nerdy. And it brings together fans, critics, and innovators—all of whom want our system to keep getting better. We learned a few things. We looked a few hard facts in the eye—including some about automatic enrollment, our favorite device. (Thank you, Professor Laibson—we can’t unsee your charts!)
We’ve got a gathering recap for you here—click / do not skip. You’ll be smarter for it. And maybe from your seat you hold part of the solutions. We need you.
Retirement security matters! / Lisa
| | |
We’ve got a quick five for you today—and they’re going to leave you thinking.
5 – from BlackRock’s Jaime Magyera and DCIIA’s Retirement Research Center - Why is retirement confidence diverging between savers and employers? —and would it surprise you to learn that employers are less confident about employee retirement success than employees are? Interestingly, in this survey employers said they felt highly responsible for helping employees generate and manage retirement income. We see a gap between intent and what exists.
4 – from our friends at Allianz—who start by saying “the confidence recession is here” —some excellent analysis of Americans’ understanding of their Social Security benefits—jump to page 9—but you’re going to want to read the entire report to get the goods on planning gaps, gray divorce, retirement savings goals, and more. How Americans feel about retirement in 2025.
3 – Emergency Savings—from Emily Boyle at PlanSponsor focusing on the work of Commonwealth—Research Reveals Access to ESAs Does Not Match Interest. A quarter of LMI families surveyed ranked Emergency Savings as a top three supplemental benefit from a list of 18 options—right after medical and paid leave.
2 – let’s get in the Fun Zone—is this your vision of retirement? Thanks to Healthy to 100: The Science of Social Connection—we now know Latitude Margaritaville is an option. This new newsletter from our friends at the Longevity Project considers how lifespan and healthspan intersect—alongside financial wherewithal. Addressing the questions we’re all thinking about for this retiring population. Get yours here.
1 – And finally—is this a good idea? We’ve seen a couple of Social Security “hookup” ideas in the past week—one focused on Trump Accounts and this one from Kathryn Anne Edwards focused on paid family medical leave. Yes, PFML helps people retire more securely! And what we love about Kedits is that she lays it out so simply, it’s easy to say yes. And we quote:
Paid Family Leave in 90 Seconds:
Expand Social Security to cover paid family and medical leave.
Right now, the program covers
1) Retirement 2) Disability and 3) Death of a Worker (aka Survivors).
Add
4) Paid Family and Medical Leave.
Everything you need for a universal leave program is there:
- the administrative infrastructure,
- coverage of virtually all W2 employees (whether they are full-time, part-time, in one job, in five jobs, or hopping between jobs),
- all self-employed workers,
- a method for collecting taxes,
- and field offices for processing claims located throughout the US.
Paid family and medical leave would require a new payroll tax that the worker and employer contributes to, a new trust fund that receives those tax deposits, and an investment in field offices to handle leave claims. Those leave claims would be more complicated than retirement or survivors claims but less complicated than disability claims.
Done.
Hmmm – seems so simple! Hello wealthiest country in the world!
0 – Bonus—Space Fun Zone—this has nothing to do with retirement, but you could link it to longevity … of the universe … In our ears this week is Alex McColgan of Astrum. Looking for your next favorite galaxy? How about Andromeda (caution, sound!). New planet? Maybe Trappist-1E suits you. Or if you like your crises bigger than the US retirement system, you could go for the Cosmos. Ah, #perspective.
| | And Finally, ... we bring you Pix of the Week! | | OK, so DID YOU WORK OUT TODAY? Cuz our friend Michael DID. We hear Peloton is the way to go, and that live classes with Jenn Sherman CANNOT BE BEAT. Did we work out today? No, no we did not. So Michael has us beat. And we think we hear an extra few beats ... of the 80s ... calling us ... THANK YOU MICHAEL! ❤️❤️❤️ You are an inspiration. And, don't tell the others, you might be our favorite in Washington. | OK SO We’re keeping it simple this week, and as a final tidbit we offer you a little fall cabin delight—from the cutest pup in the Pacific Northwest. Harry says Hi. He says he does have permission to eat that cup. And Happy Thanksgiving to you too. 🍗 | | |
That’s it for this edition. ❤ Hug your people and change the world.
| | |
Massena Associates provides process, policy, and implementation consulting on retirement savings programs and products.
Our clientele includes public entities, policy organizations, and private sector providers. Our specialty – efficient, targeted results. We are an active speaker on retirement security topics, including state-facilitated programs, MEPs and more.
If you’d like to explore working together, we welcome the conversation. Connect with us here, and at 339-236-0684.
| | |
Looking for a great retirement savings innovation resource? The Center for Retirement Research at Boston College develops and hosts terrific content and proprietary research related to states, financial security, social security, and more.
The Defined Contribution Institutional Investment Association (DCIIA) is dedicated to enhancing the retirement security of America’s workers. To do this, DCIIA fosters a dialogue among the leaders of the defined contribution community who are passionate about improving defined contribution outcomes. DCIIA's site provides a range of public and member-specific resources.
The Georgetown Center for Retirement Initiatives, Led by Angela Antonelli, GCRI provides excellent information on state-based and other retirement security innovation and policy.
Pew’s Retirement Savings Project studies the challenges and opportunities for increasing retirement savings and is another great resource - check out the work of John Scott and his terrific team.
If you want a great source of broad-based, consumer-focused retirement news, Jeffrey H. Snyder’s The Morning Pulse is your ticket. You can subscribe here.
| | | | |