|
RETIREMENT SECURITY MATTERS
A forum for retirement savings innovation, together.
Vol 99 | February 19, 2026
| | |
Greetings! Greetings! welcome to Retirement Security Matters—where we talk about retirement readiness innovation across public and private spaces. | |
February brings fresh energy to retirement security. So freshhh 🌊- almost as refreshing as a polar bear dip. This week we have crisp new insights on participant engagement from State Street’s Danielle Gladstone, updated Auto IRA news and numbers, and a look innovation across the retirement landscape. You won’t want to miss: Hot Sauce features a few non-ret gems—from Susan Orlean’s bright storytelling to Formula 1 season prep. Grab that hot drink—especially if you’re in the Northeast—and read on.
What we’re digging into this month:
| | Beyond the Click: Danielle Gladstone on What Really Drives Retirement Readiness | | Danielle Gladstone, Vice President and Head of Participant Engagement at State Street Global Advisors | |
State Street’s Head of Participant Engagement on the surprising power of short-term debt, why financial literacy still trumps fancy tech, and the essential truth about participant engagement that nobody wants to admit
As Vice President and Head of Participant Engagement at State Street Global Advisors, Danielle Gladstone has access to data we dream about—including the findings from SSGA's 2025 Global Retirement Reality Report, which surveyed over 4,300 retirement savers across five countries. What she’s learned surprises.
The Short-Term Debt Revelation
Here’s something that should make us sit up: short-term debt is a more powerful predictor of retirement confidence than investment knowledge or formal retirement planning. (Whattt?) That’s right—whether someone feels confident about retirement depends less on their retirement account literacy and more on whether they’re carrying credit card balances and personal loans.
“Having little or no short-term debt was cited by 45% as a top positive factor affecting confidence,” Gladstone tells us. Meanwhile, inflation and healthcare costs keep workers up at night, regardless of how well their target date fund is performing.
“Short-term debt emerged as the number one driver of retirement confidence—beating investment knowledge and retirement planning.”
Financial Literacy: The Unsexy Solution
We asked Gladstone about innovation she sees —AI tools, crypto debates, private markets in TDFs. Her answer? The industry’s biggest challenge is still pretty basic: financial literacy.
“Personal finance is a taboo subject for a lot of people. They’re afraid of it. They don’t talk about it.” She lights up when discussing states mandating financial literacy in elementary schools. “This could be transformative.”
Her take on crypto? Blunt: “I don’t think it’s appropriate in a DC portfolio.” Private markets? More optimistic, especially when wrapped in professionally managed TDFs where participants don’t have to make complex decisions.
The Truth About Engagement
But the insight that cuts deepest? “It doesn’t matter what you’re offering or how you’re offering it,” Gladstone emphasizes. “If participants don’t know about it, don’t understand it, don’t know where to find it, it’s useless, unfortunately.”
Email still dominates as the preferred communication channel, but here’s a twist: in-person workshops rank second—ahead of webinars. Could it be that participants want personal connection, even as digital thrives? While AI can help simplify complex concepts, Gladstone is skeptical about replacing live advisors: “Call me old-fashioned, it’s no replacement for human interaction.”
What Else We Covered
Get this: we dive into sponsor-level personalization (both its power and surprising limits), measuring campaign success beyond click-through rates, spotty research on peer comparisons, and why automation’s “set it and forget it” benefit can sometimes backfire -- reducing active engagement.
The bottom line? Confidence without competence is concerning. As the retirement landscape evolves with new investment options and communication tools, the fundamentals remain unchanged: financial literacy, clear communication, and strategic engagement are what separate retirement readiness from retirement wishfulness.
READ THE FULL INTERVIEW
About Danielle Gladstone
As Vice President and Head of Participant Engagement at State Street Investment Management, Danielle Gladstone sits at a unique intersection of behavioral finance, communication strategy, and retirement policy. You gotta see the rest, here.
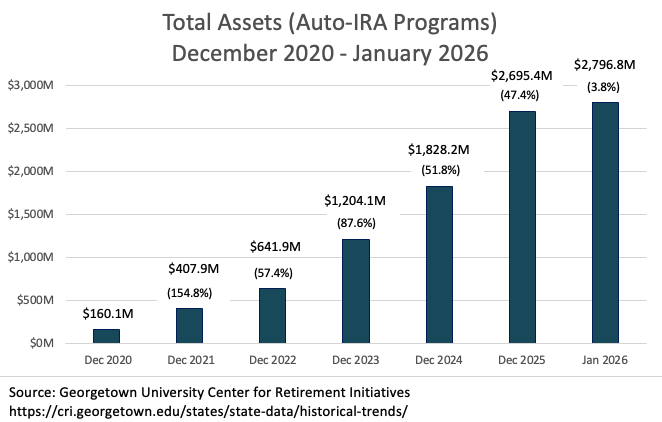
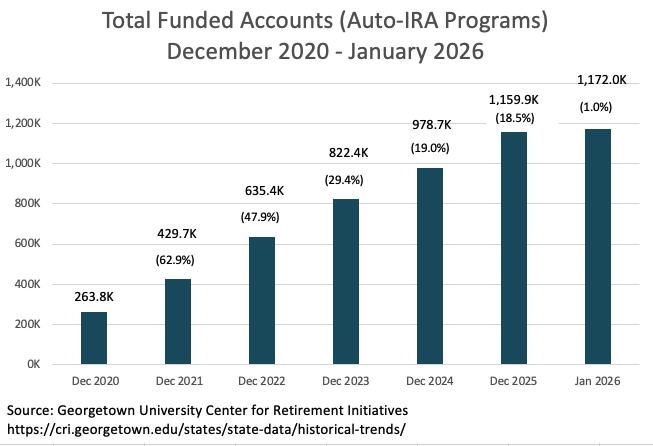
| | By the Numbers: State Auto IRAs Today | | The momentum continues. As of January 2026, state Auto IRA programs have crossed significant milestones, with assets approaching $3 billion and nearly 1.2 million workers now saving for retirement through these programs. | | |
And ...
-
Funded Accounts: Nearly 1.2 million savers now have accounts (❤️)
-
Average Balance: Climbing past $2,400
-
Five-Year Growth: From $160 million (2020) to $3 bils. Yes please.
We're seeing progression of the implementations that started less than 10 years ago. Early programs—OregonSaves, Illinois Secure Choice and CalSavers—continue to pave the way, demonstrating that automatic enrollment works and that workers without access to workplace retirement plans want to and will save when given a simple, accessible option.
The newest programs—Minnesota (launched January 2026), Nevada, New York, and Rhode Island—are beginning to add new savers each month. Hawaii could launch later this year; if they do, they’ll become the 18th state with an active Auto IRA program.
A special thank you to Angela Antonelli and the Georgetown Center for Retirement Initiatives for this data. Find more metrics and information on their site, here.
| | States in Action—Auto IRAs | | The past quarter has seen solid activity in the state Auto IRA space. New programs launching, existing programs expanding, and states exploring partnerships—we like the steady pace and the expansion of coverage. A quick “thank you” to our colleagues in retirement-security land. We pulled this roundup from a range of sources, including AARP, the Georgetown Center for Retirement Initiatives, Pew Charitable Trusts, news outlets like CNBC and PlanSponsor, and the websites of and conversations with our state program friends. | | |
New Programs Launch
Minnesota Launched in January 2026
Minnesota’s program opened this January, with worker enrollment beginning January 19. The state joins the growing Colorado Partnership for a Dignified Retirement, bringing its established administration and structured-and-configured platform to Minnesota’s workers.
Hawaii on Track for Mid-2026 Launch
Hawaii made a significant policy shift in 2025, switching from a saver opt-in model to an opt-out, automatic enrollment model. That brings the program closer to the structure of other Auto IRAs, represents a best practice, and makes it easier to launch – including potentially this year. Breaking news from Georgetown: In February 2026, the Hawaii Retirement Savings Board voted to enter the Multistate Alliance for Retirement Security, joining Connecticut and Rhode Island in this partnership arrangement.
Partnership Developments
State partnerships continue to grow and show value. As of January 2026, 8 of the 17 Auto IRA programs have entered partnership agreements through two distinct arrangements:
Colorado Partnership for a Dignified Retirement (PDR)
Member states as of January 1, 2026: Colorado, Maine, Delaware, Vermont, Nevada, and Minnesota. The partnership offers cost-effectiveness and faster time-to-market for smaller states while maintaining state-level customization.
Multistate Alliance for Retirement Security
Connecticut and Rhode Island formalized their partnership in September 2025, with RISavers opening to all eligible employers on October 21, 2025. As noted, Hawaii’s board voted to join this partnership in February 2026.
Program Expansions and Amendments
Several states are considering or enacting program expansions:
-
New Jersey and Virginia are both exploring lowering employer thresholds, which would expand coverage to more workers. New Jersey’s bill would lower the employer threshold from 25 to 10 employees. Virginia’s bill would lower their threshold from 25 to 5 and remove a 30-hour work requirement for employee eligibility.
-
Philadelphia could become the first city to enact and launch an Auto IRA program, with Mayor Cherelle Parker approving legislation in January 2026 that allows voters to decide on the Philly Saves program. Go Philly's!
-
Massachusetts raised the cap on its CORE MEP program. Now nonprofits with 100 or fewer employees are eligible to join. In the past, the limit was 20 or less. The CORE program is currently serving about 2700 savers through 260 employers.
Coverage Milestone
Back-of-the-envelope estimates suggest that currently approved and operational state programs, when fully rolled out, will cover approximately one-third of the total uncovered W-2 workforce in the United States. That’s remarkable progress in less than a decade since OregonSaves launched in 2017. We love it. Go, States, Go.
The gap that remains? 33 states still lack programs. This is exactly what motivates proposals like AARP’s Auto IRA Plus and Representative Neal’s Automatic IRA Act. For more, see this piece.
Research Note: The Employer Response
Fascinating new research from our friends at the Center for Retirement Research at Boston College confirms that state Auto IRA programs are actually spurring MORE employers to adopt their own 401(k) plans. In states with Auto IRA mandates, firms are offering their own retirement plans at rates 5.7 to 8.7 percentage points higher than same-sized firms in states without such programs.
Why would employers choose “the more expensive way to comply with the law”? That’s the puzzle researchers are still working to understand. But the outcome is unambiguous: state Auto IRAs are expanding retirement coverage both directly (through state program participation) and indirectly (by catalyzing employer plan adoption). More commentary here.
| | We Got You: Key Insights from State Street's GR3 Report | |
State Street Global Advisors’ 2025 Global Retirement Reality Report surveyed 4,371 workplace retirement plan savers across Australia, Canada, Ireland, the UK, and the US. The findings reveal nuanced views on retirement confidence, income planning, and preparedness—and point to where the industry needs to focus its efforts.
| |
The Confidence Gap
While retirement optimism is growing (about 1 in 5 respondents feel optimistic about being financially prepared for retirement), deeper analysis reveals a clear disconnect between sentiment and actual preparedness. In many cases, confidence isn’t anchored in robust planning or adequate savings, but rather in optimism bias or lack of awareness about future income needs and longevity risk.
Key confidence boosters:
- Having little/no short-term debt (45% cited this as a top positive factor)
- Financial security/ability to save for retirement (37%)
- Confidence that retirement plan is invested wisely (33%)
- Employment security (31%)
Top concerns negatively affecting confidence:
- Inflation/increased cost of living (45%)
- The economy (26%)
- Medical expenses (increasing with age—50% of those 65+ cited this)
- Mortgage debt/housing (higher for younger workers: 36% of 18-34 year-olds)
The Gender Gap Persists
Just 22% of women report feeling very or extremely optimistic about retirement, versus 33% of men. Women are also less likely to have a decumulation plan: 39% of women versus 23% of men replied “I don’t know” when asked about their plans for retirement savings.
The Income Planning Challenge
Nearly 1 in 3 respondents don’t have a plan for their retirement savings once retired. Over half of surveyed savers now associate retirement income with a steady, dependable income stream—an encouraging increase from 2023. However, about 1 in 5 still see it as simply a drawdown plan, suggesting continued confusion about how retirement savings convert into dependable income.
Concerns about retirement planning:
- Not knowing how much savings is needed (66%)
- Not having the ability to generate consistent income throughout retirement (62%)
- Outliving savings (58%)
- Not being capable of covering unexpected medical costs (65%)
The Power of In-Plan Income Solutions
Half of respondents would keep their assets in their retirement plan if that plan offered income solutions. This figure increased significantly from 2023 in the UK, Ireland, and Australia, signaling clear demand for lifetime income options delivered through workplace plans.
| Innovation Highlights: What's Trending in Retirement Security | |
The retirement industry is experiencing a wave of innovation. From in-plan retirement income solutions to enhanced participant engagement tools, 2026 is shaping up to be a year of execution after years of exploration.
1. In-Plan Retirement Income: From Pilot to Practice
The Institutional Retirement Income Council (IRIC) forecasts that 2026 will mark the transition from growing interest in retirement income innovation to broader adoption of in-plan solutions. Will it? After years of building the groundwork with hybrid target date funds, annuity marketplaces, systematic withdrawal programs, and managed accounts with built-in income features, IRIC notes that consultants and advisors are now implementing standardized fiduciary evaluation frameworks to help plan sponsors adopt and use.
2. Enhanced Participant Experience Through Digital Tools
2026 may also see improvements in how participants interact with and transact in-plan retirement income options. The evolution emphasizes clarity, simplicity, and digital engagement—helping participants understand how their plan balance converts to income, compare options, and make informed decisions in real-time.
AI-enabled tools are playing an increasingly important role in personalizing retirement income projections and spending estimates, while maintaining human oversight. The goal: meet participants where they are with intuitive, mobile-first tools that simplify complex decisions. (This forecast also comes from the IRIC analysis).
3. Financial Wellness Programs Focusing on Pre-Retirees
There’s growing recognition that financial wellness isn’t one-size-fits-all. Employers are increasingly offering comprehensive pre-retirement programs that include:
- Education on Social Security and Medicare elections
- Retirement paycheck modeling that visualizes income from multiple sources
- Tools to help participants manage debt and build emergency savings alongside retirement savings
According to a 2025 Mercer survey, 92% of employers plan to prioritize financial wellness, yet only 36% currently offer financial education. The gap between intent and execution represents a significant opportunity. IRIC also says this.
4. Emergency Savings Accounts (ESAs) Gain Momentum
Research from Commonwealth, AARP, and the Bipartisan Policy Center continues to show that emergency savings can complement—not compete with—retirement savings. Key findings:
- 30% of households making under $75,000 with access to workplace retirement plans reported that an emergency savings option paired with their retirement plan would make them MORE likely to contribute to retirement (Source: Commonwealth and SaverLife survey)
- Households with at least $1,000 in emergency savings were half as likely to withdraw funds from retirement accounts during the pandemic
- 58% of households making under $60,000 don’t have $400 saved for an emergency (Commonwealth analysis of Federal Reserve Report on the Economic Well-Being of U.S. Households, 2020)
Well-crafted emergency savings solutions can act as buffers against early withdrawals from retirement accounts, protecting long-term security while addressing short-term needs.
5. Auto-Enrollment Mandates Drive Adoption
SECURE 2.0’s automatic enrollment provision took effect January 1, 2025, requiring new 401(k) plans to auto-enroll workers at a contribution rate of 3-10% (with exemptions for small and very new businesses). The impact is already being felt: Vanguard’s 2025 HAS report showed that 61% of 401(k) plans now include auto-enrollment, up from 54% in 2020 and just 27% in 2010. That was fast! (20 years ago the rate was just 10%)
Plans with auto-enrollment show a 94% participation rate, compared to 64% for plans without this feature.
| | |
We’re only giving you three this month. Savor.
3 – Get out your LIBBY app. We’re currently reading Susan Orlean’s “The Library Book” – 2018 - captivating. Orlean weaves together the story of a devastating 1986 fire at the Los Angeles Public Library with a broader meditation on libraries, books, and community. We love her research and the way she tells a story. We loved The Orchid Thief, too.
2 – F1 Season is (almost upon us. We’re getting ready for the 2026 Formula 1 season by diving into both the official F1 YouTube channel and creator Kym Illman’s behind-the-scenes content. An accredited F1 photographer, Illman brings unusual access and insider perspective to the sport. He’s how we found out Liam Lawson almost hit two marshals at the Mexico City race when we were in the stands.
1 – Pitchers and Catchers Report. Yes friends, it’s that time of year. Our beloved Red Sox – and your teams too – are tuning up for the season ahead. Will we have a deep enough bullpen? Will they hang on to our best players? Will we be crying if this happens? We will. We certainly will. The Yankees and Giants kick off the Opening Day days early, on March 26. Get your mitts out.
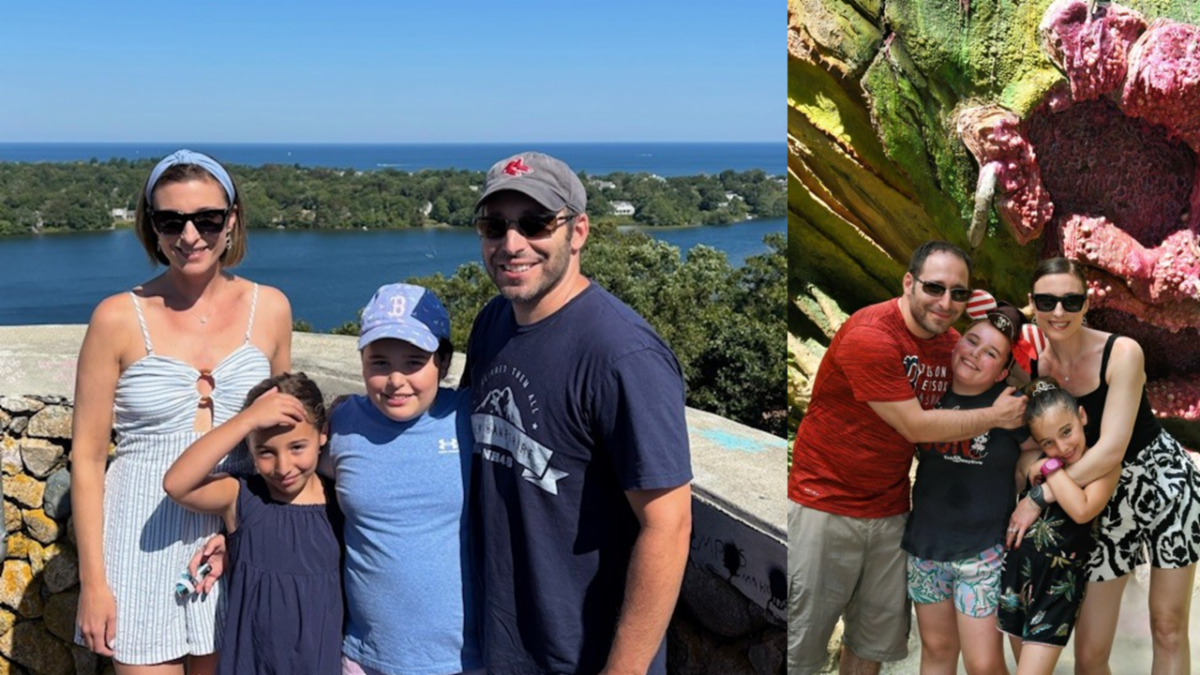
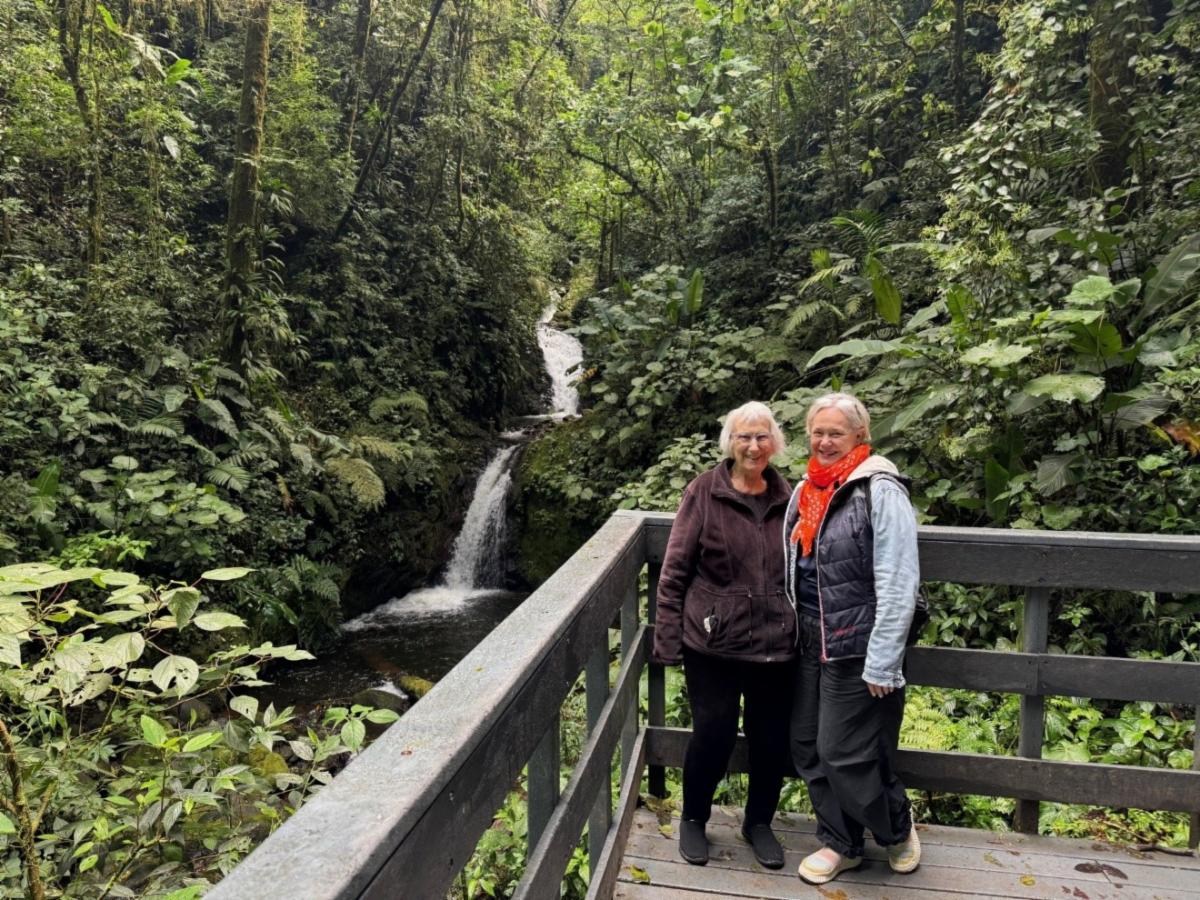
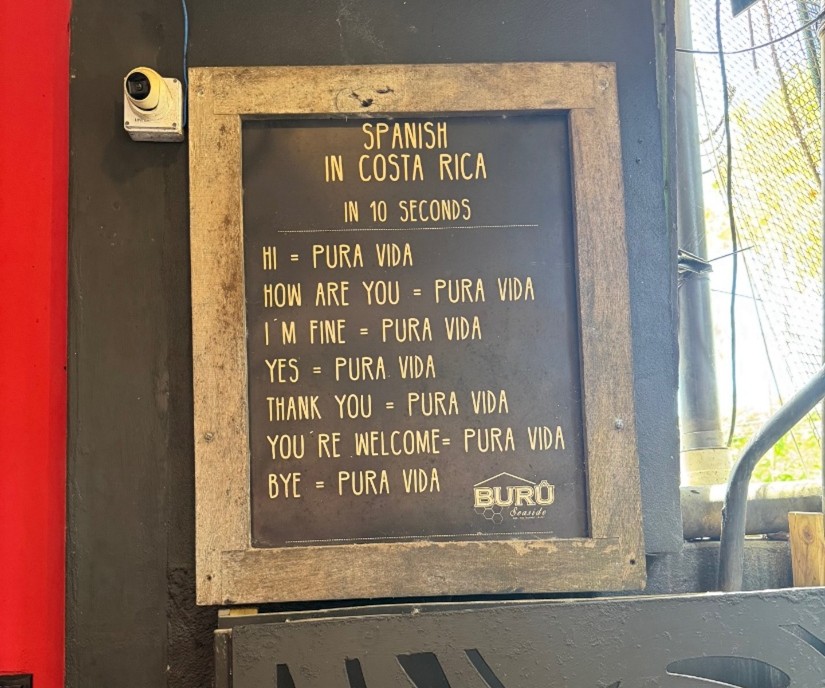
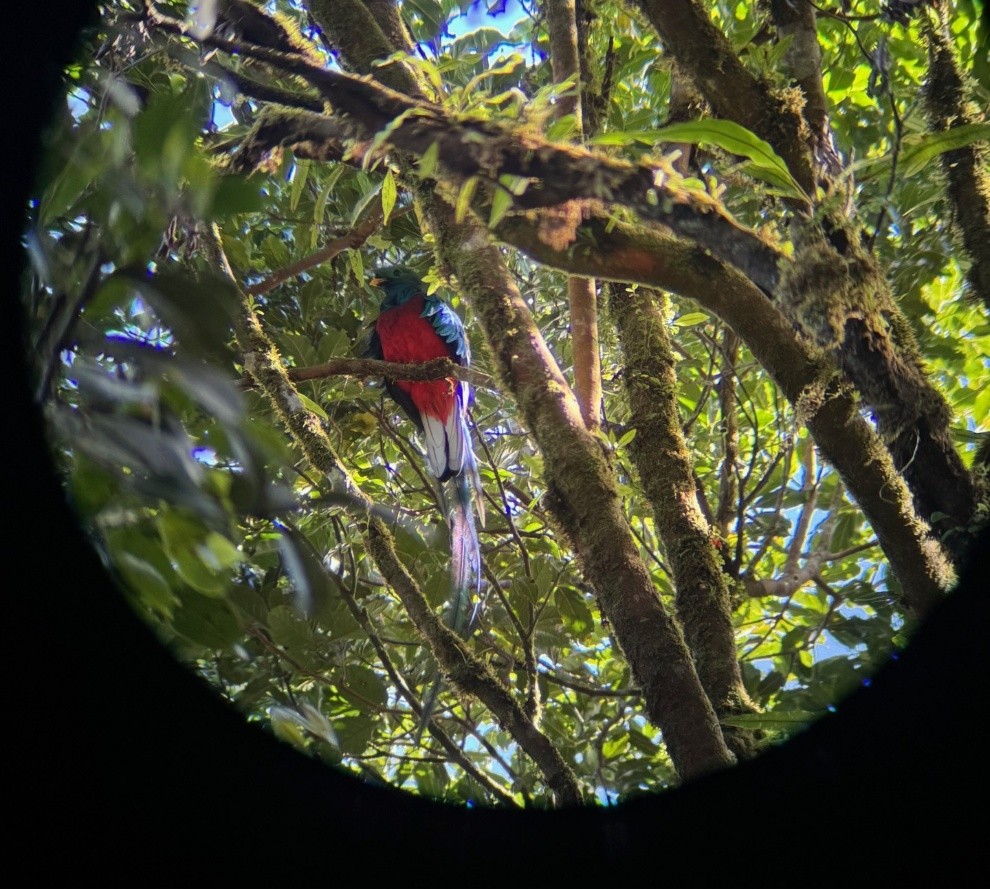
| | Please Make it Happen ... Pix of the Week! | | Danielle recharging the right way—Cape Cod, Disney World, and time with husband, Brett (a professional jazz pianist and music teacher) and Ave (10) and Leila (7). | | Ifffff you find yourself in Costa Rica, we hope you’ll be accompanied by your mother. | | And that you will experience the pura vida – it’s absolutely for real. | | And may you also spot the legendary resplendent quetzal high in the canopy of a cloud forest in Monteverde. We caught our mother saying, “this makes it all worth it.” #favoritechild – for a day. | | |
That’s it for this edition. ❤ Hug your people and change the world.
| | |
Massena Associates provides process, policy, and implementation consulting on retirement savings programs and products.
Our clientele includes public entities, policy organizations, and private sector providers. Our specialty – efficient, targeted results. We are an active speaker on retirement security topics, including state-facilitated programs, MEPs and more.
If you’d like to explore working together, we welcome the conversation. Connect with us here, and at 339-236-0684.
| | |
Looking for a great retirement savings innovation resource? The Center for Retirement Research at Boston College develops and hosts terrific content and proprietary research related to states, financial security, social security, and more.
The Defined Contribution Institutional Investment Association (DCIIA) is dedicated to enhancing the retirement security of America’s workers. To do this, DCIIA fosters a dialogue among the leaders of the defined contribution community who are passionate about improving defined contribution outcomes. DCIIA's site provides a range of public and member-specific resources.
The Georgetown Center for Retirement Initiatives, Led by Angela Antonelli, GCRI provides excellent information on state-based and other retirement security innovation and policy.
Pew’s Retirement Savings Project studies the challenges and opportunities for increasing retirement savings and is another great resource - check out the work of John Scott and his terrific team.
If you want a great source of broad-based, consumer-focused retirement news, Jeffrey H. Snyder’s The Morning Pulse is your ticket. You can subscribe here.
| | | | |