RETIREMENT SECURITY MATTERS

A forum for retirement savings innovation, together.

Vol 97 | December 18, 2025

Greetings! Greetings! welcome to Retirement Security Matters—where we talk about retirement readiness innovation across public and private spaces. 

Hello Friends! Happy Holidays to you - may you deeply enjoy your Hannukah, Christmas, Atheist's Day, and New Year. In a few short days we’ll find ourselves drop-shipped into 2026. But for now, let’s chilllllll. Take a breath and a moment for ourselves. We got good stuff for you today—three juicy big ones, and five little ones, and some fun pix to round things out.


Up ☃️ next:


  • We are in Vermont with Becky Wasserman and Big Vision
  • State Auto IRAs—By the Numbers, and a Forecast
  • A 530A by any other name
  • Shortcut to Hot Sauce, Cool Stuff … and
  • Pix of the Week!
    

View as Webpage Comments or content suggestions? We welcome both. Have something about your program or work you’d like to share? We are all ears.

Small State, Big Vision: Inside Vermont Saves with Becky Wasserman

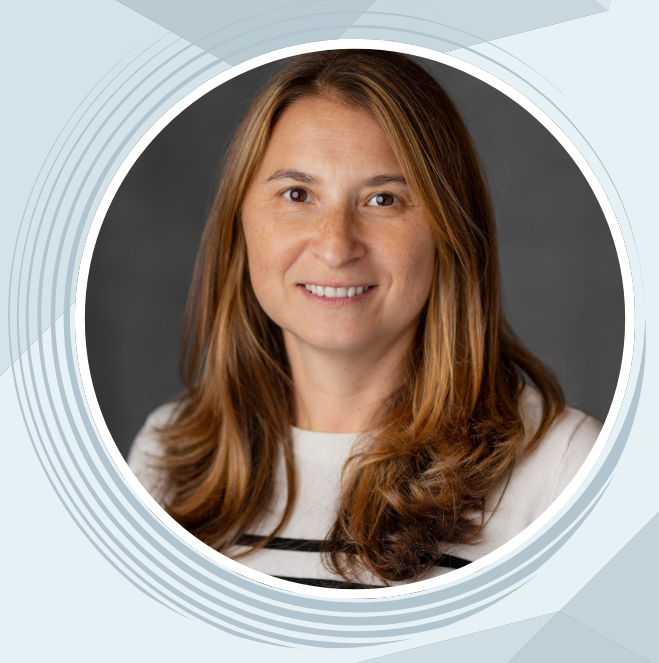
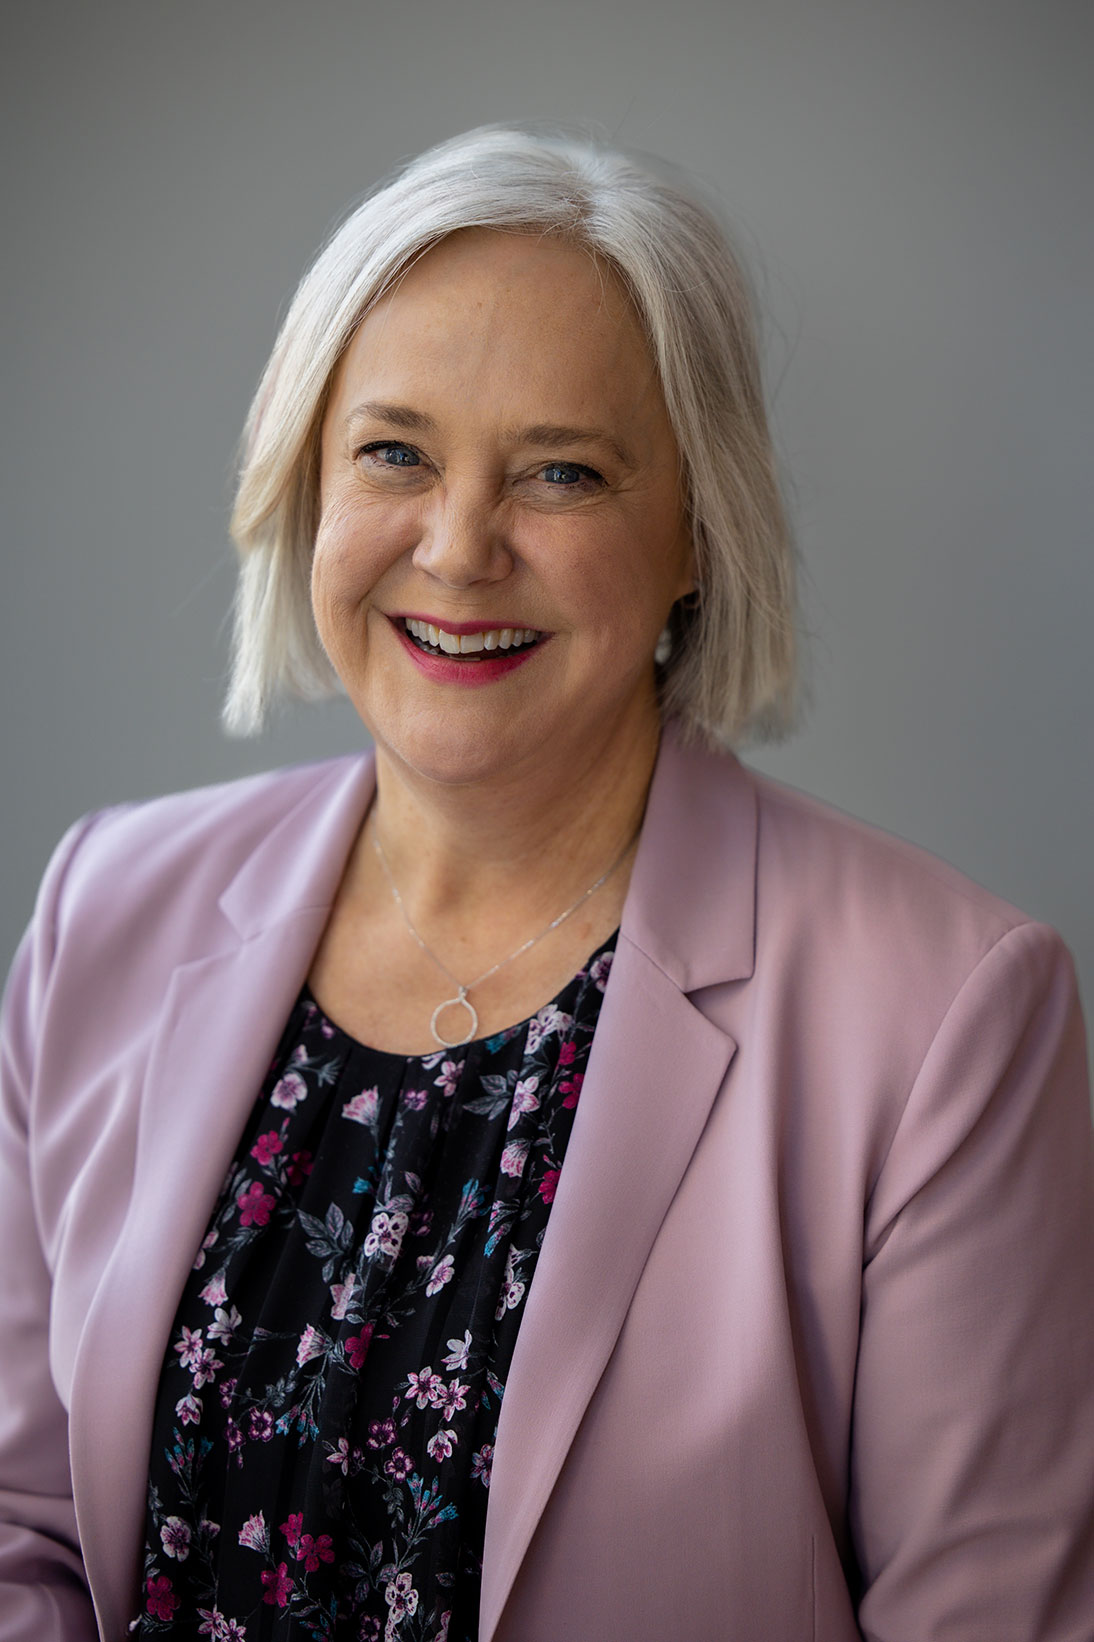
Rebecca (Becky) Wasserman, Executive Director, Vermont Saves

Vermont may be small, but its approach to retirement security is proving that size doesn't limit ambition. With just 650,000 residents and approximately 88,000 workers lacking access to workplace retirement savings, Vermont faced a unique challenge: how to launch a sustainable auto IRA program without the scale enjoyed by larger states.


The answer? Strategic partnership, creative outreach, and a commitment to accessibility that reflects Vermont's community-oriented values.


We talk this week with Rebecca (Becky) Wasserman, inaugural Executive Director of Vermont Saves. Here she shares candid insights from the program's first year—from navigating scam concerns and communication challenges to engaging tax practitioners as trusted messengers for small businesses. She reveals how Vermont's partnership with Colorado through the Partnership for a Dignified Retirement has provided crucial efficiency and resources, and how the state's unique governance structure gives it flexibility to respond quickly to employer feedback.


"I've had people say, 'I never thought it was possible for me to save for retirement,'" Wasserman shares. "Seeing that direct impact on a person's life—that's what makes this work so meaningful."


What sets Vermont apart?


  • No statutory board—the State Treasurer serves as sole fiduciary
  • Employee threshold adjustable through rulemaking (not legislation)
  • Direct accessibility: "There's no phone tree before you can reach me"
  • Innovative language access through the Vermont Language Justice Project
  • Integration strategy across 529, ABLE, and retirement savings programs


Wasserman's vision extends beyond retirement alone. As director of the Economic Empowerment Division in Treasurer Mike Pieciak's office, she's working to connect Vermont Saves with other initiatives—from baby bonds to emergency savings—creating a comprehensive approach to financial security from birth through retirement.


Read the full interview to dig in


  1. Vermont's Distinctive Approach - Learn about the Partnership for Dignified Retirement, Vermont's unique governance structure, and plans to lower the employee threshold from five to two
  2. Implementation Lessons - Discover early surprises, communication challenges, and strategies for building trust in a world of digital scams
  3. Engaging Employers - Find out why Vermont is targeting tax practitioners and CPAs as key messengers, and how personal connections make government accessible
  4. Looking Ahead - Explore plans for program integration, protecting individuals with disabilities, and creating a dashboard view across savings programs


Don't Miss Our Conversation!

Key Takeaways for Other States:


  • Consider partnerships to achieve economies of scale
  • Engage trusted professional intermediaries (CPAs, tax practitioners) for small business outreach
  • Build accessibility into program design—from language access to direct staff contact
  • Think holistically about economic security across multiple programs
  • Use rulemaking flexibility where possible to respond quickly to feedback

Vermont Saves launched in December 2024 and is housed in the Office of the State Treasurer. The program requires employers with five or more employees to register unless they already offer a qualified retirement plan.


Learn more: vtsaves.vermont.gov | vermonttreasurer.gov

By the Numbers: State Auto IRAs Today

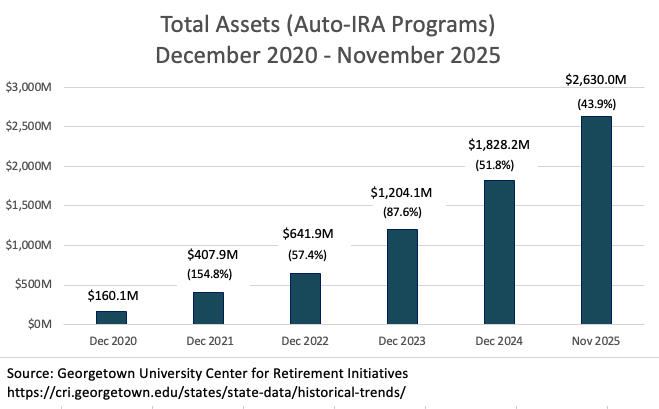
We Read it for You – Program assets finished November at $2.63 billion. For the year, this represents a growth rate of 44%. Assets are up 4x their level just three years ago. Helped by market returns, part of the programs’ purpose, asset growth is significantly greater than account growth (see below). About 60% of these assets belong to California savers. Oregon’s program holds 17%; the Illinois program holds 12%; Colorado’s program holds 7%. The balance of reported assets are held by savers in Connecticut, Maryland, Maine, Virginia, New Jersey, Delaware, Vermont and Nevada. Just wait until our friends in New York come on line. ❤️

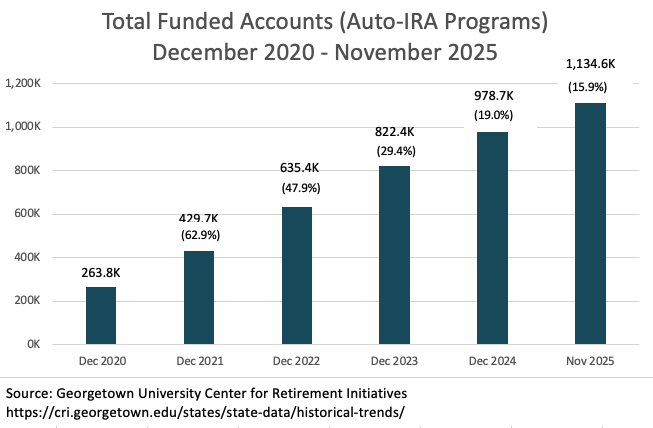
Funded Accounts – now total 1,134,600. This is an increase of about 16% in 2025, and an increase of 1.8x over their level three years ago. About half of these account belong to Californians. 14% belong to savers in Illinois; 13% to savers in Oregon, and 8% to savers in Colorado. The balance is split across the remaining live, reporting state programs.


Year-end Forecast: Our A.I. pal Claude is predicting $2.7-$2.75B in assets, and between 1.145 and 1.155 million funded accounts. What do you think … can you beat the bot with a better forecast? Send us your prediction and if you win, you’ll get an amazing RSM prize.


A special thank you to Angela Antonelli and the Georgetown Center for Retirement Initiatives for this data. You’ll find more detailed metrics and information on their site, here.

Will Trump Accounts Save Retirement?

These new 530A things are getting all the attention this month! Here’s a quick set of thoughts, followed by links to a wide range of perspectives so that you can form your own opinion.

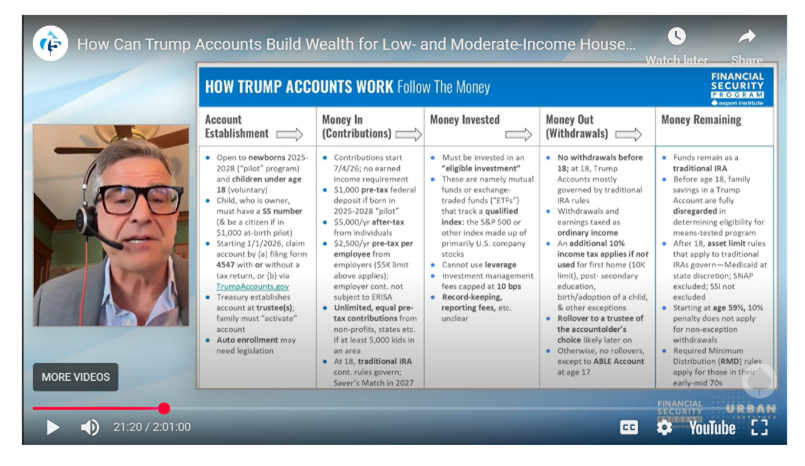
DOOOO check out this terrific explainer video from the Aspen Institute and the Urban Institute featuring Ray Boshara, among others. ⬆️

What's the Potential. This is our rough cut—other sources will give you additional thoughts and context. About 14 million kids are likely to be eligible for pilot contributions of $1,000. Assuming no further contributions and market investments, these accounts could be worth about $5,800 at age 18. We’re guessing that in 2043 when this starts to look real, lots of families who didn’t do it sooner are going to try to backward-claim their 530A accounts. If everyone claims and establishes accounts, aggregate assets across these pilot children could be north of $81 billion.


That won’t happen. The claiming number will be lower. But the system will also be aided by supplemental contributions and the establishment of voluntary accounts.


For 25 million kids born between 2016 and 2024 who are eligible to establish an account and who live in LMI zip codes, the Michael & Susan Dell Foundation has pledged a $250 contribution into established accounts. For this gift, LMI zip codes are defined as those with family incomes averaging $150k or less. This pledge will certainly be followed by more from titans of industry and others—likely including unique definitions of eligible children. A number of states, including Texas, are considering programs that line up with Trump accounts and provide supplemental funding.


Including pilot program children, some 36-40 million children in the US will be under 18 and eligible for voluntary account contributions over the next decade. As you can imagine, potential account balances at age 18 vary widely—from the $5,800 we reference above, to over $700,000 with maximum contributions and high market returns. Experts estimate narrower ranges of $10,000 to $100,000 for the average kid.


Will it make a difference. Yes, it will. You will find good arguments for voluntary savings to go into other account types for kids. For education savers, 529 accounts offer higher annual contribution caps and more flexible access. For emergency fund savers, straight savings accounts are going to provide the day to day access they need. However, we love birth- and kid-based savings that goes directly into an IRA without child income requirements—and there’s not other way to do this today.


As semi-realists, if we had to sum up human behavior and likely outcomes, we’ll go here:


1 – starting in 2043 we’ll probably see a rash of account liquidations—even with the 10% extra tax due—from folks who suddenly realize they have access to an account they don’t have a very big emotional investment in.


2 – we’ll also see a lot of inertia—folks who’ve forgotten these assets, and/or who have to take active steps to use or manage their accounts. These assets will continue to grow—somewhere. They’ll be remembered and found again at a future, useful date—it could be for trade school or college, a home, a new child. And for many, it could absolutely be to fund a more secure retirement.


3 – and, like a version of #2 on steroids, we will see families and kids take active charge of their accounts—contributing when they can—seeking out employer contributions and matches—and making very thoughtful decisions about the use of funds saved. How many? This is a giant experiment - we can't wait to see.


4 – with estimates ranging from $150 billion to $1.2 trillion held in Trump Accounts by 2046—it’s hard to pin down retirement and economic impact in advance. But we do think the net benefit, including to retirement assets for the next generation, is going to be significant.


Jump here for more info—what Trump Accounts are, how they work, and what folks are saying.


The facts (credit for this summary to our friends at the Aspen Institute):


1 - Trump Accounts allow the federal government, organizations, and families to make contributions into IRA accounts for child beneficiaries


2 – As a third form of IRA (Traditional, Roth, Trump), these accounts have special rules covering:


A – taxation: the account becomes a traditional IRA in the year a child achieves age 18, and withdrawals are taxed accordingly. Contributions by employers are tax-deductible; contributions by individuals are not.


B – withdrawals: not allowed before age 18. Taxed at a higher rate if not used for qualified expenses such as the purchase of a first home, post-secondary education, birth/adoption of child, and more.


C – contribution limits differ from traditional and IRA limits at present. Investments are restricted to market investments that track a qualified index like the S&P 500. Initially, accounts will be held by custodian/recordkeeper(s) selected by the Treasury. Account beneficiaries may transfer accounts to the provider of their choice in the year they turn 18.


3 – Accounts are expected to go live in 2026 for two sets of beneficiaries:


A – Pilot program kids – those born in the years 2025-2028—who will receive a $1,000 federal contribution. And who are eligible (registered SSN). And whose parents and guardians file IRS Form 4547 to claim the accounts.


B – All other kids under age 18—for whom voluntary accounts can be established beginning July 4, 2026.


Retirement security matters! / Lisa

Hot Sauce! Cool Stuff


We’re going short form today, folks.
It’s the holidays! We got shopping to do. But before we both go, here are some quick bites to spice up your day:


5️⃣ - we talked with our friends Aaron Szapiro in 2020 and 2022, and Angela Montez in 2022 about CITs in 403(b)s -- and it just might be happening. Could .. it .. be?


4️⃣ - we haven’t talked about Social Security yet—let’s do! We like PlanSponsor.com’s recap of this month’s Senate HELP Committee hearing on the future of retirement savings. Would lifting the cap on payroll taxes solve our solvency problem? We think it could go a long way. Would Americans stand for it? Based on research we’ve seen, they support it and far prefer it to a reduction in future benefits. Maybe it’s not an intractable problem after all—what do you think?


3️⃣ - should we have read this before going to Costa Rica with our mother? Maybe .. not .. but The Adventurer’s Son by Roman Dial makes for a pretty good story. We will probably not go solo hiking in the Corcovado on the Osa peninsula. I promise, Mom.


2️⃣ - in our ears—Yo-Yo & Friends—six conversations with designers, physicists, chefs and musicians. Jony Ive might be our favorite. It’s an Audible Original, so not available everywhere … but worth it. Cellist Yo-Yo Ma is, on the side, a great philosopher.


1️⃣- on the Tikky Tokky—did you know this about China? We did not! Scales have fallen from our eyes. Derek Pen—@derekpenguin—answers the question Why is every product in China tied to one specific city. A question we would not know to ask, and an answer that reveals a lot.


🎄 you're welcome. 🎄

And Finally, ... we bring you Pix of the Week!

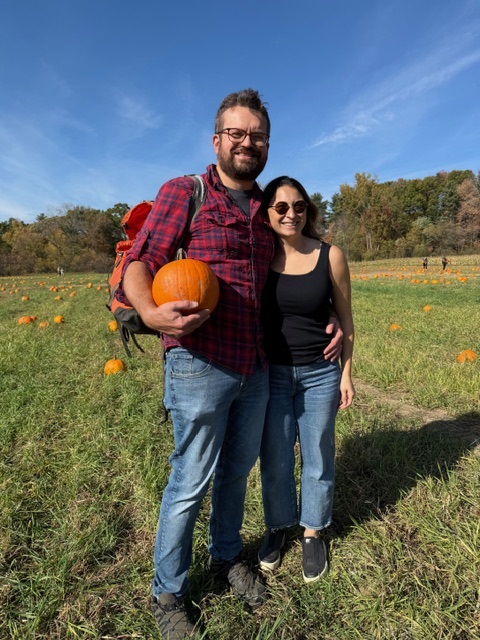
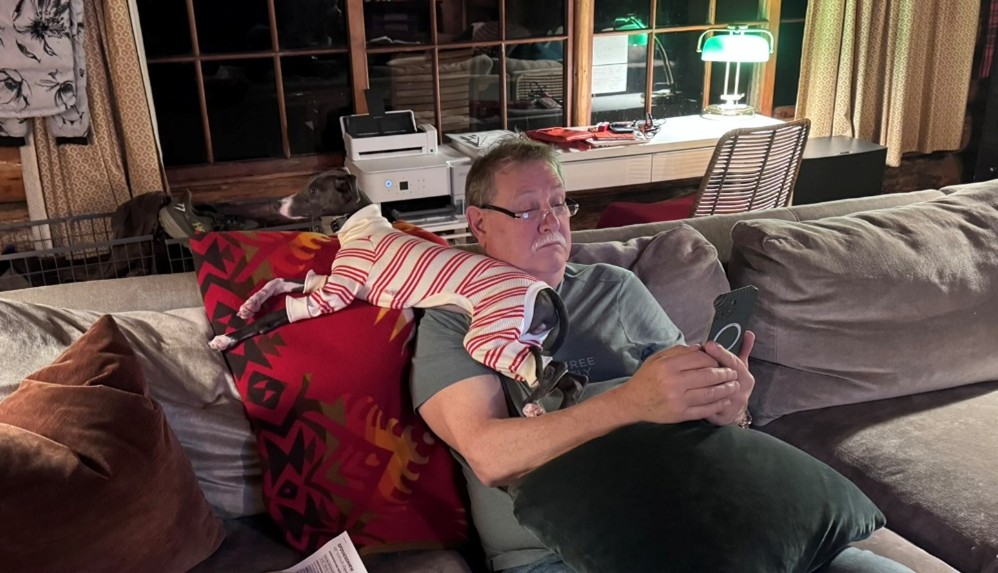
Becky and her husband, Ben Traverse … just two Vermonters living their best pumpkin-patch life. Proof that Vermont grows great pumpkins—and even better people. ❤️❤️❤️ Thank you for sharing, Becky - that's a handsome guy you got!

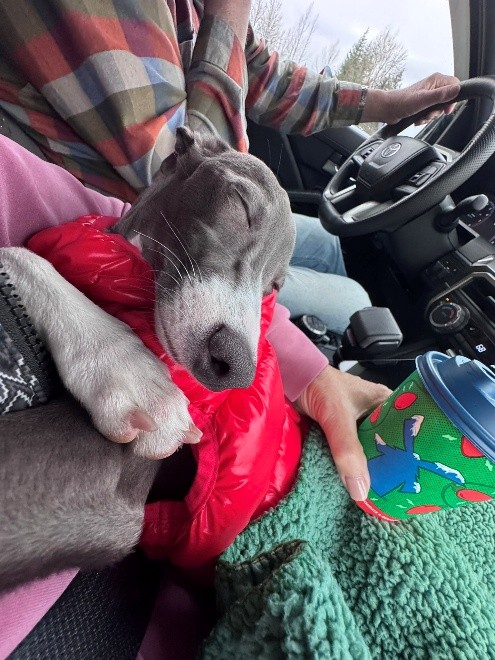
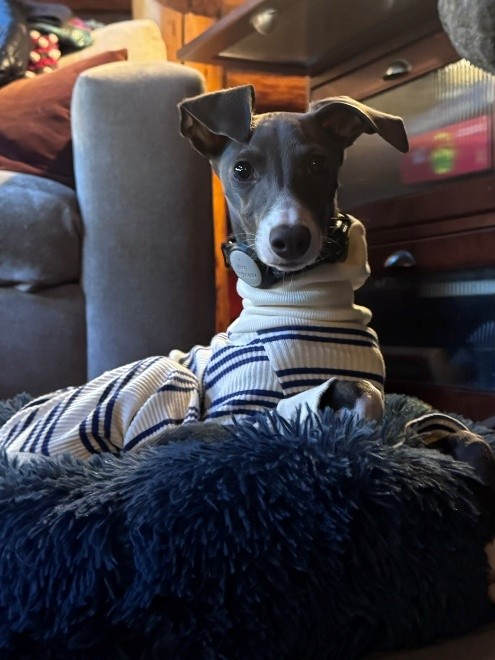
… and if instead of pumpkining in Vermont, you find yourself hanging out with the cutest dog in Oregon ... you may dress him up in PJs and a puffer to keep him warm. Which he will tolerate patiently. Harry is five months old this week.

That’s it for this edition. ❤ Hug your people and change the world.


Massena Associates provides process, policy, and implementation consulting on retirement savings programs and products.


Our clientele includes public entities, policy organizations, and private sector providers. Our specialty – efficient, targeted results. We are an active speaker on retirement security topics, including state-facilitated programs, MEPs and more.


If you’d like to explore working together, we welcome the conversation. Connect with us here, and at 339-236-0684.

RESOURCES you can use:

Looking for a great retirement savings innovation resource? The Center for Retirement Research at Boston College develops and hosts terrific content and proprietary research related to states, financial security, social security, and more.


The Defined Contribution Institutional Investment Association (DCIIA) is dedicated to enhancing the retirement security of America’s workers. To do this, DCIIA fosters a dialogue among the leaders of the defined contribution community who are passionate about improving defined contribution outcomes. DCIIA's site provides a range of public and member-specific resources.


The Georgetown Center for Retirement Initiatives, Led by Angela Antonelli, GCRI provides excellent information on state-based and other retirement security innovation and policy.


Pew’s Retirement Savings Project studies the challenges and opportunities for increasing retirement savings and is another great resource - check out the work of John Scott and his terrific team.


If you want a great source of broad-based, consumer-focused retirement news, Jeffrey H. Snyder’s The Morning Pulse is your ticket. You can subscribe here.

massenaassociates.com

Linkedin  X