RETIREMENT SECURITY MATTERS

A forum for retirement savings innovation, together.

Vol 98 | January 22, 2026

Greetings! Greetings! welcome to Retirement Security Matters—where we talk about retirement readiness innovation across public and private spaces. 

We’re starting a new series here at RSM—the Ocean 🌊 Series. Think about what we can get done together, in a great blue ocean of retirement security possibilities. We can’t do it without you! We’ve got the whole year ahead of us—let’s get after it.


We start with a big idea, and wrap up with a bang. Got you!


  •  AARP’s David John on Auto IRA Plus (you mean it gets better?!)
  • State Auto IRAs – by the Numbers – ¿Que Pasa?
  • Two Good Retirement Security Proposals – side x side
  • Hot Sauce! Such cool stuff you will not believe it, and
  • Pix of the Week! 

View as Webpage Comments or content suggestions? We welcome both. Have something about your program or work you’d like to share? We are all ears.

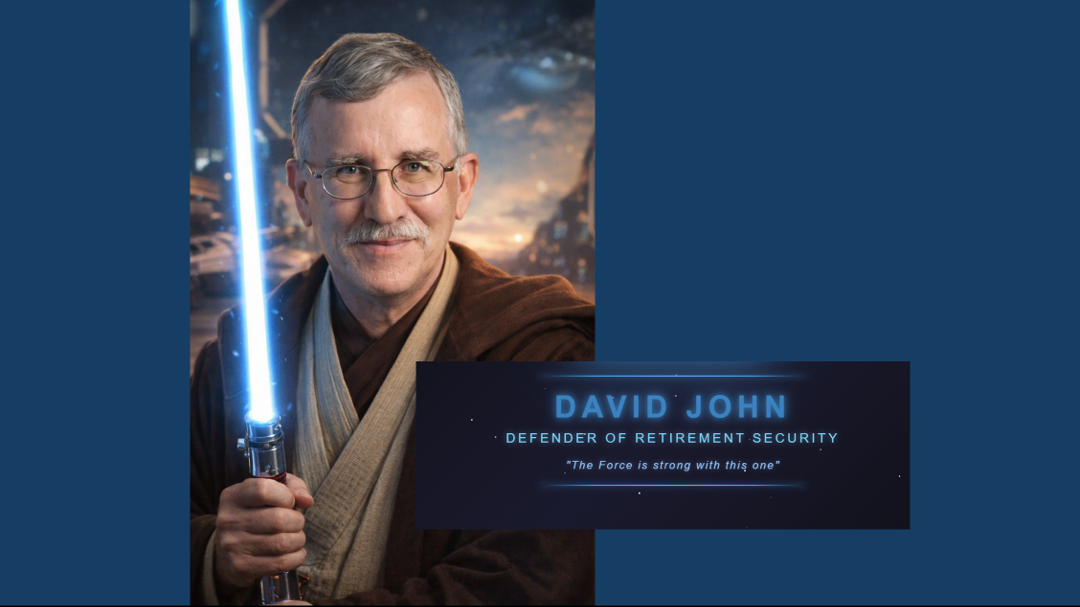
Cue Star Wars Theme: David John on Auto IRA PlusThe Next Generation

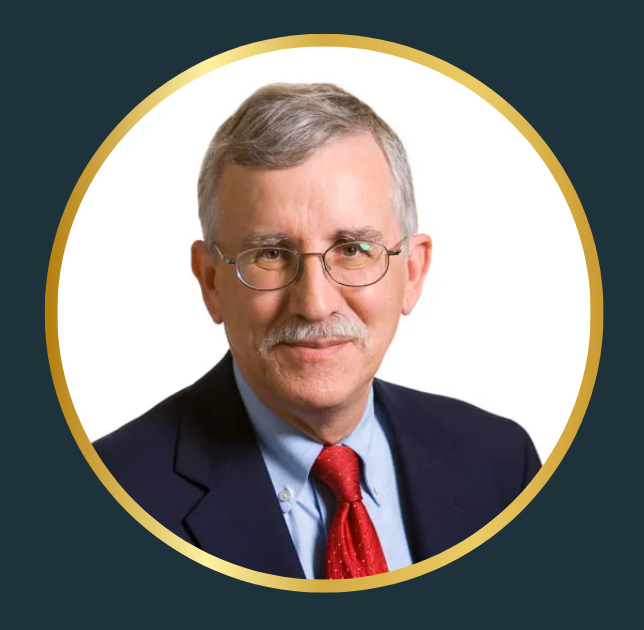
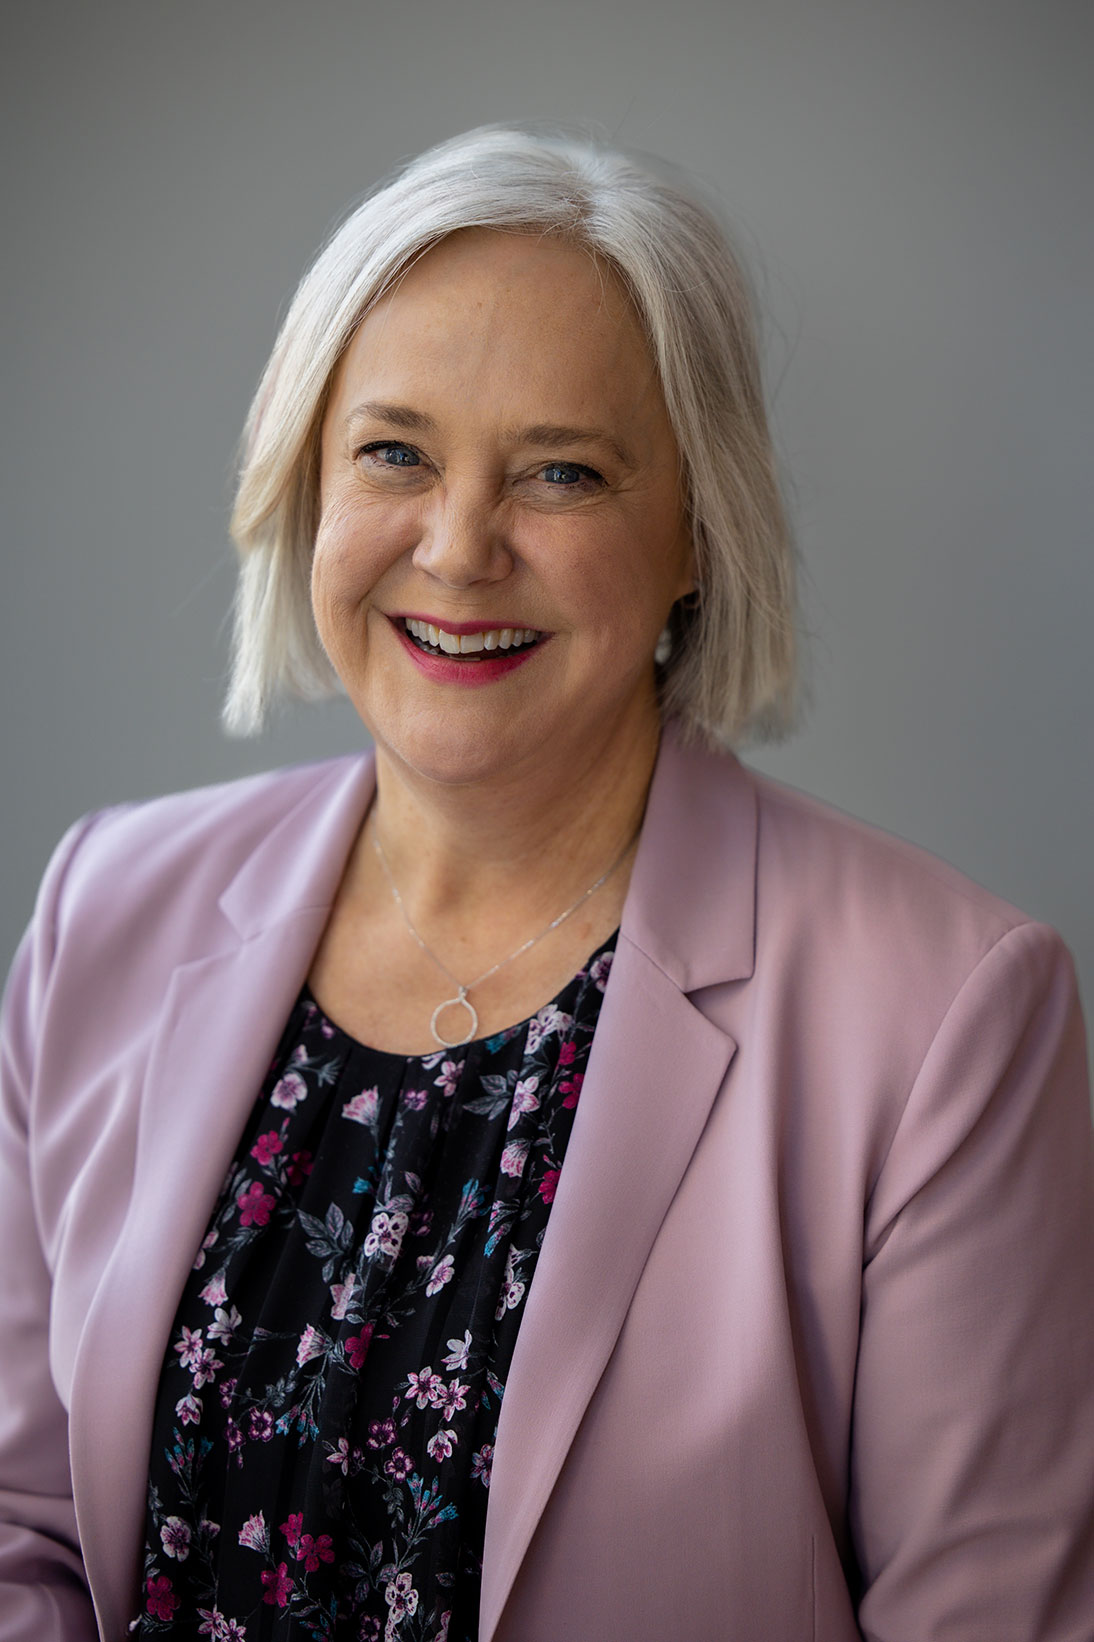
David John, Senior Strategic Policy Advisor at AARP's Public Policy Institute

Twenty years after David John and Mark Iwry introduced the Auto IRA concept, the bipartisan idea has become reality in 17 states, with 14 programs live and managing $2.7 billion for over 1.1 million savers. The success is undeniable. But 33 states still lack programs, leaving millions of workers without access to workplace retirement savings.


Now, as Senior Strategic Policy Advisor at AARP's Public Policy Institute, David is introducing Auto IRA Plus—a framework that would establish federal standards for retirement savings access through state programs while maintaining flexibility, creating a pathway to universal retirement coverage without disrupting what works.


In this candid conversation, David discusses the legislative path forward, why his approach beats alternative federal proposals (of course!), the critical intersection of Auto IRA and the Saver's Match, and why financial wellness programs need to evolve to mobile-first, text-and-video communications that meet workers where they are.


In This Interview:


➡️ Twenty Years In: How Auto IRA went from a joint Brookings Institution/Heritage Foundation concept to $2.7B reality

➡️ What is Auto IRA Plus? Federal standards + state flexibility = universal coverage

➡️ Building on What Works: Why sweeping the existing system aside would be expensive and counterproductive

➡️ The Legislative Path: What needs to happen at state and federal levels

➡️ Comparing Alternatives: How Auto IRA Plus stacks up against the Neal approach and federal programs

➡️ Federal Standards & State Flexibility: Setting minimums while letting states exceed them

➡️ Options for Non-Participating States: Partnership models and compliance mechanisms

➡️ The Saver's Match Connection: Why 80% of Auto IRA participants need this to work

➡️ Financial Wellness Evolution: From email to text, from laptops to phones, from planning to debt management

➡️ 2026 Priorities: What David wants to see accomplished this year


By the Numbers


20 years from concept (Feb 14, 2006) to today

17 states have authorized Auto IRA programs

14 programs are currently live

1.1 million accounts opened by workers who previously lacked access

$2.7 billion in retirement savings accumulated

33 states still without programs (the coverage gap Auto IRA Plus addresses)

~80% of Auto IRA participants are estimated to be eligible for the Saver's Match


Two Insights From David


On the timeline for policy change:


"An idea in Washington is like a fine wine. It has to age for a significant period of time before people will start to really take it seriously."


On building vs. starting over:


"It's neither desirable nor practical to sweep everything that exists today off to the side and start over again. What this does is fill in the gap and move towards a unified system that builds on what we have."


READ THE FULL INTERVIEW


About David John

David John is Senior Strategic Policy Advisor at AARP's Public Policy Institute. He co-created the Auto IRA concept with Mark Iwry in 2006 and has spent decades working on retirement security, savings policy, and financial wellness across both the Heritage Foundation, the Brookings Institution, and AARP.


About Retirement Security Matters

Retirement Security Matters is published by Massena Associates. For more information, visit massenaassociates.com

By the Numbers: State Auto IRAs Today

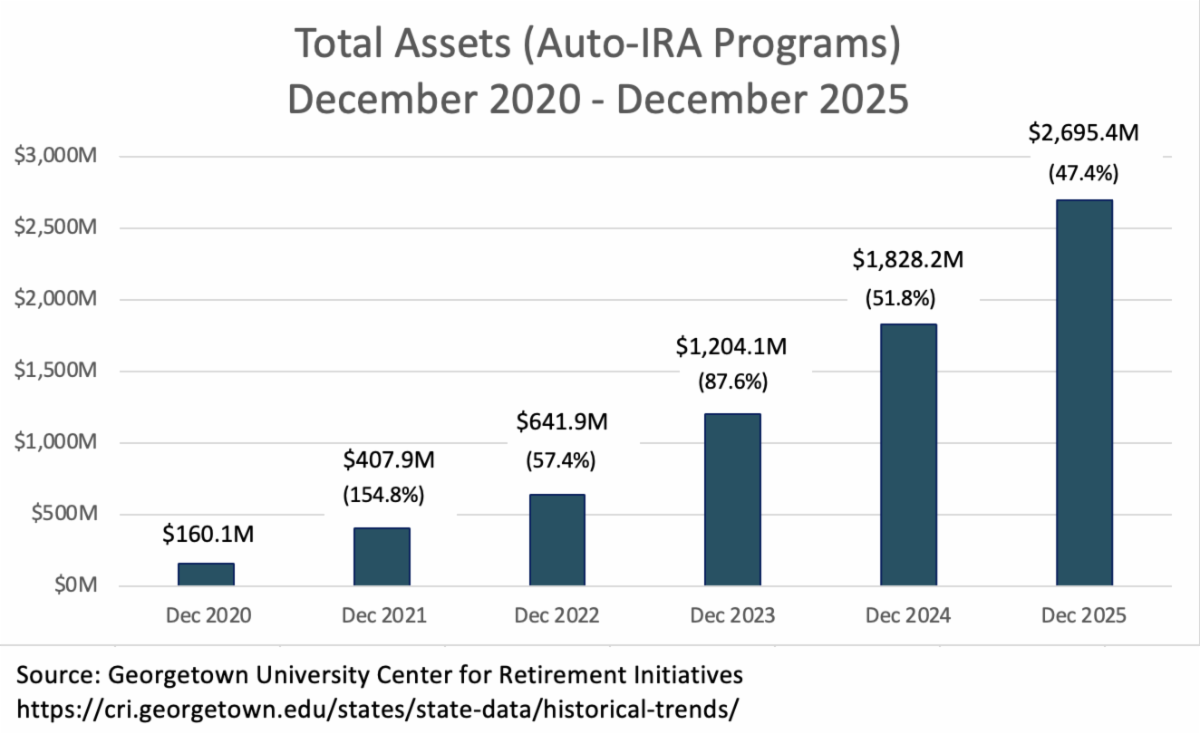
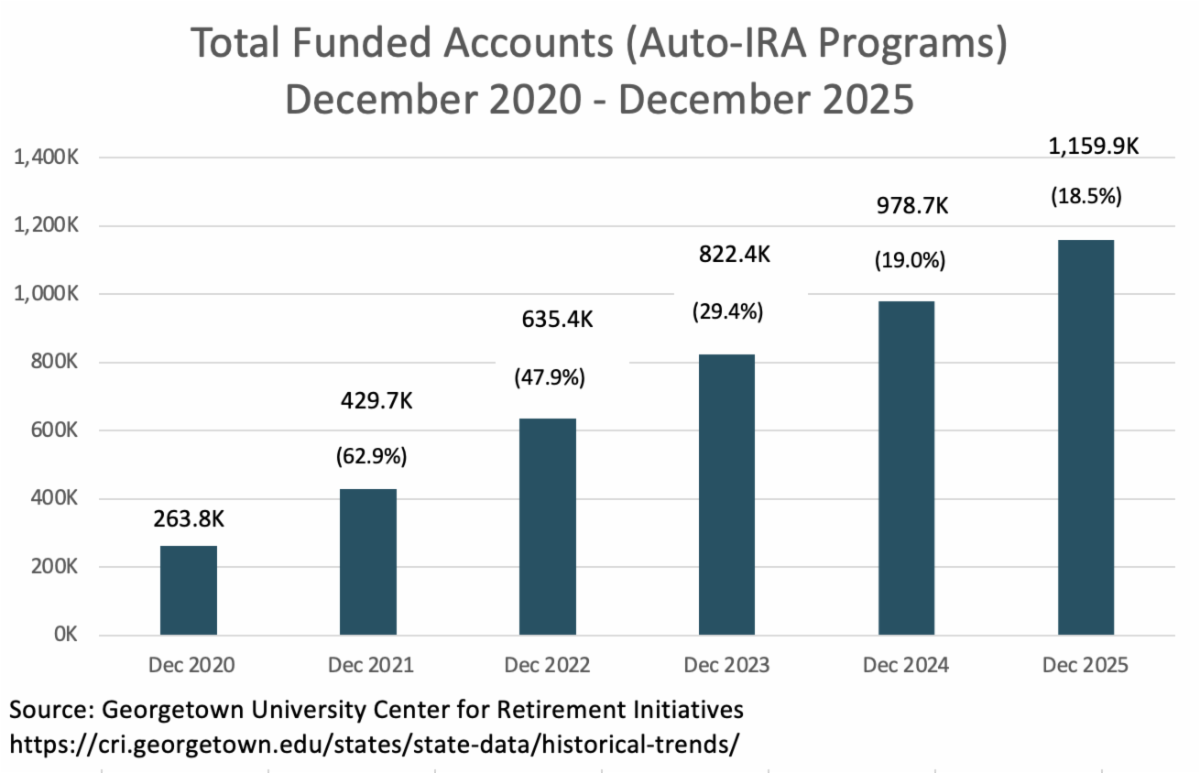
In five years, Auto IRA assets have grown from $160 million to $2.7 billion. Over the same period, funded accounts have grown to 1.16 million, from a 2020 year end level of about 264,000. The average balance across all accounts is now greater than $2,300. Looking back over this set of hills, this is what we wanted to see: early success at levels that make a difference for those participating.

Funded accounts grew 18% in 2025 -- and at an average rate of about 180,000 net new accounts a year over the last five years. As the base rises, we'll expect to see growth rates moderate. At the same time, the absolute number of net new accounts is likely to continue to rise as large programs like California and New York State complete their rollouts to the states' workforces.


A very seat of the pants estimate tells us that the currently approved programs, when fully rolled out, will cover about a third of the total uncovered W-2 workforce in the US. Check our math on that, please.


A special thank you to Angela Antonelli and the Georgetown Center for Retirement Initiatives for this data. You’ll find more detailed metrics and information on their site, here.

Two Good ProposalsLet's Compare

979

This very headline is going to drive at least one of our readers bananas 🍌. But we’re a fan of the good, not the perfect. Two current proposals on the table are AARP’s one as articulated by David John, above, and the one (re)introduced by Representative Neal in December 2025 that would require employers with 10+ employees who don't sponsor retirement plans to automatically enroll employees in IRAs at 3-5% contribution rates.


We’re curious to see how they stack up. Let’s get out the spreadsheet.


Comparison: Rep. Neal's Automatic IRA Act vs. AARP's Auto IRA Plus

Feature

Rep. Neal's Automatic IRA Act (2025)

AARP's Auto IRA Plus (2025)

Scope

Federal mandate requiring employers with 10+ employees nationwide to offer retirement access

Network of 50 state-run Auto IRA programs with federal standards but state customization

Implementation

National program administered federally, effective for plan years beginning after 2027

State-by-state implementation; states can run their own or adopt another state's program

Employer Coverage

Mandatory for employers with 10+ employees who don't sponsor a retirement plan

Mandatory at state level for employers without plans (state determines size threshold)

Default Contribution Rate

6% minimum for 401(k)-type plans; 3% for Auto IRAs; escalates 1% annually to 10% cap

3-5% default (state-determined); automatic escalation (typically to 10%)

Employer Choice

Employers choose between establishing 401(k)-type plan OR facilitating federal Auto IRA

Employers choose between offering 401(k)-type plan OR registering workers for state Auto IRA

Employer Costs

$500/year tax credit for 3 years for employers with ≤100 employees offering Auto IRA

No employer fees or administrative costs for state Auto IRA participation

State Program Protection

Permits existing state programs (pre-1/1/2028) to continue; preempts future state laws after that date

Builds on and expands existing state programs; encourages all 50 states to participate

Lifetime Income Provision

Requires employers to offer employees with $200K+ vested savings option to convert up to 50% into annuity

Not specified; focuses on accumulation phase and emergency savings integration

Gig Worker Coverage

Explicitly includes gig workers and independent contractors in Auto IRA access

Coverage depends on individual state program design and eligibility rules

Additional Features

Includes provisions for converting savings to guaranteed income; integrates with existing tax credits

Emphasizes portability, emergency savings accounts, financial literacy resources, and Saver's Match access

Considerations. We expect you’ll have some opinions about what you see here – we do too! But more than anything, we love the idea of universal access to retirement savings at work. To see it happen, we’ve got to make it happen. In March, we’ll share a third proposal with yet different characteristics – stay tuned.


Retirement security matters! / Lisa

Hot Sauce! Cool Stuff

It’s the Ocean 🌊 series—we’ve got sandy beaches and a warm climate to hop into, so let’s get some cool sluff into your hands and get outta here.


1 – Did Boston College’s Center for Retirement Research find that state Auto IRAs are actually spurring MORE employers to adopt their own 401(k) plans? We heard they did. LOVVVEEE THISSSSSS.


2 – Are 530A Trump Accounts picking up steam? Yes, yes they are. The latest announcement comes from our own ICI – the Investment Company Institute. For a recent take on these accounts, see this piece from RSM November.


3 – We’ve been thinking about Out of Plan Emergency Savings—have you? Vanguard has—see the latest, here. We like choices, and this is a new one for plan participants—again, out of plan. Our friends at the BiPartisan Policy Center have, too.


4 – PALATE CLEANSER! Time for some start-of-year fun—ours come from YouTube this week.


A – Do you know Samurai Matcha? We appreciate his optimistic approach to life. Here he’ll bring you 26 Small Habits for a Calm, Healthy & Happy Life. Yes, please. We’re going to start wearing our shoes less.


B – So many things we did not know about the Moai – from Portland-based creator Stefan Milo. Have we added the island of Rapa Nui (aka Easter Island) to our must-see list? Yep yep. We need to see this in person.


C – And here’s a new favorite from Denver – Immy Lucas – we could listen to her talk about low buy, meal prep, and the insecurity of being 30 all day long. We’re not insecure – you’re insecure!


Please Make it Happen ... Pix of the Week!

Did we use AI to turn David John into the defender of retirement security that we know him to be? Maybe. Or, this is actually what David looks like when he's not on Zoom.

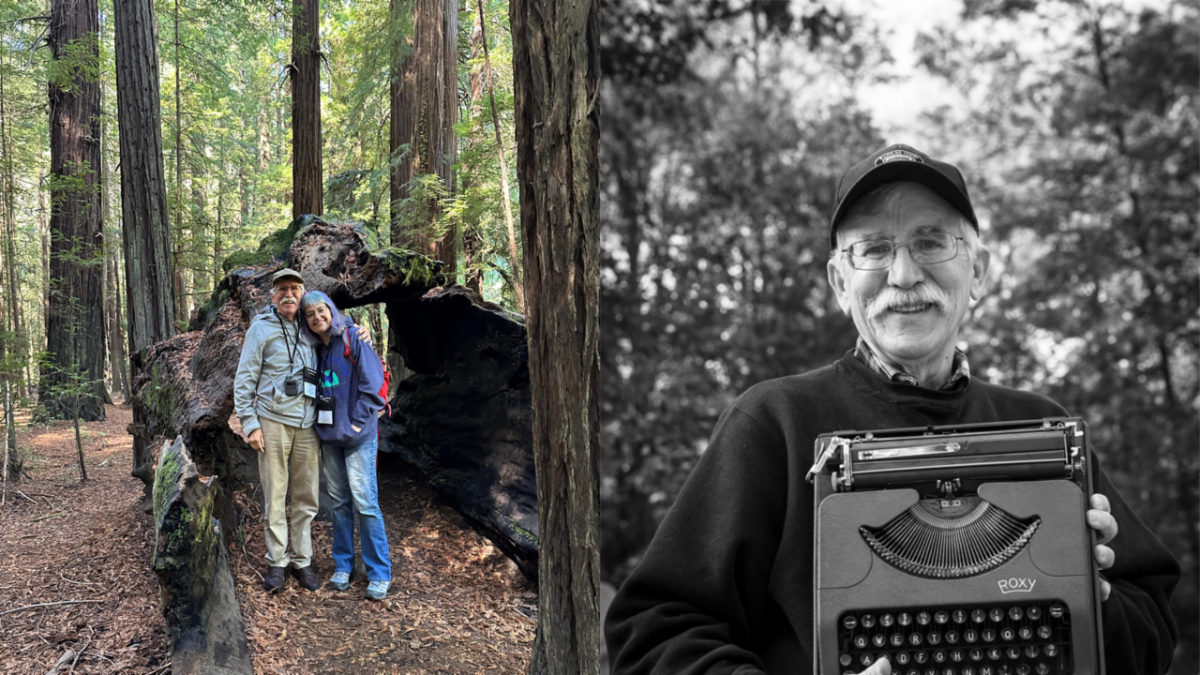
David is in tree-mendous company with his lovely wife, Sherri Philpott ❤️—and yes, that’s the man, the myth, and the manual typewriter.

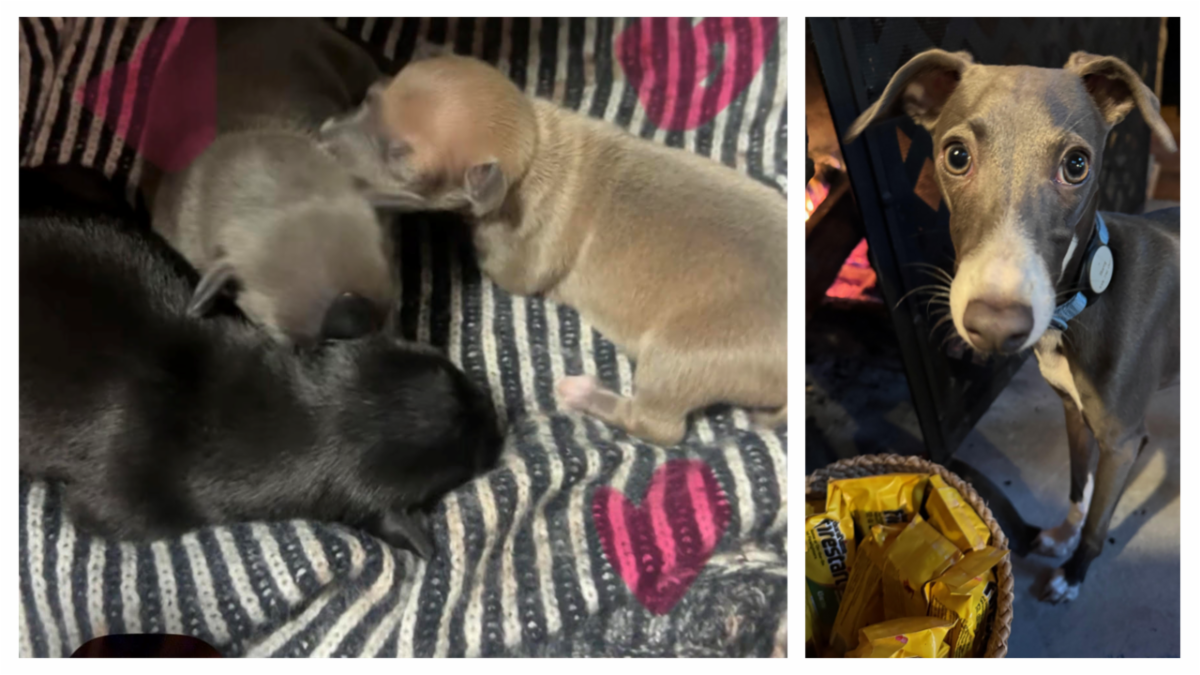
And in other news, little Harry is getting a sister. She’s just a little black potato blob at the moment, one week old in this shot on the left. Harry says, “What!”

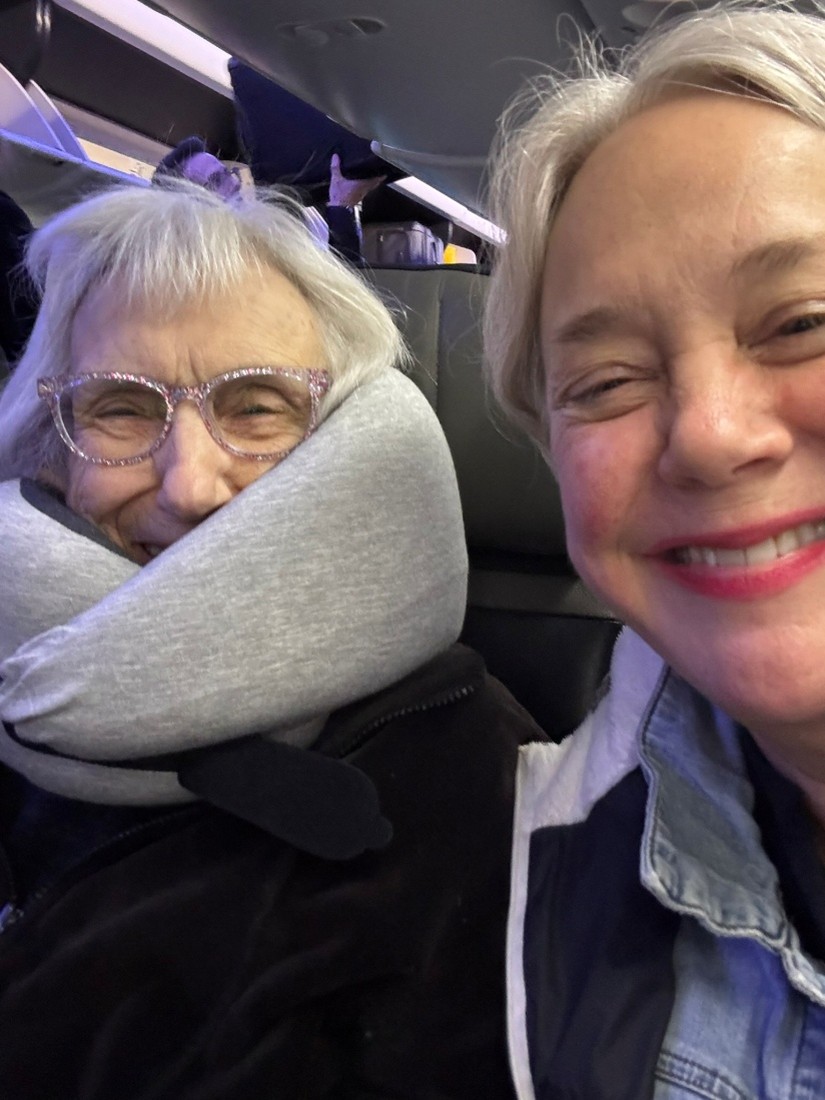
And no, we weren’t kidding about sunshine and oceans. This is Mom. We swear she’s smiling under that neck wrap. 🌊☀️🛫 She's headed to Costa Rica.

That’s it for this edition. ❤ Hug your people and change the world.


Massena Associates provides process, policy, and implementation consulting on retirement savings programs and products.


Our clientele includes public entities, policy organizations, and private sector providers. Our specialty – efficient, targeted results. We are an active speaker on retirement security topics, including state-facilitated programs, MEPs and more.


If you’d like to explore working together, we welcome the conversation. Connect with us here, and at 339-236-0684.

RESOURCES you can use:

Looking for a great retirement savings innovation resource? The Center for Retirement Research at Boston College develops and hosts terrific content and proprietary research related to states, financial security, social security, and more.


The Defined Contribution Institutional Investment Association (DCIIA) is dedicated to enhancing the retirement security of America’s workers. To do this, DCIIA fosters a dialogue among the leaders of the defined contribution community who are passionate about improving defined contribution outcomes. DCIIA's site provides a range of public and member-specific resources.


The Georgetown Center for Retirement Initiatives, Led by Angela Antonelli, GCRI provides excellent information on state-based and other retirement security innovation and policy.


Pew’s Retirement Savings Project studies the challenges and opportunities for increasing retirement savings and is another great resource - check out the work of John Scott and his terrific team.


If you want a great source of broad-based, consumer-focused retirement news, Jeffrey H. Snyder’s The Morning Pulse is your ticket. You can subscribe here.

massenaassociates.com

Linkedin  X