RETIREMENT SECURITY MATTERS

A forum for retirement savings innovation, together.

Vol 93 | July 17, 2025

Greetings!  Lisa, welcome to Retirement Security Matters—where we talk about retirement readiness innovation across public and private spaces. 

In this edition we’re serving up a delectable s’more of content. You know, a little melty chocolate on a graham cracker with a fluffy browned marshmallow of goodness. Pull up your camp chair, settle in, take a sip of lemonade—soft or hard—and enjoy an action break with us.


  • The System We Deserve – What? with Aspen’s Karen Andres and KC Boas
  • Fressssshhh State Auto IRA Stats
  • 2025 Innovation – Underscore, and More
  • Hot Sauce, Cool Stuff, Campfire Style … and
  • We got you -- Pix of the Week!

The System America Deserves: More, and Better

This week we’re sitting down with Karen Andres and KC Boas from the Aspen Institute Financial Security Program to explore what’s ahead for all things inclusive saving and investing. We cover some ground: Trump Accounts, the 2027 Saver’s Match rollout, and fresh thinking about financial diaries. Their take? America’s retirement system has some unfinished business. Let’s get after it.

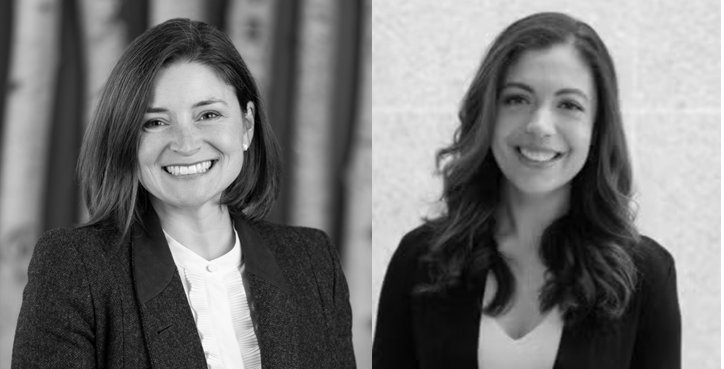
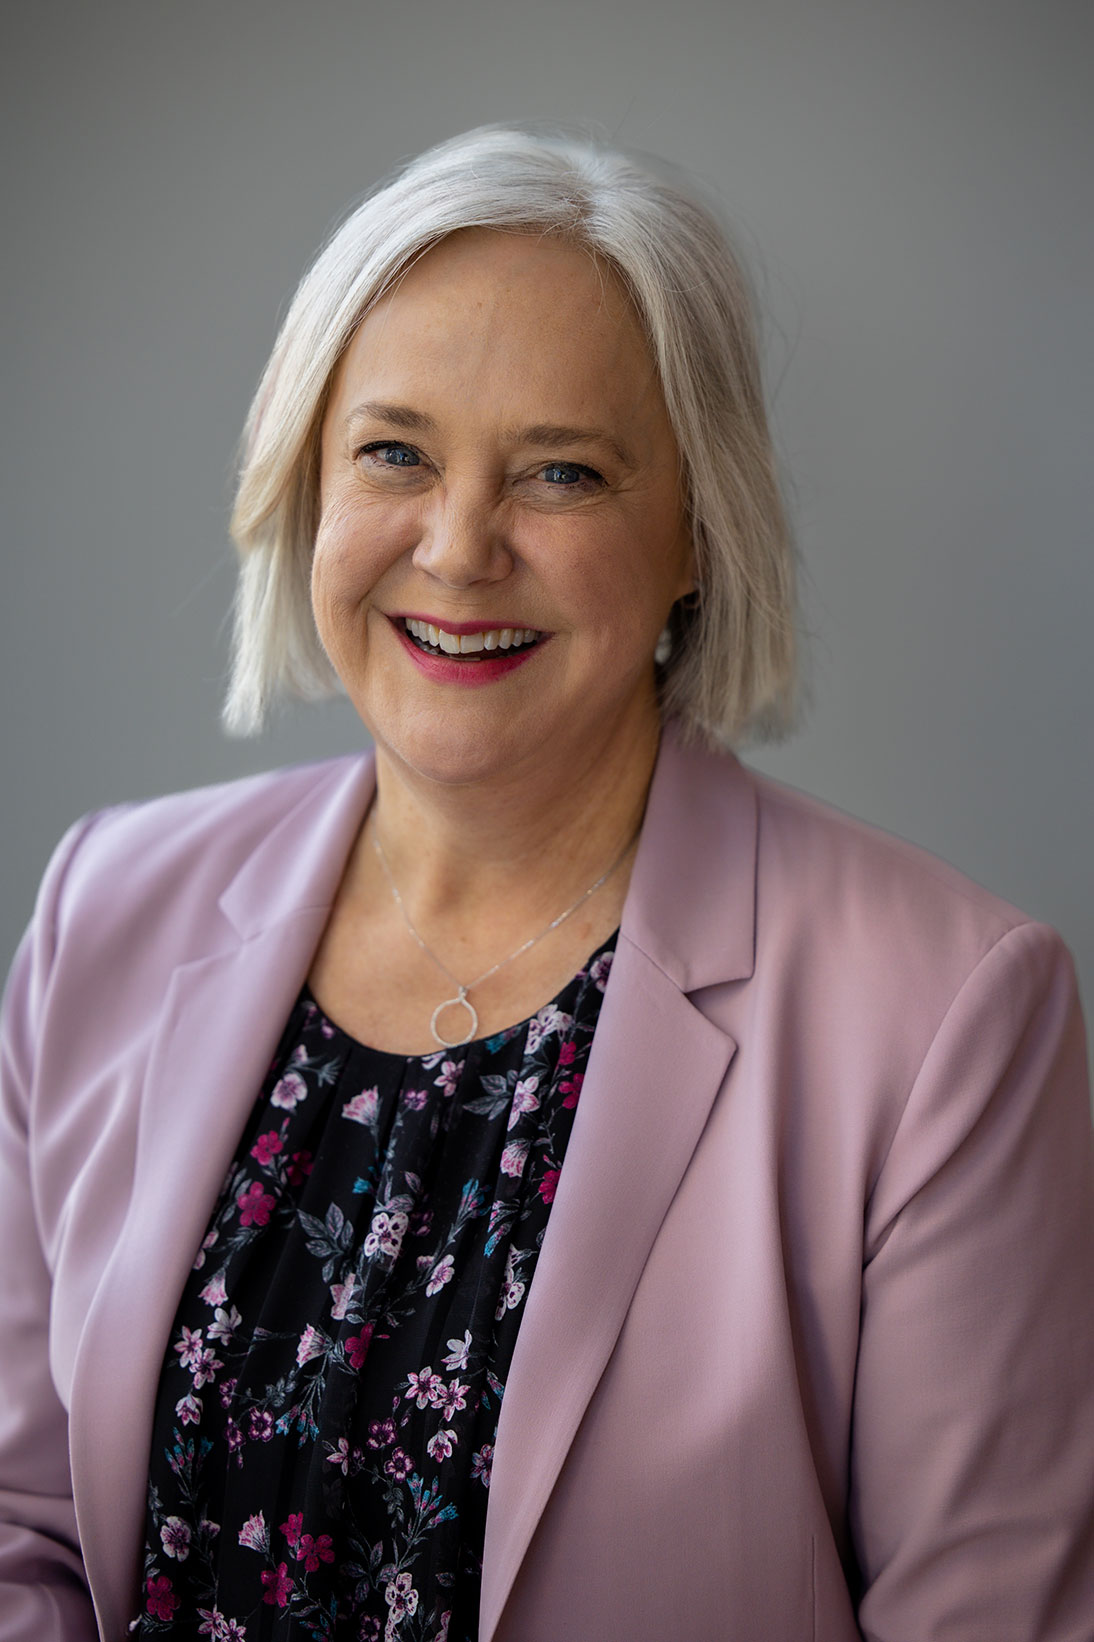
Photo: Karen Andres, Director of Inclusive Saving and Investing, and KC Boas, Retirement Savings Initiative Lead, Aspen Institute Financial Security Program

The following is a BRIEF excerptclick here to enjoy our full conversation.


Karen and KC, you’re both deep in the work of making financial security real for people. What are your current prioritieslet’s start with you, KC, on inclusive savings.


KC Boas: Yes—I’ll frame it this way. There’s a tension at the heart of this work: America’s retirement system is working for millions. And it’s failing millions. Both are true. But failure isn’t inevitable. The system isn’t working for many yet. And the “yet” is where we see opportunity.


Over the past few months, we’ve been scheming… Dreaming up what the next five years of our work needs to be. Our guiding principle was to start with the experience of the household. When you boil it down, the lifecycle of a retirement saver has three parts: access, saving & investing, and retirement. So, we’re organizing our work around that journey.


You’re also planning a financial diaries project for older Americans. We learned so much from the first work. Tell us more.


Karen: Yes. It’s a time-tested methodology that’s never been applied to older adults, so we’re breaking new ground. The appeal of this approach is that it marries real lived experience—I’m talking, sitting across from a retiree at their kitchen table and digging into the details of what’s happened in their financial life and why—with transactional data.


That’s what we plan to do with a sample of 100 low-wealth households, ages 55–75. What decisions and trade-offs are they making? How do they react to financial shocks? Where are the gaps? Uncovering the answers to these types of questions can drive better design of both policy and product. And this really matters given how close we are to a benefits cut for Social Security if policymakers don’t take action.


We’re in project funding, and looking for partners who want to help us press play.


Speaking of new policy—let’s talk about the Trump Accounts. Bring us up to speed.


Karen: They’re now the law of the land! There’s a lot to unpack there—and even more to figure out. As passed into law, these accounts are a traditional IRA—so, not a Roth—for all kids under 18, starting as early as birth, and who have a Social Security number.


But there are several unique features—like a $1,000 seed investment pilot program—some of which need to be clarified with the Treasury Department.


Over the past several months, we’ve held dozens of roundtables with 50+ stakeholders across sectors—and we’ve written extensively about those findings. But the bottom line is: . . . (this piece is continued heredon’t miss the rest of what Karen and KC have to say!) . . .


I think this brings us back to your point about the retirement system needing to work for everyone.


KC: Right. Because ultimately, we get to choose who this system serves. The design choices we make—about access, incentives, and, yes, data—will determine whether the next generation of retirees is more secure than the last. A system this consequential should work for everyone.


Karen and KC, what a terrific conversation, chock full of innovation, inspiration and great ideas. Thank you!


Get or stay connected with Karen and KC. Connect on LinkedIn: Karen Andres and KC Boas. Connect by email: Karen and KC. You can also follow their work at the Aspen Financial Security Program here. You may also be interested in readouts from the Aspen Leadership Forum on Retirement Security – you’ll find the 2025 readout here. You can catch up on past forums here.


As the Director of Inclusive Saving and Investing at the Aspen Institute Financial Security Program, Karen Andres works to spark both policy and market changes that will enable everyone in America to successfully save and invest in assets that grow. KC Boas is the Retirement Savings Initiative Lead at the Aspen Institute Financial Security Program. A longtime advocate for a holistic, people-centered approach to wealth building, KC works across the public and private sectors to develop retirement solutions that benefit all households.

By the Numbers: State Auto IRAs Today

What’s UpStates!


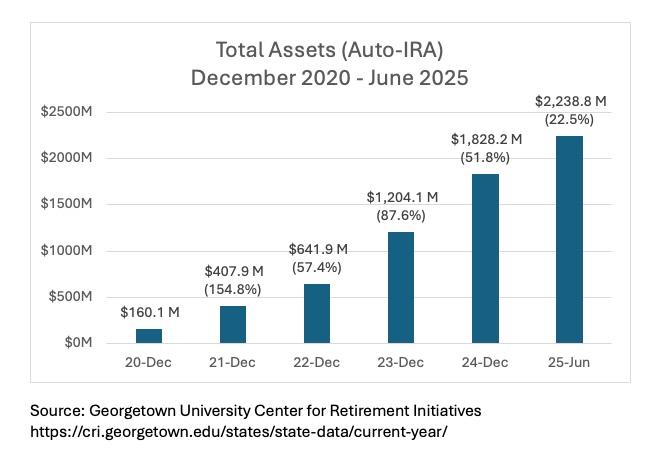
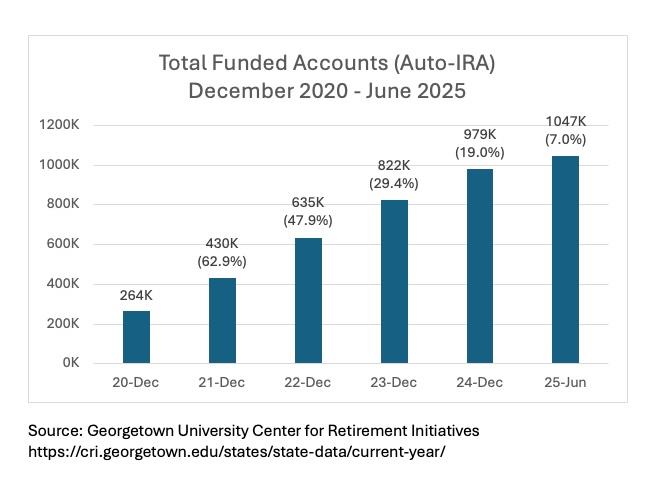
We hope you enjoy this view as much as we do. What’s here: growth in assets and growth in funded accounts across the Auto IRA universe over the past five years. By December 2020 across three programs we’d achieved $160 million saved in about 264,000 accounts. Not bad, not bad.


As of June 30, 2025, we are at $2.2 billion in about 1.05 million accounts. We like this. You can see the impact of more states and programs coming online, and the steady growth over time. States and savers, we applaud you. Well done.


Thank you to Angela Antonelli and the Georgetown Center for Retirement Initiatives for this data. You’ll find more detailed metrics and information on their site, here

2025 Innovation: Underscores, and Other Ideas

If you read the opening piece, you know our friends at Aspen have given us much to think about. Giving you a little more, we’re going to tie their comments into the perspectives of a few others.


We’ll start with BlackRock and the Bipartisan Policy Center. You’ll find both cross-pollination and some common thinking in this piece, summarizing the 2025 Retirement Summit these two held in DC this spring. The room was buzzing. You’ll recognize these priorities: 1 - expanding access to retirement plans in both public and private sector ways; 2 - adding the buffers of emergency savings and early wealth building; 3 - looking at retirement income in new ways. And the Summit included specific elements related to strengthening DB plans—they’re not dead yet, folks—and proliferating more of the best practices of employee education and auto-features to strengthen DC plans.


Our friends at IRI – the Insured Retirement Institute -- published their 2025 Federal Retirement Security Blueprint in March as well. Unsurprisingly, they stress the importance of retaining favorable tax treatment for retirement assets and keeping available a wide variety of private sector solutions (vs. one federalized solution). They’d also like to see a requirement that employers offer one of these private sector plans. We feel differently—we like a requirement that employers offer or facilitate, because we think plenty of employers are not ready for the responsibility associated with offering a plan—but smart people don’t have to agree on everything!


IRI would also extend program availability by lowering the workplace plan participation age to 18, and allowing state-legal cannabis businesses to offer plans. And they’d increase usage by automatically re-enrolling employees three years after opt out. There’s much more—check it out—and re-enrollment seems to be having a moment in the sun. Let’s make that sunny place bigger.


And, here’s one more item responsive to the comments above about Social Security solvency. This month Senators Cassidy (LA) and Kaine (VA) propose the creation of a $1.5T supplemental trust fund, funded over a ten year period and invested in equities and ‘other investments that generate a higher rate of return,’ intended to close the Social Security funding gap and maintain benefits. As we mentioned recently, an overwhelming chunk of Americans—young and old alike—would prefer an increase in funding to the program over a reduction in committed benefits. Even if they have to pay more in taxes. Thank you, Senators, for advance and creative thinking.


Say it with me:

Retirement security matters! / Lisa

Hot Sauce! Cool Stuff—Campfire Style

We have hit you with enough technical stuff for one day. 🔥Let’s have some fun.


1 – S is for Tom Selleck—We’ve just listened to his autobiography - #recommend. It offers a gentle, insider’s view of Hollywood and a great refresh of things we’d forgotten from the 90’s. And we like him even more now.


2 – M is for Minimalism—we’ve been bingeing Gabe Bult, and we think you’ll like this one (caution, sound). There’s nothing as refreshing as a summer possessions purge. Nothing.


3 – O is for Online Only—in the cloud, Baby. We bought this scanner and we are getting rid of every single piece of paper that crosses our path. Visual minimalism. It’s a work in progress.


4 – R is for Retirement—uhh, obviously! We like @bill_retired—for an insider’s view of how to think about it like a regular person. Again, sound warning. Also, TikTok. Here’s another perspective, from @koereyelle. We had to look for it, cuz our TT full of white people our own age. #algorithms


5 – E is for Energy—our current morning mantra: Energy. Balance. Focus. It’s working.


We hope this brings you SMORE delight today.

And Finally, ... YES it's Pix of the Week!

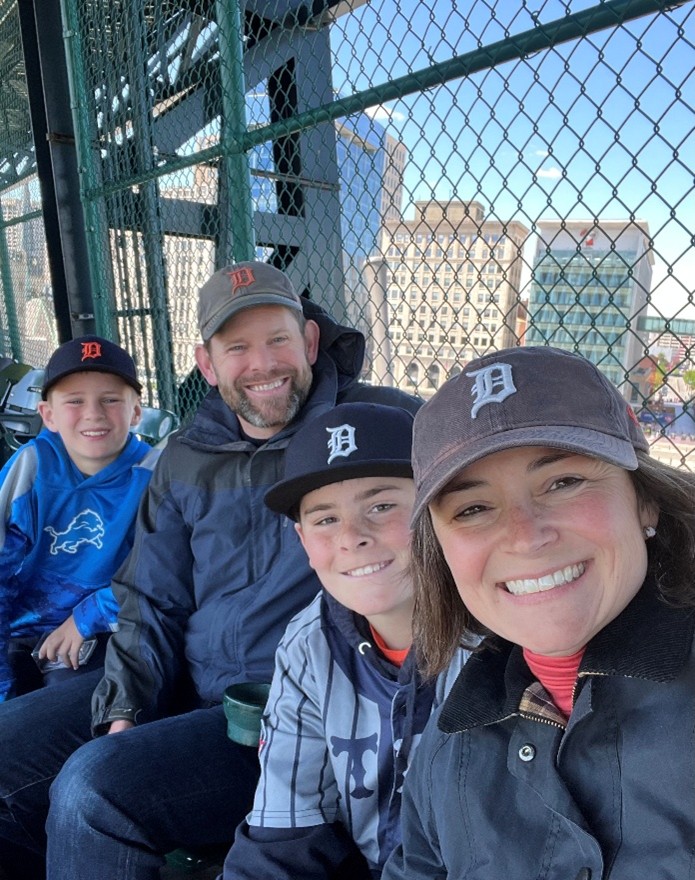
We think we are well known for our love of ⚾. So when @KarenAndres shared this picture, we fell in love.


First of all, that is a great looking set of boys! All three of them. Nice Tigers regalia.


Karen sez: my boys are ALL IN on the MLB-leading Detroit Tigers! In fact, this game ended up being a shut-out for our ace pitcher, Tarik Skubal.


Fortunately, they were playing the Guardians, not the Red Sox, so we can enjoy the shutout with you. 

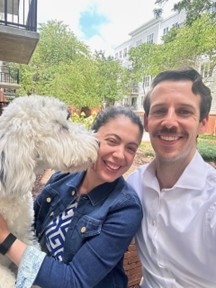
And @KCBoas shares a little more summer delight – with husband Henry and their pup Nessie. What cuties! 


Kisses ❤️ all around.

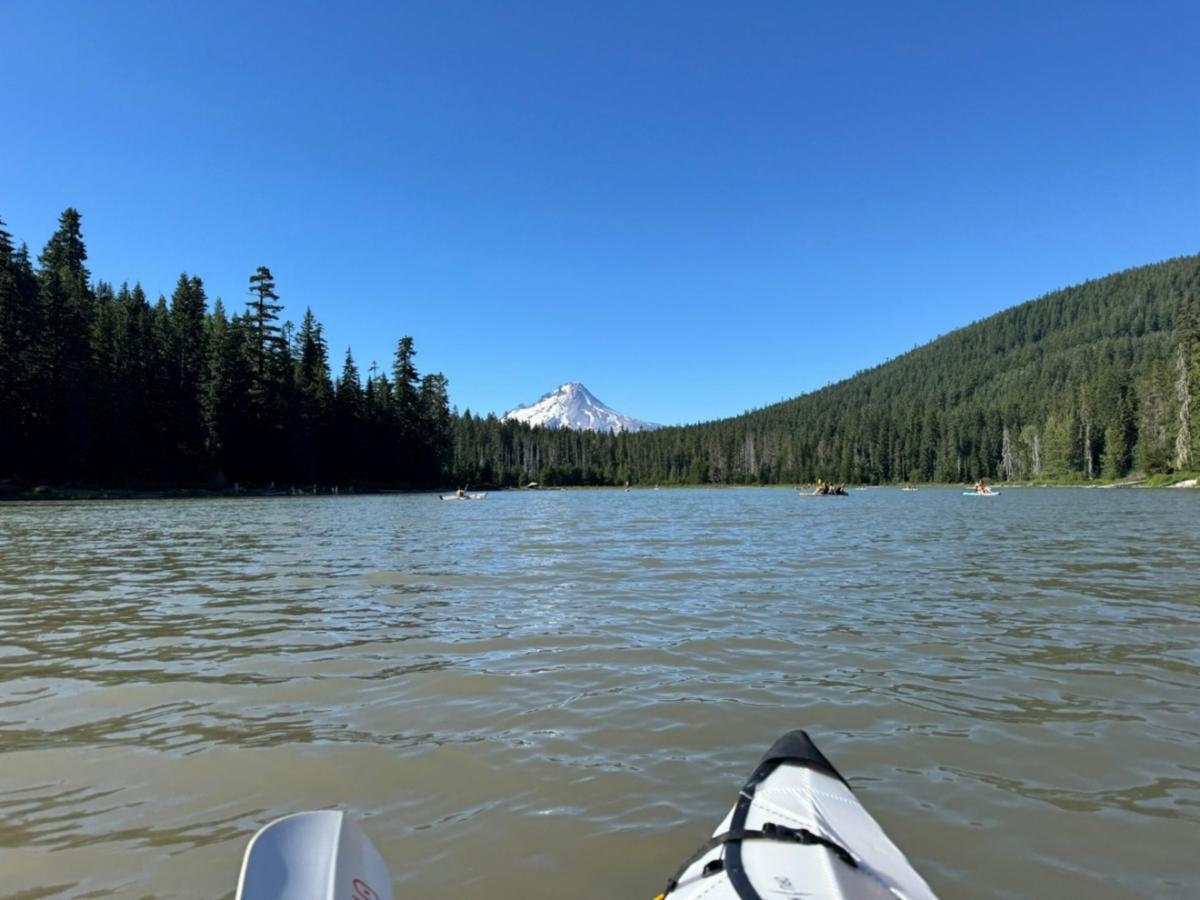
And, if you find yourself in Oregon this summer, you may take a paddle around Frog Lake while admiring Mount Hood and working on your tan. Will you see frogs? Yes, yes you will. Tiny, croaky, cute. All over. Enjoy!

That’s it for this edition. ❤ Hug your people and change the world.


Massena Associates provides process, policy, and implementation consulting on retirement savings programs and products.


Our clientele includes public entities, policy organizations, and private sector providers. Our specialty – efficient, targeted results. We are an active speaker on retirement security topics, including state-facilitated programs, MEPs and more.


If you’d like to explore working together, we welcome the conversation. Connect with us here, and at 339-236-0684.

RESOURCES you can use:

Looking for a great retirement savings innovation resource? The Center for Retirement Research at Boston College develops and hosts terrific content and proprietary research related to states, financial security, social security, and more.


The Defined Contribution Institutional Investment Association (DCIIA) is dedicated to enhancing the retirement security of America’s workers. To do this, DCIIA fosters a dialogue among the leaders of the defined contribution community who are passionate about improving defined contribution outcomes. DCIIA's site provides a range of public and member-specific resources.


The Georgetown Center for Retirement Initiatives, Led by Angela Antonelli, GCRI provides excellent information on state-based and other retirement security innovation and policy.


Pew’s Retirement Savings Project studies the challenges and opportunities for increasing retirement savings and is another great resource - check out the work of John Scott and his terrific team.


If you want a great source of broad-based, consumer-focused retirement news, Jeffrey H. Snyder’s The Morning Pulse is your ticket. You can subscribe here.

massenaassociates.com

Linkedin  X