|
RETIREMENT SECURITY MATTERS
A forum for retirement savings innovation, together.
Vol 101 | April 16, 2026
| | |
Greetings! Greetings! welcome to Retirement Security Matters—where we talk about retirement readiness innovation across public and private spaces. | |
But first, taxes. Have you filed? More on this later. And as a palate cleanser, let’s give you some very pleasant new things to think about. We’re enjoying spring flowers, and the thought that with the right kind of federal legislation a thousand more flowers could blossom, and the reality of a lot of cool things coming to life as our shared technical capabilities grow.
You’ve just done—or pushed off—your taxes. You should probably read this edition with a beer in your hand. For you this week our great stuff includes:
-
Advice, Anyone? The Missing Layer with Amy Chou
-
State Auto IRAs – By the Numbers
-
States in Action – Auto IRAs and More
-
Reporting from the Rooms: Aspen Leadership Forum on Ret Svgs 2026
-
Hot Sauce! Cool Stuff ... Reader's Version ... and
-
Pix of the Week! Woohoo.
| | The Missing Layer: Advice | | |
AI, human advisors, and a company trying to close the gap between saving and knowing—with Addition Wealth’s Head of Product, Amy Chou
We’re getting better all the time at getting people into retirement accounts. Coverage is up. Funded accounts are up. Auto IRAs are opening new doors for millions of workers who never had a shot at a workplace account.
But here’s an uncomfortable question: is enrollment enough if no one helps you figure out what to do next?
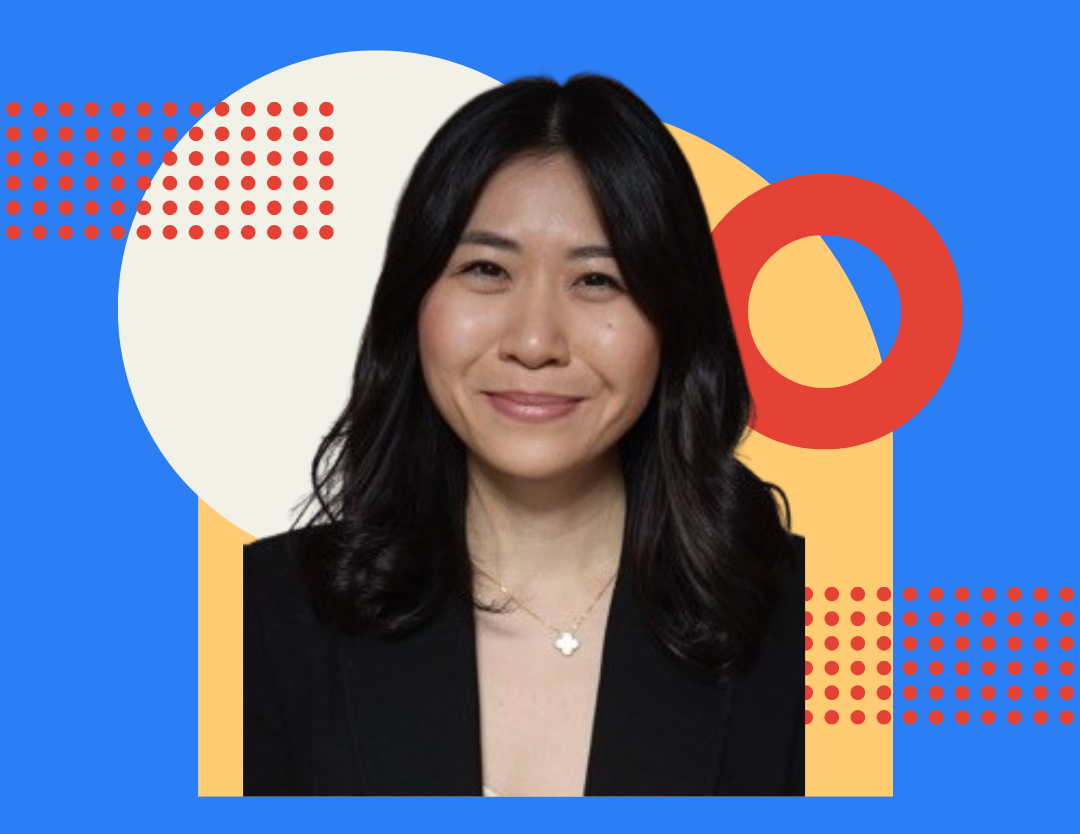
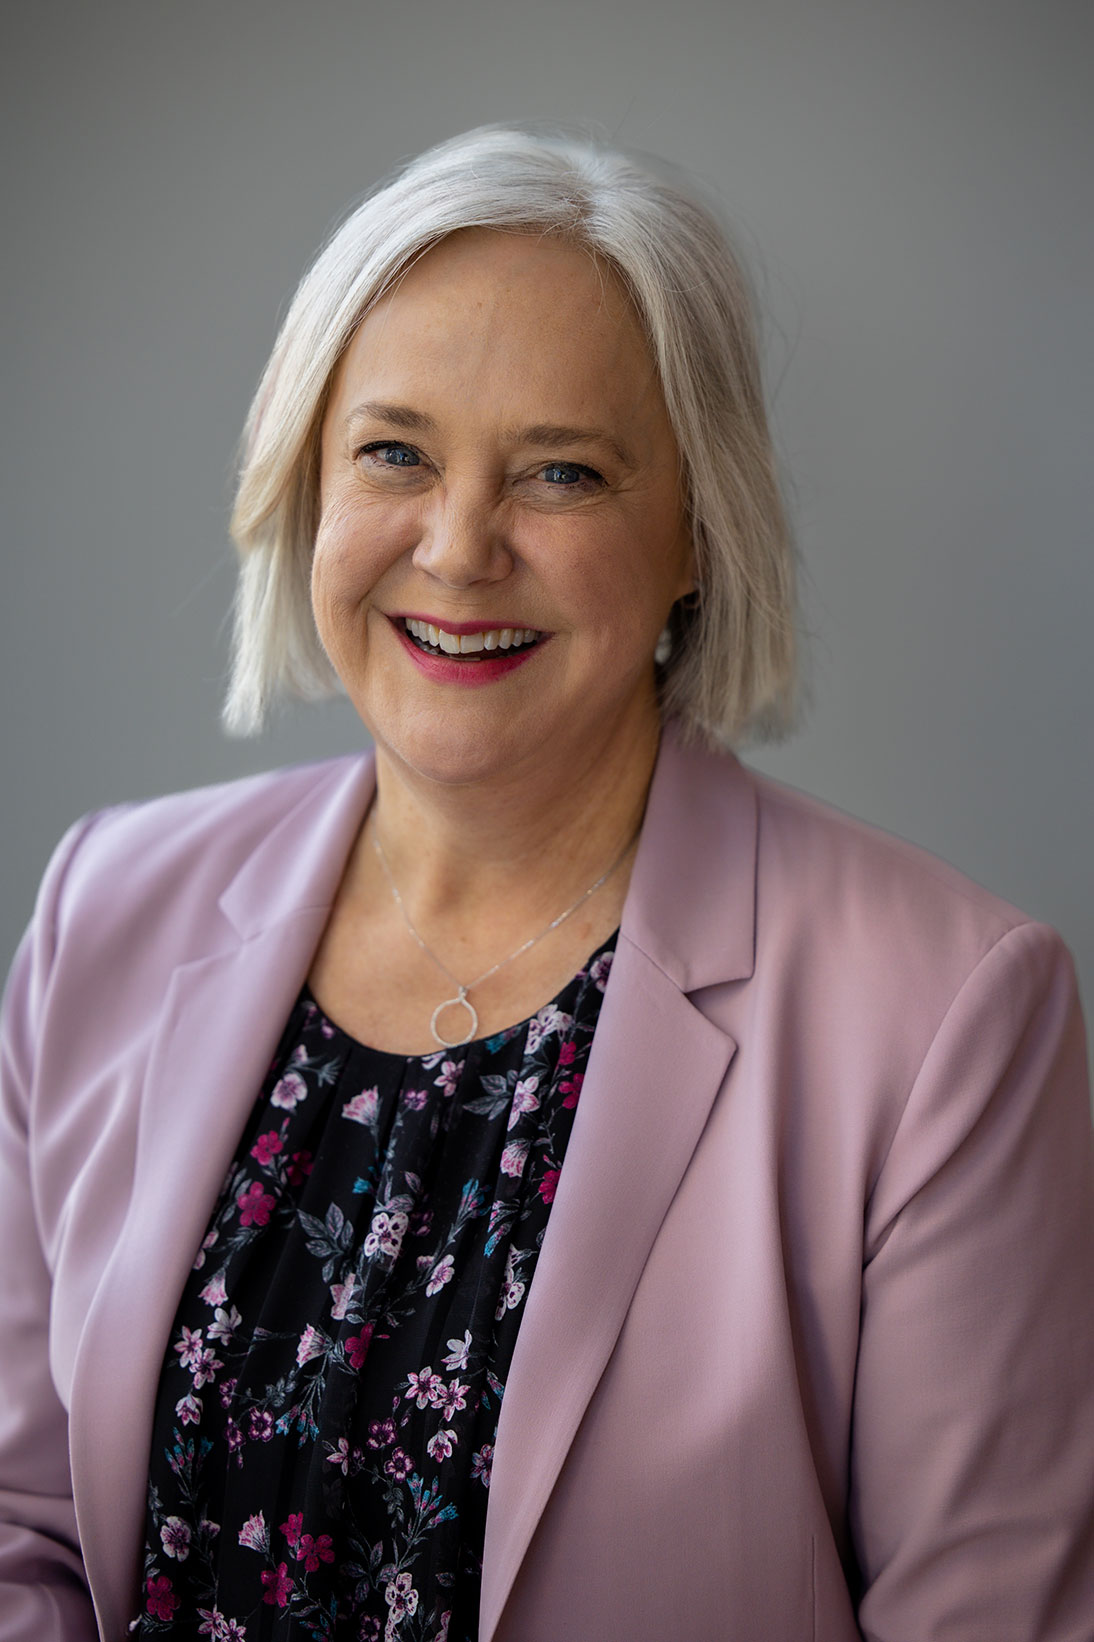
That’s the question driving a growing corner of the fintech world—and it’s the question we put to Amy Chou, Chief Operating Officer and Head of Product at Addition Wealth, a New York-based financial wellness company doing something pretty fresh in the advice space. Chou is a founding team member who came up through J.P. Morgan, Uber, and Jet.com. She knows how to build things at scale. And what she’s building now is a platform designed to give workers—including—maybe—workers in state Auto IRA programs—something most of them have never had: personalized financial guidance.
Our full conversation is live here. Here are three things that stayed with us. PS we go deep on Addition Wealth, but this is not an ad. It’s an example. We love this space, if you have more good examples for us, please share.
Thing 1: Can a platform know your next move before you do?
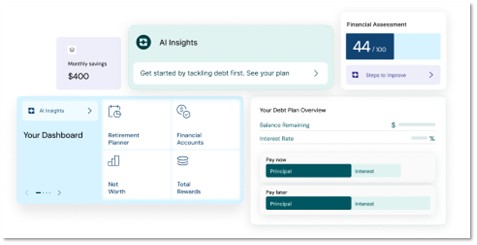
Addition Wealth works primarily through plan sponsors and financial institutions, which means they start with a data-rich picture of each participant—benefits elections, payroll information, personal finance accounts. They use that data to power what Chou calls “next best decision” and “next best action” recommendations: not just a dashboard showing where you stand, but a specific, actionable prompt for what to do next.
One of the ways they keep this current is a real-time integration with payroll and HRIS providers, so when a participant gets a raise or changes their contribution rate, the platform reflects it immediately. No waiting for a monthly data dump. The picture stays fresh.
| | Example screenshot provided by Addition Wealth. | | |
That might sound like table stakes—but most retirement platforms aren’t doing this. We can think of the many retirement accounts we’ve clung to over the years, watching capabilities evolve. And we believe most participants are still making decisions using a lot of guesswork, or darts. Addition Wealth is trying to change that. And when the complexity of a decision tips past what a digital tool can handle, users can click through to a live, vetted advisor. The seam between tech and human—that’s the part Chou says they care most about making invisible.
Read more about the platform — and the Edward Jones partnership — here →
Thing 2: Flexibility isn’t a feature. It’s a key strategy.
We asked Chou what Addition Wealth is learning as the offering scales. Her top answer was direct: nobody actually knows what the ultimate solution looks like yet, because the technology is moving so fast. We feel this, Amy. Yes.
She’s not just talking about AI capabilities—though those are also shifting by the day. She’s talking about participant expectations, regulatory frameworks, and the very definition of what “good” financial guidance looks like in a digital context. Her response, as a product person: build flexibility in from the start, because rigidity is the real risk.
Industry research backs this up—and adds a dose of caution. A Transamerica Institute study surveying more than 300 retirement industry experts projects AI as a major catalyst in plan administration and participant experience, but flags open questions about how governmental oversight will keep pace and where legal liability will land if AI-driven recommendations go sideways. Those are real questions.
On the opportunity side: an Accenture report published in late 2025 estimates that improvements in participant engagement—with AI and behavioral economics as key drivers—could unlock up to $405 billion in 401(k) assets under administration by 2034. That’s a lot (quiet understatement).
Get the full breakdown — including metrics that really got our attention — here →
Thing 3: Auto IRA participants may need this most.
Here’s the part that stopped us.
We asked Chou directly whether the kind of personalized guidance Addition Wealth provides is really applicable to state Auto IRA programs—or whether it’s fundamentally a 401(k) product, built on the rich data infrastructure that employer-sponsored plans provide.
Her answer: the data challenges are real, but Auto IRA participants may actually need these services more than their 401(k) counterparts. Many are saving for the first time. Many work for small businesses with no benefits infrastructure. They don’t have an HR department to call, or a plan administrator running webinars. They’re navigating financial decisions without the support that 401(k) participants take for granted.
Addition Wealth has an intake protocol designed to bridge the data gap—a series of straightforward questions that builds what Chou calls a “mosaic” of information about an individual, supplemented by third-party data subscriptions. It’s not perfect. But it’s more than most Auto IRA participants are getting today.
The broader point landed hard: we spend a lot of energy closing the coverage gap. We spend a lot less energy making sure that newly covered workers can actually do something useful with their accounts. That’s the advice gap. And if we can get comfortable with the quality and integrity of AI-assisted delivery, it may be one of the more powerful tools we have to close it.
Catch our full conversation — including what Chou says about 530A Trump Accounts and why she’s bullish on what comes next →
One more thing.
In our final exchange we asked Chou whether she worried that AI was going to displace the human advisors she works with. She didn’t hesitate: humans aren’t going anywhere. These tools help people do their work better. At the end of the day, human-to-human advice still matters—it’s just going to be supported in a far smarter way.
Recent survey data bears that out: more than half of participants say human oversight and transparency about how AI decisions are made would significantly increase their trust in these tools. The future isn’t human or technology. It’s both, working together—and the companies who figure out how to make that feel seamless are going to be very interesting to watch.
About Amy Chou
Amy Chou is Chief Operating Officer and Head of Product at Addition Wealth. Connect with her on LinkedIn or by email. Addition Wealth is headquartered in New York.
| | By the Numbers: State Auto IRAs Today | | |
March 2026 Snapshot
-
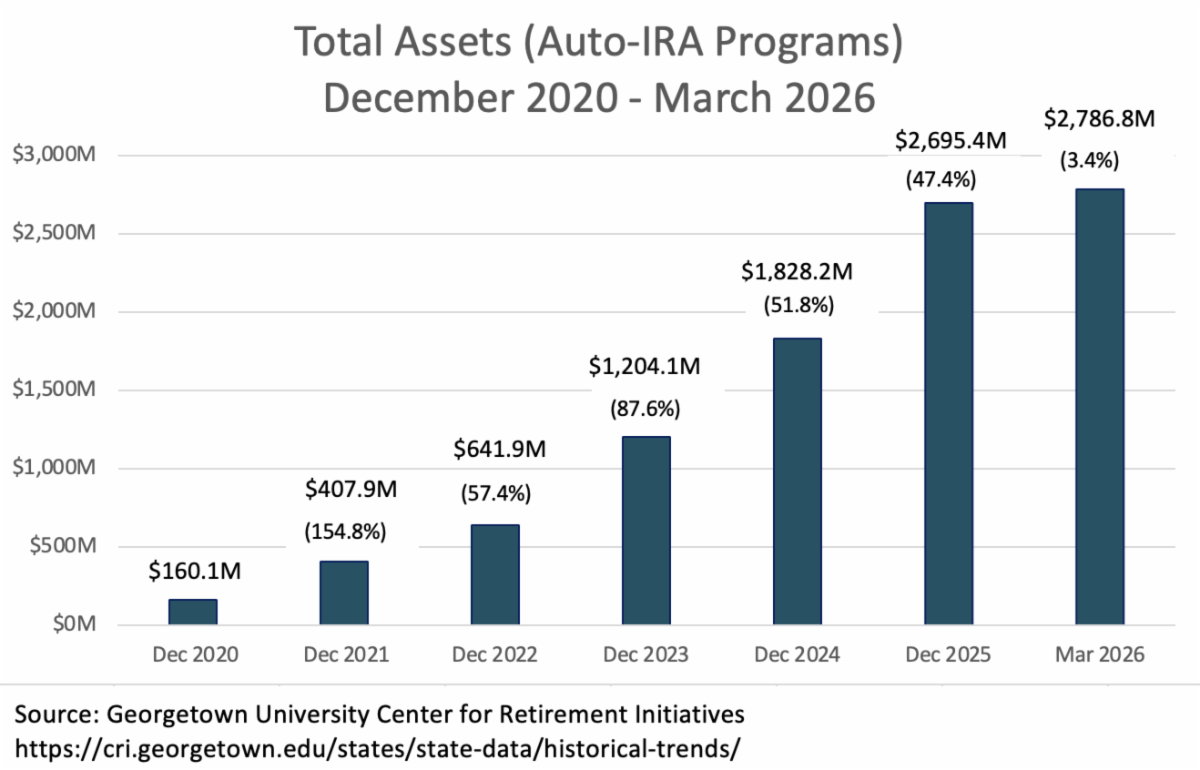
Total Assets: $2.8 billion across all state programs (end of 2025: $2.75 billion)
-
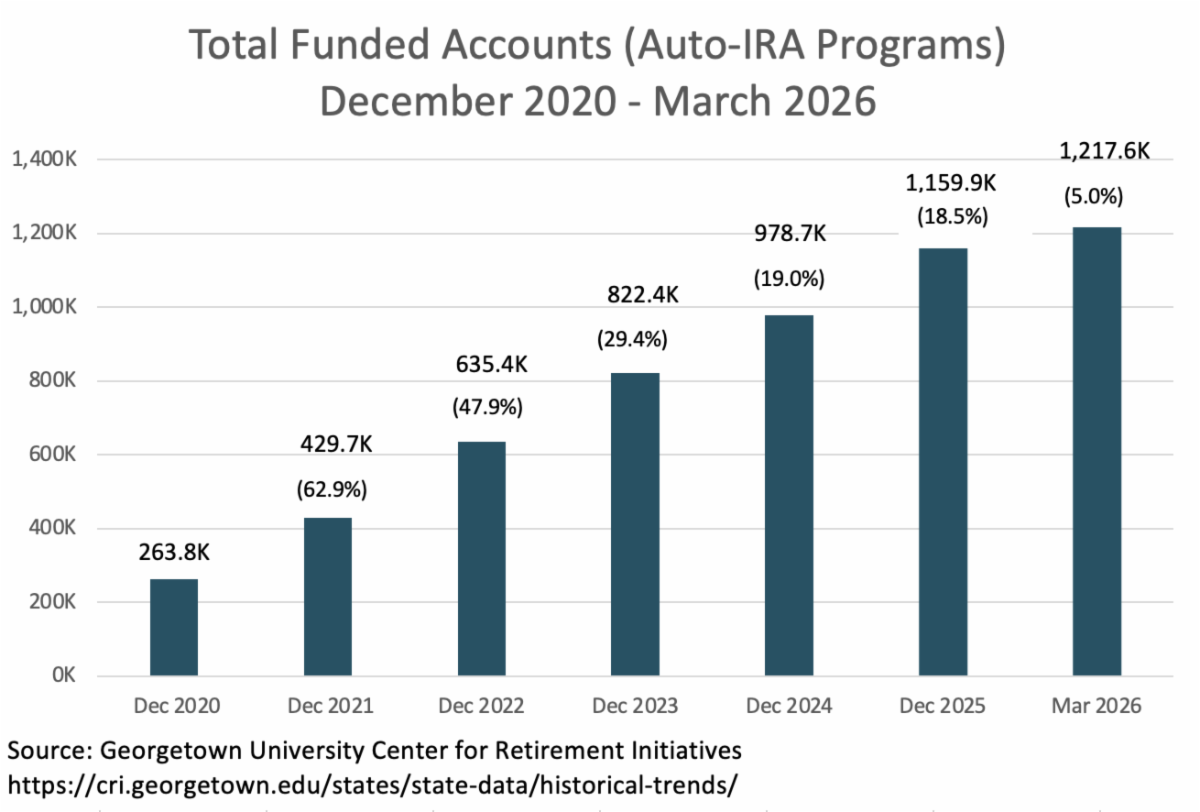
Funded Accounts: 1.22 million savers now have accounts
-
Average Balance: Currently $2,288—earlier accounts have higher balances
-
Five-Year Growth: From $160 million (2020) to nearly $3 billion (2026)
There’s a war on – but funded accounts are still growing. Year to date we are up 5%. Assets are down from February (market movement) but up 3.4% for the three months ended March 31. We think funded account growth is more important. We anticipate that early 2026 growth will be good but modest, and that we’ll start to see some oomph in Q2 and Q3 as more programs come online.
Funded Account overall growth rate—19% in 2024, 18.5% in 2025
Our friend Claude tells us these are the recent and upcoming State Auto IRA deadlines. Use your imagination as you think about how large some of these states are:
Q1 2026 (January – March)
-
January 1 — Minnesota Secure Choice opens to all eligible employers and workers
-
January 1 — Vermont Saves Wave 2: employers with 15–24 employees
-
January 20 — New Jersey: Gov. Sherrill signs A5358, lowering RetireReady NJ threshold from 25 to 10 employees
-
March 18 — New York Secure Choice Wave 1: employers with 30+ employees
Q2 2026 (April – June)
-
April 1 — New Jersey RetireReady NJ: deadline for employers with 10+ employees
-
May 15 — New York Secure Choice Wave 2: employers with 15–29 employees
-
July 1 — Vermont Saves Wave 3: employers with 5–14 employees
-
July 1 — Connecticut MyCTSavings: personal care attendants added as covered employees
Q3 2026 (July – September)
-
July 15 — New York Secure Choice Wave 3: employers with 10–14 employees
-
Mid-to-late 2026 — Hawaii HRSP anticipated launch (exact date TBD)
-
October 15 — Rhode Island RISavers Wave 1: employers with 100+ employees
A special thank you to Angela Antonelli and the Georgetown Center for Retirement Initiatives for the program metrics data shared above. You’ll find more detailed metrics and information on their site here.
| | States in Action - Auto IRAs and More | | |
“And More” means we’ve got two new program types enacted this month. The states have been busy—here’s a quick recap.
A quick “thank you” to our colleagues in retirement-security land. We’ve pulled this roundup from a range of sources, including state sites, AARP, ASPPA, The Georgetown Center for Retirement Initiatives, PSCA, and the websites of and conversations with our state program friends.
| | |
Mississippi — Work and Save Program Enacted April 2026
Gov. Tate Reeves signed HB 4073 on April 8, creating the Mississippi Work and Save Program. The bill moved fast—introduced by Rep. Jody Steverson on Feb. 24, passed the House 118-1 the next day, and both chambers adopted the conference report on March 29. One notable feature: Mississippi's program is voluntary, meaning employees must affirmatively choose to participate rather than being auto-enrolled (echoes of Hawaii’s original bill). We think employers are required to facilitate, but the language to date is squishy. Participating employees will contribute to a Roth IRA with a target date fund default and a 5% starting contribution rate. Interestingly, the Senate added an amendment allowing the Mississippi Deferred Compensation Plan and Trust to offer Roth and other after-tax vehicles. Implementation must be substantially completed by July 1, 2028, with contributions beginning no later than August 1, 2028.
| |
Utah — Retirement Plan Exchange Signed March 2026
Gov. Spencer Cox signed HB 250 on March 24, creating the Utah Retirement Plan Exchange—a model in which the state facilitates a marketplace for private-sector retirement plan providers rather than running a state-administered IRA. Echoes of Washington State’s original and very lightly used Small Business Retirement Marketplace. The exchange platform must be set up by November 2, 2026, and begin operations by January 1, 2027.
Several states successfully enacted program expansions this season:
New Jersey — RetireReady NJ Expanded to 10+ Employees (April 1 effective)
The employer threshold dropped from 25 to 10 employees, with a 3% default contribution rate for enrollees who don't select a level. New Jersey Department of the Treasury Gov. Mikie Sherrill signed A5358 into law on January 20. The Senate passed it 24-15 and the Assembly 50-22, both on January 12. April 1, 2026, was the deadline for the newly covered employers.
Virginia — RetirePath Expansion to 5+ Employees
SB 149 passed the Virginia Senate unanimously and would expand the RetirePath mandate from 25 employees down to 5, while also folding in part-time workers and minors. April 13 was the deadline for the Governor to sign, veto, or take no action—allowing the bill to become effective as law.
California — CalSavers 1+ Employee Mandate Now in Effect
As of January 1, 2026, all California employers with one or more employees are required to provide access to a qualified retirement program or certify an exemption with CalSavers, with financial penalties for continued noncompliance.
Connecticut — MyCTSavings Personal Care Attendant Expansion
Personal care attendants will be included as covered workers for purposes of MyCTSavings beginning July 1, 2026. Connecticut also added provisions for participants receiving a federal Saver's Match contribution and new noncompliance penalty procedures for employers.
Research Note: New from Pew
Our friends at the Pew Charitable Trusts have just published findings from 2023 survey work showing bipartisan small business support for auto-IRA programs: 84% in Massachusetts, 76% in Pennsylvania, and 73% in Washington. Support was strongest among newer firms.
| | Reporting from the Rooms: Aspen Leadership Forum on Retirement Savings – April 2026, Baltimore | |
We joined the Aspen team and partners for three days of retirement consideration in Baltimore this month. Aspen will have a terrific report following this that we can’t do justice to, but we can share some of the considerations (and reads which were shared with us), which included:
1 – Four national retirement savings proposals on the board today—commonalities, differences, pros and cons? What does ‘universal access’ mean—and what should it look like.
Auto IRAs -- As proposed through Ranking Member Neal’s (D-MA) Automatic IRA Act of 2025.
Auto-IRA Plus (AARP) -- Auto IRA Plus: Expanding Retirement Access Through State Auto IRA Programs and as covered by us here.
A TSP-for-All Model – as proposed in the Retirement Savings for Americans Act of 2025, introduced by Sens. Hickenlooper (D-CO) and Tillis (R-NC), and U.S. Reps. Sewell (D-AL) and Smucker (R-PA).
And President Trump’s endorsed coverage proposal – as announced at February’s State of the Union Address.
… and to help with the framing, some fresh work from the Bipartisan Policy Center here: The Next Step for Retirement Security Is a Nationwide Minimum Coverage Standard.
2 – Things we thought we knew / and what we do know now—our takeaways:
a. From SaverLife – fresh perspectives on the priority and realities of LMI families and the opportunity to save for retirement
b. From Pew – new plan formation in Auto IRA states is impressive—in 2023 all program states were at or above the national average of 9%, and Colorado led the nation with a rate of 18%. See for yourself, just published.
c. From Gusto – in Auto IRA states their retirement plan business is growing at 2x the rate they experience elsewhere
d. From H&R Block – a tax time focus on 530A Trump child investment accounts has yielded big voluntary enrollments
e. From NEST UK and a research partner – automatic enrollment is a ‘very sticky nudge’ and can serve as a double-edged sword. Saver engagement matters. And, should we be thinking about ‘Auto Keep’ features—including immediate enrollment, immediate vesting, no force-outs, no loan defaults (allow post-employment repayment).
Please stay tuned for an important post-event report out from The Aspen Institute Financial Security Program.
This information is shared with the permission of those organizations mentioned.
| Hot Sauce! Cool Stuff - Just for you. | |
OK! We have worn ourselves out doing our taxes ourselves for the first time in about thirty years. #Recommend—there’s nothing like it to get closer to what’s going on under the hood of your family finances. This year we used FreeTaxUSA, as recommended by our fee-based financial planner BIL Bob—and it wasn’t too bad. If we get it all wrong / get audited, we will report back.
This week's HSCS is therefore focused on all the books we read while we were avoiding doing our taxes, snack style:
As an appetizer – we've just finished David Sedaris' Calypso. Twenty-one essays about aging, family, mortality, and a beach house called "the Sea Section" ehhh .. Here we enjoy Sedaris at both dark and warm, snide and funny. If you've ever laughed until you were slightly horrified at yourself, you’ll appreciate the second to last piece about insults around the world.
As an entrée – Educated, by Tara Westover. We could not put this down, because Westover does such a good job writing about what it’s like to grow up in rural Idaho working and home-schooled but, in her case, really without school, and off the structural grid of doctors, town life, and even birth certificates. She taught herself enough to win a Gates Cambridge Scholarship and earn a PhD in history. We’d like her to write more; what a powerful story.
As a main course – Viola Davis – Finding Me. Davis traces her journey from a crumbling apartment in Central Falls, Rhode Island, to EGOT status in Hollywood (we had to look it up too – that’s Emmy, Golden Globe, Oscar, and Tony). She holds nothing back and this memoir hits. Her stories are hard to hear sometimes, very hard to put down, shocking, funny, and very very real. Read it.
For dessert – The Unselected Journals of Emma M. Lion by Beth Brower—yes we read all eight novellas flippity flappity—great escapism. Set in 1883 London, Emma is witty and opinionated, navigating inheritance drama and eccentric neighbors through the pages of her journal. Readers compare it to Jane Austen meets P.G. Wodehouse, which should tell you everything you need to know. If you’re on Audible, it’s narrated by Genevieve Gaunt, chef’s kiss.
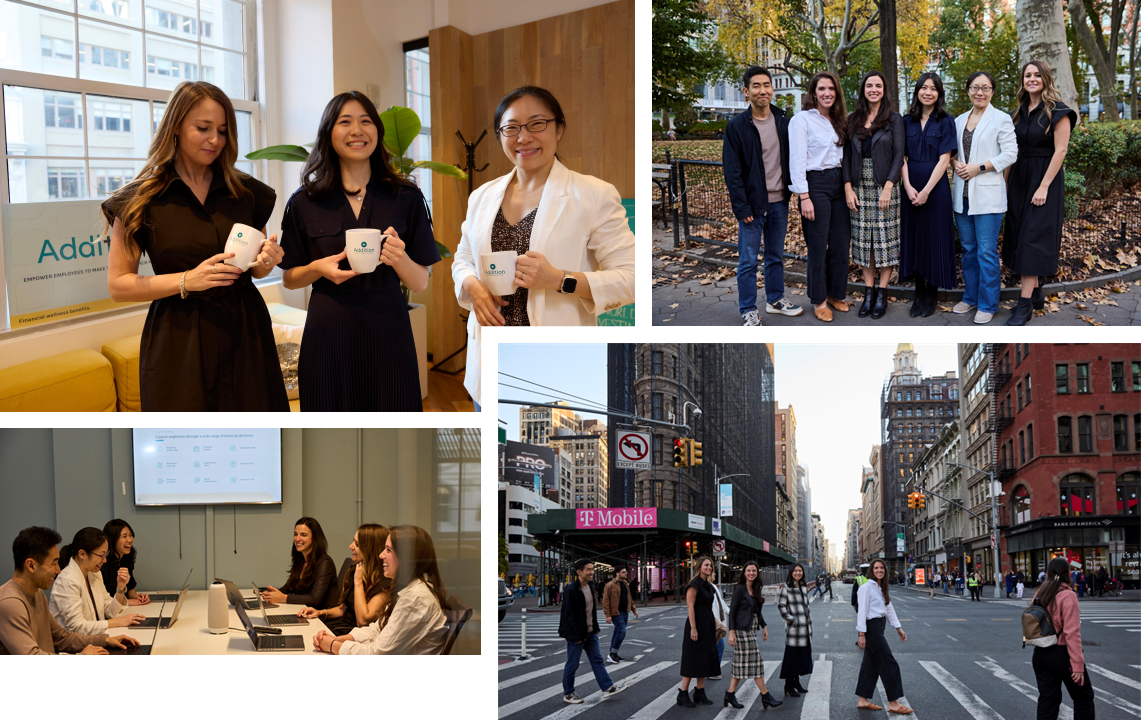
| | Thank you Amy Chou and the Addition Wealth team for sharing your days in the life —building the future of financial guidance, one step at a time…Abbey Road style. | Thank you Amy Chou and the Addition Wealth team for sharing your days in the life —building the future of financial guidance, one step at a time…Abbey Road style. | | |
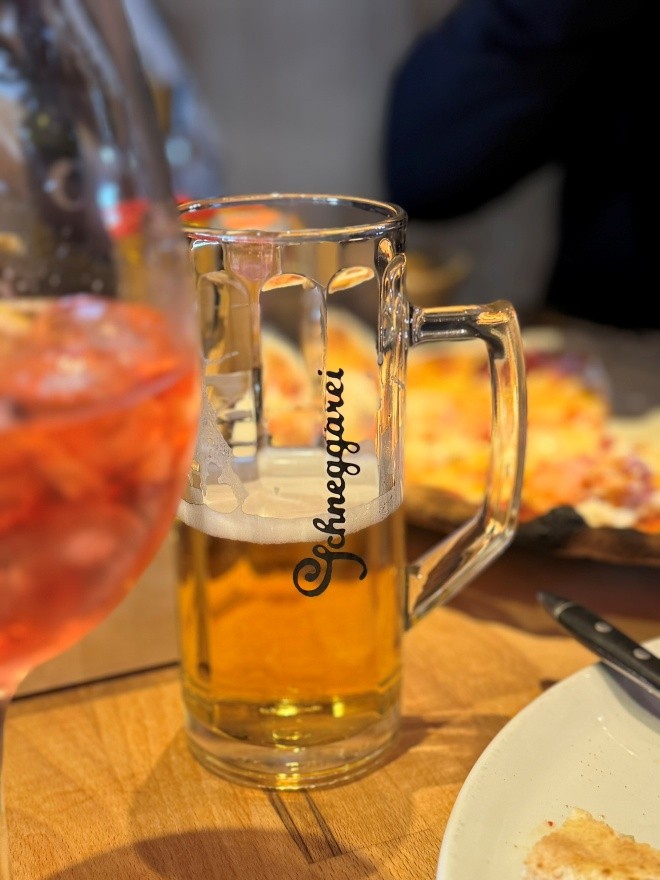
And a little further afield ... ifffff you find yourself in the Arlberg valley in the alpine town of Lech, we hope you’ll be accompanied by your family, and stay at the Hotel Haldenhof.
| | If there is a magical dump of snow lasting more than 24 hours we hope you will go out in it, even if you can’t see to ski. | | You may give your husband plenty to think about … which is all good as long as it ends with a good meal – of pizza and beer. #Tschuss! | | |
That’s it for this edition. ❤ Hug your people and change the world. Special thanks to Melanie Lewis, without whom these 101 editions would not have been possible.
| | |
Massena Associates provides process, policy, and implementation consulting on retirement savings programs and products.
Our clientele includes public entities, policy organizations, and private sector providers. Our specialty – efficient, targeted results. We are an active speaker on retirement security topics, including state-facilitated programs, MEPs and more.
If you’d like to explore working together, we welcome the conversation. Connect with us here, and at 339-236-0684.
| | |
Looking for a great retirement savings innovation resource? The Center for Retirement Research at Boston College develops and hosts terrific content and proprietary research related to states, financial security, social security, and more.
The Defined Contribution Institutional Investment Association (DCIIA) is dedicated to enhancing the retirement security of America’s workers. To do this, DCIIA fosters a dialogue among the leaders of the defined contribution community who are passionate about improving defined contribution outcomes. DCIIA's site provides a range of public and member-specific resources.
The Georgetown Center for Retirement Initiatives, Led by Angela Antonelli, GCRI provides excellent information on state-based and other retirement security innovation and policy.
Pew’s Retirement Savings Project studies the challenges and opportunities for increasing retirement savings and is another great resource - check out the work of John Scott and his terrific team.
If you want a great source of broad-based, consumer-focused retirement news, Jeffrey H. Snyder’s The Morning Pulse is your ticket. You can subscribe here.
| | | | |