|
The State of the States
“The state of the states is strong—and getting stronger every year,” Angela told us.
Today, 20 programs have been adopted, reaching more than 20 million workers without access to an employer plan. Fourteen are already open, with Nevada and New York joining this year and Rhode Island, Minnesota, Hawaii, and Washington lined up next. Partnerships are blossoming too, as states pool resources and infrastructure.
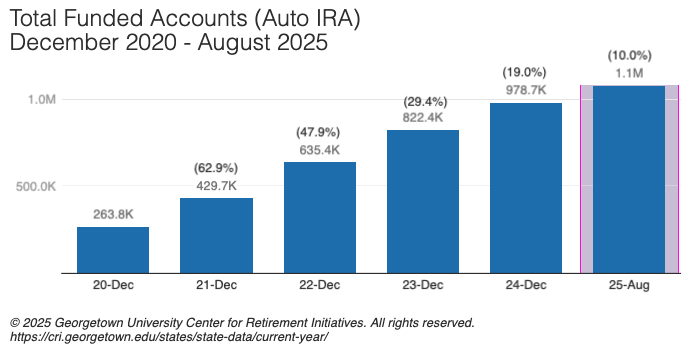
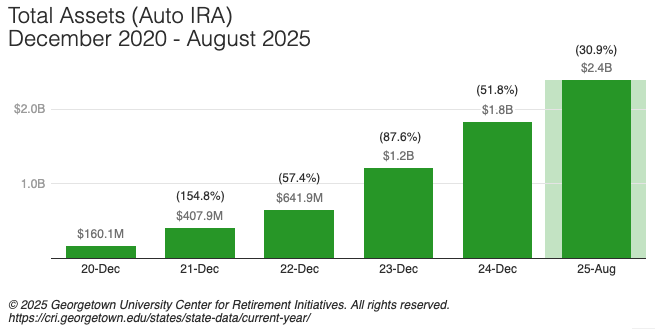
With over $2.4 billion in assets and a million saver accounts, the programs are scaling rapidly and continuing to improve through legislative updates and shared best practices.
The Employer Challenge
So, what’s hardest now? “Reaching employers—especially the smallest ones,” Angela says. Most U.S. firms have fewer than 20 workers, and they’ve always been the hardest to serve.
Finding them, setting up accounts, and supporting payroll deductions is no small feat. But, she added, “these are good challenges. Solving them builds the infrastructure we need so all employers can offer a simple, effective way to save.”
Signs of Progress
Despite the hurdles, results are promising. In states like California, Illinois, and Oregon, tens of thousands of firms have adopted their own plans. Colorado saw a 13% jump in new plan formation after its program launched.
“We’re also seeing positive labor-market effects,” Angela explains. “Retirement benefits matter to workers. They can support employment and retention.” And importantly, Auto IRAs are boosting savings without increasing withdrawals.
New Frontiers: Alternative Assets
CRI is also looking at how money is invested. Private assets are common in DB plans and abroad; the question is whether DC savers should have access too.
“Our research shows modest allocations, especially in target-date funds, can improve outcomes,” Angela said. With disrupted savings paths—caregiving breaks, job changes, early retirements—workers need every prudent tool available. “Private assets can be one of those tools.”
The Saver’s Match
Set to launch in 2027, the Saver’s Match could boost retirement income by 40–50% for millions of low- and moderate-income workers. Auto IRAs will be a key delivery channel, but one operational issue looms: the match must be depositable into Roth accounts.
“There are workable solutions here,” Angela said. “Congress and the Administration should act to make it easy.”
What’s Next
Looking ahead, CRI will continue supporting state programs while expanding research on saver and employer behavior, program benchmarking, and innovation around lifetime income and emergency savings.
“At the end of the day, we have an employer-based system,” Angela reminded us. “If sponsors won’t adopt innovations, they don’t happen. We need to reduce friction and make it practical for them to say yes.”
Angela’s perspective is a reminder of how far state programs have come—and how much possibility remains.
Read the full convo with Angela Antonelli here.
Angela, you’ve shared so much current thinking and practical wisdom. Thank you.
Want to continue the conversation? Reach out to Angela by email, and on LinkedIn.
|