|
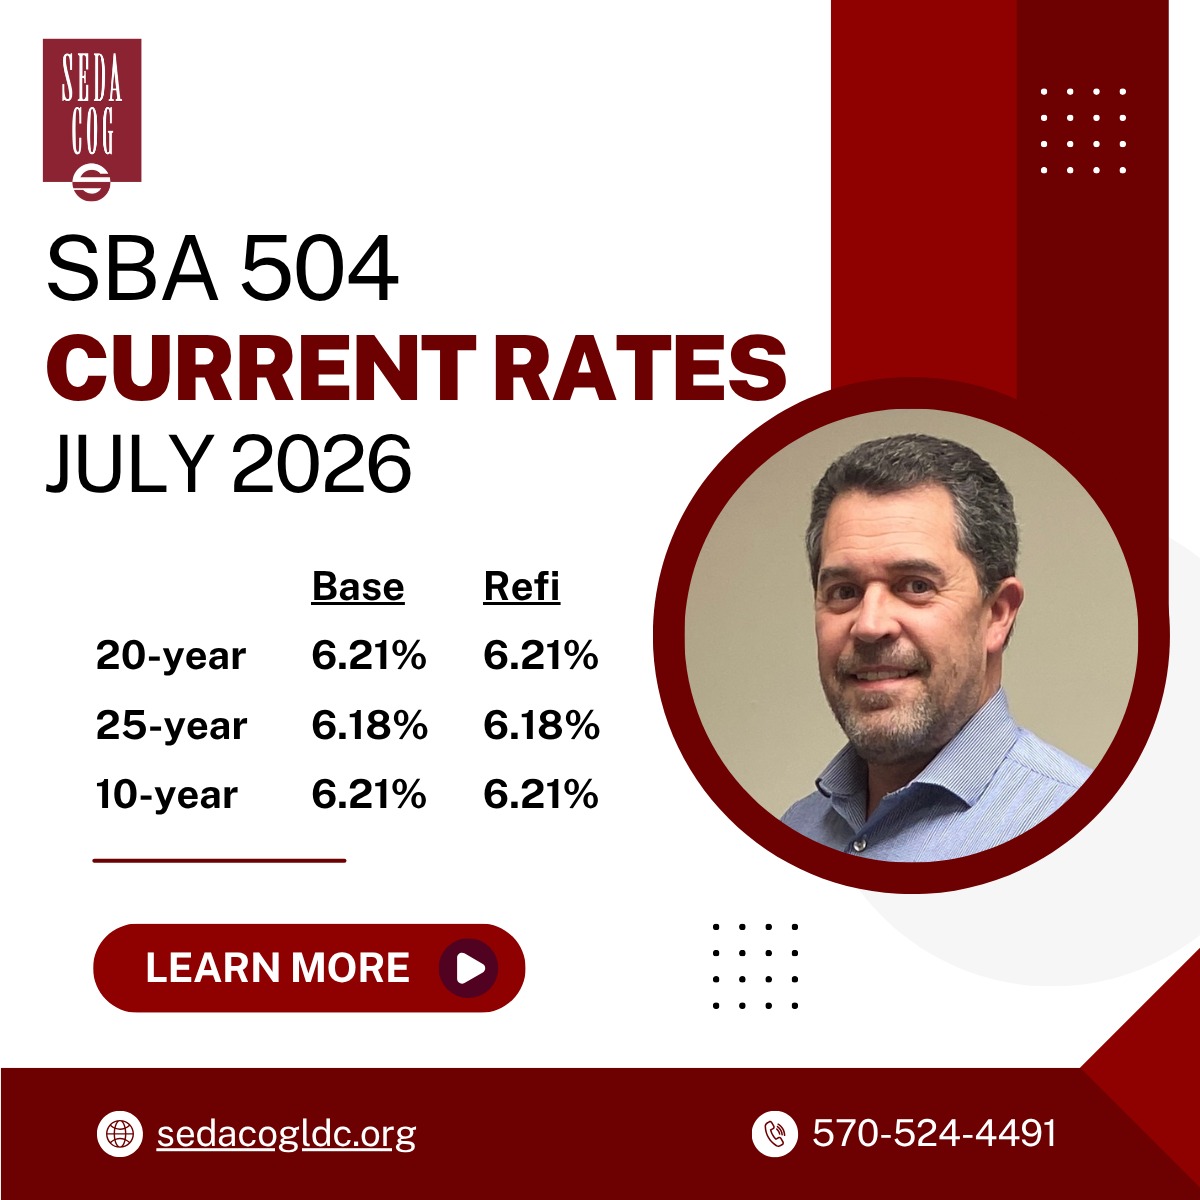
NADCO, the trade association for the nation's Certified Development Companies (CDCs), has released the SBA 504 fixed interest rates for July 2026. Eagle Compliance, the Fiscal Agent for the SBA 504 Loan Program, responsible for the marketing, pricing, and selling of the debentures sold to investors to fund the SBA 504 Loan Program, stated that July saw SBA interest rates rise due to weak job numbers and persistent inflation.
According to Eagle Compliance, a week before the SBA bond sales:
Thud
Friday’s jobs report came in weaker than expected at 57,000, much lower than the May report of 122,000 and the consensus forecast of 117,000, plus the April and May reports were revised lower by 74,000. As disappointing as the report was, it helped to show improvement from the latter part of last year as the first six months of 2026 show an average gain of 92,000 each month vs. an average monthly decline of 8,000 for the last six months of 2025.
The unemployment rate declined to 4.2% as more people left the job market, possibly due to recent immigration policies and baby boomer retirements. The Labor Force Participation Rate (a measure of working-age population either working or looking for work) declined to 61.5% in June, its lowest level since March 2021, with the size of the labor force declining by 720,000 from May to June.
Analysts like to have a reason for any move in the markets, so it was reported that this indication of a recently stagnant job market combined with cooling inflation may encourage the Fed to not raise rates this year. Unfortunately, inflation is not cooling, and 4.2% unemployment is fairly strong, so until lower oil prices translate into reduced energy costs, the Fed will need to be vigilant.
Rates Rise
After rallying the previous week as oil prices declined and hopes for a Middle East settlement seemed more positive, the ten-year benchmark Note’s yield increased to 4.49%, but that level remains 3 bps lower than when the 504 program priced its June debentures. The move higher in the rate began after the ADP private employment report on Wednesday served as a precursor for the next day’s NFP report that disappointed markets, as well as comments from the new Fed chair, Kevin Warsh. When asked at a central banker conference if inflationary pressures demanded a central bank response, he replied, “I’m not going to make a judgement now.” At his initial press conference following the June 17 FOMC meeting, he seemed surprisingly hawkish, but critics remain suspicious and believe he remains committed to a lower interest rate policy to spur productivity. Minutes from that meeting will be released Wednesday and will be closely scrutinized, especially since he abstained from the Committee’s Summary of Economic Projections.
Concerning the next FOMC meeting on July 29, the CME FedWatch tool shows just a 22% chance of a 25 bps rate increase to a range of 3.75%-4%.
Following the bond sales, Eagle Compliance reported:
Summertime Forecast Calling for Elevated Temps & Yields
As we approached the July SBAP sale, credit markets had moved toward, and were perhaps already in, a risk-off state. The recently released June employment report revealed a headline number that was weaker than expected, but overall, it showed significant hiring improvement in 2026 vs. 2025. Many market participants had become convinced the FOMC’s next move had changed from a decrease to an increase in rates, though timing was uncertain. The ceasefire in Iran appeared to be tenuous at best.
Early last week, since our May 10-Year pricing, the 5-Yr. UST yield had risen 26 bps to yield 4.24%, while the 10-Yr. UST yield had decreased 5 bps since the June pricing to yield 4.47%. Month over month, comparable ACMBS new issue and secondary market spreads had widened 2 to 3 bps. The MBS to U.S. Treasury basis had also widened 2 to 3 bps. The UST Curve had mildly flattened once again month over month; however, since the start of the year, this overall flattening trend was quite significant. Additionally, our most recently issued June 20-Year and 25-Year SBAP issues were quoted in the secondary market with a +47 bps bid. As they were initially priced at +45 and +46 bps, respectively, it was inadvisable to consider initial price talk for the July issues at any level less than +47 bps. Collectively speaking, these factors painted a neutral to mildly negative picture, so it was decided that the initial pricing spreads on the July offerings would be +42 bps on the 10-Year SBAP (over the 5-Yr. UST), +47 bps on the 20-Year, and +48 bps on the 25-Year SBAPs (20 and 25-Year over the 10-Yr. UST). Each was 2 bps wider from the last pricing of each issue. The week’s significant expected economic releases were very light (FOMC minutes on Wednesday), and the U.S. Treasury was scheduled to complete its quarterly refunding (3-Year, 10-Year, and 30-Year notes/bonds).
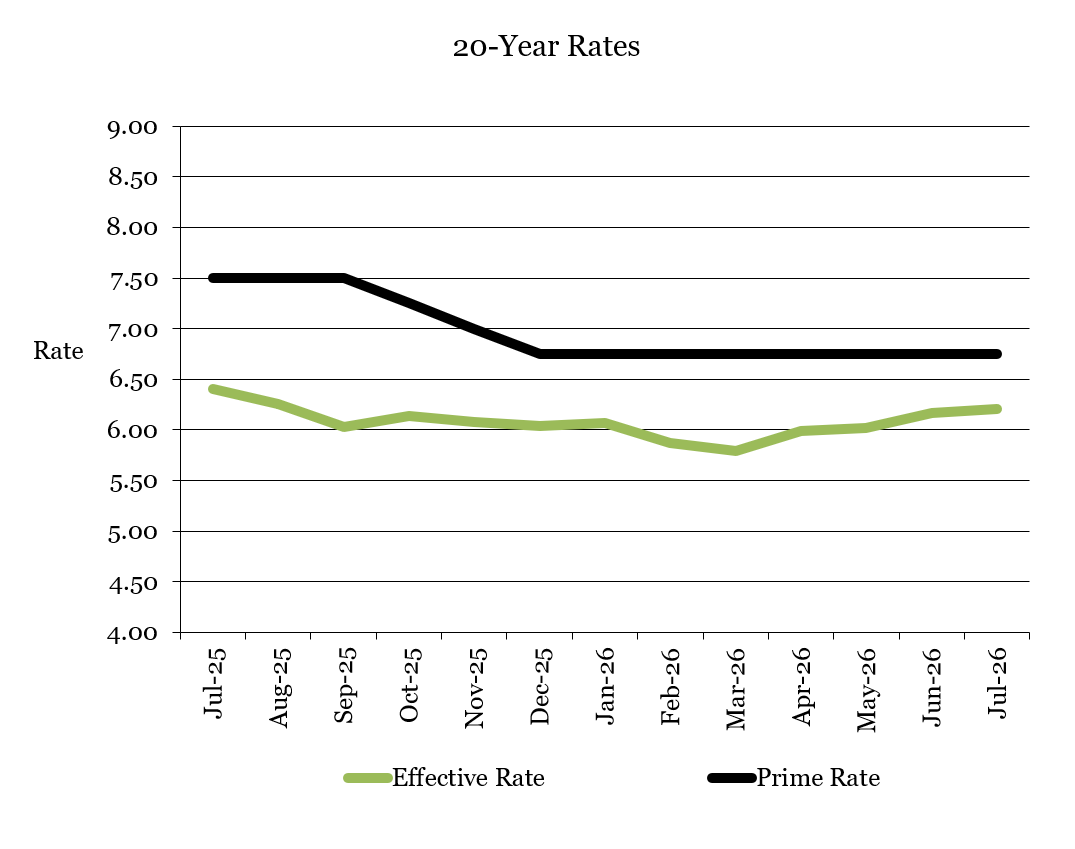
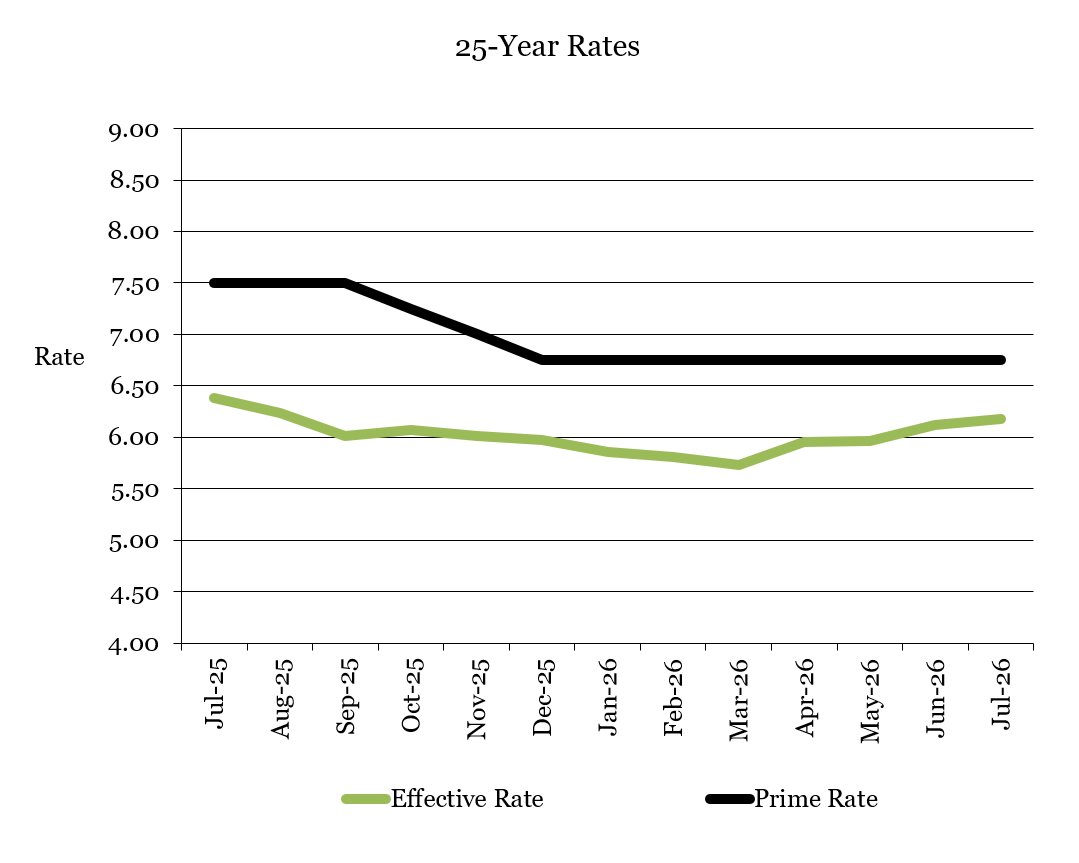
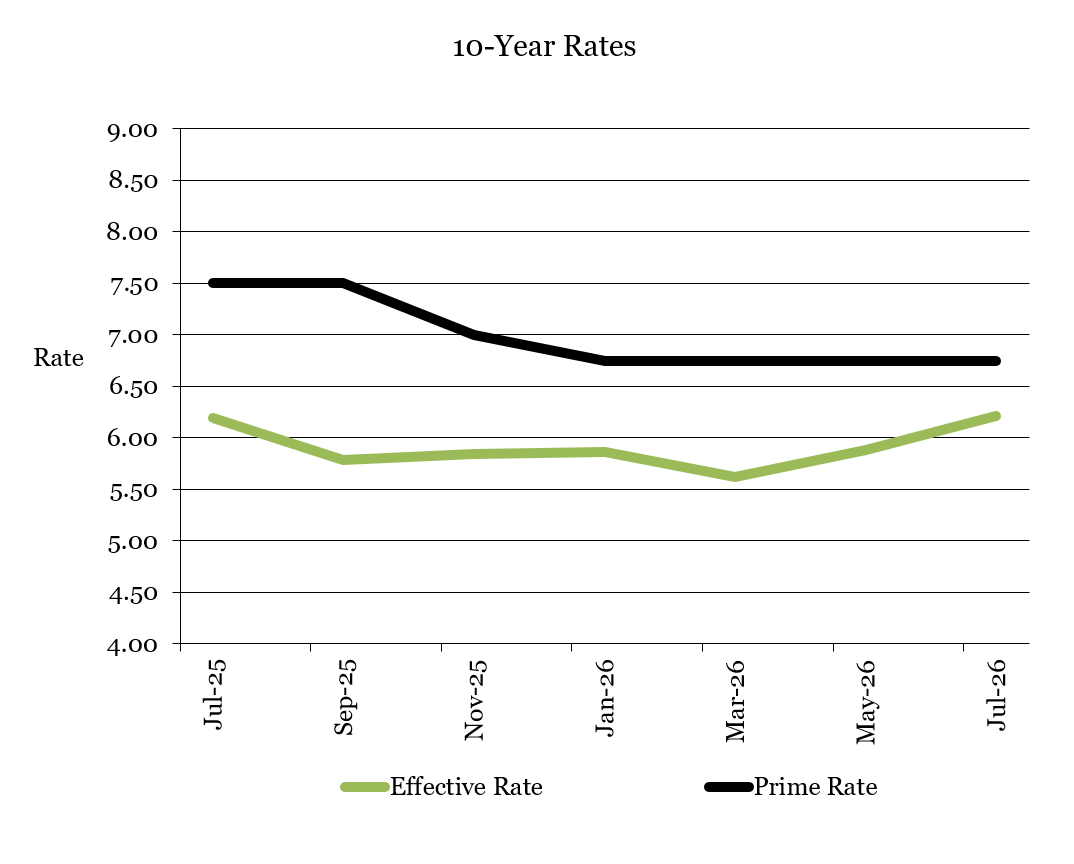
Investor response to the $23.3 million 10-Year, $10.2 million 20-Year was very quick and positive as each underwriter received investor orders significantly greater than the par amount of bonds available. The 25-Year 504 offering took longer to distribute, and although oversold, it was to a lesser degree. It is worth noting that on Announcement Day an investor was offering a block of 2024 SBAP issues for sale in the secondary market. Due to the oversold condition on the 10-Year and 20-Year, it was decided the offering spread on each could be narrowed 2 bps, while the spread on the 25-Year was left unchanged. This was well received by investors. The 10-Year SBAP offering was priced at +40 bps, the 20-Year SBAP at +45 bps, and the 25-Year at +48 bps. The July debenture rate for the 10-Yr. was 4.69%, for the 20-Year it was 5.01%, and for the 25-Year it was 5.04%. The coupon level on the 10-Year issue was 31 bps higher than the prior offering, the 20-Year was 4 bps higher, and the 25-Year was 6 bps higher. The 25-Year rate is 31 bps under the program life average of 5.35%, and the spread over Treasury (+48) was 30 bps below its program life average of T+78.
On Wednesday, the June FOMC meeting minutes showed policy makers were notably divided on the potential evolution of inflation, and by extension, the likely pathway for policy. According to the minutes, some participants saw a potential for price pressures to ease and allow for lower rates, while others anticipated an ongoing elevated inflationary environment warranting higher rates.
_________________________________________________________________
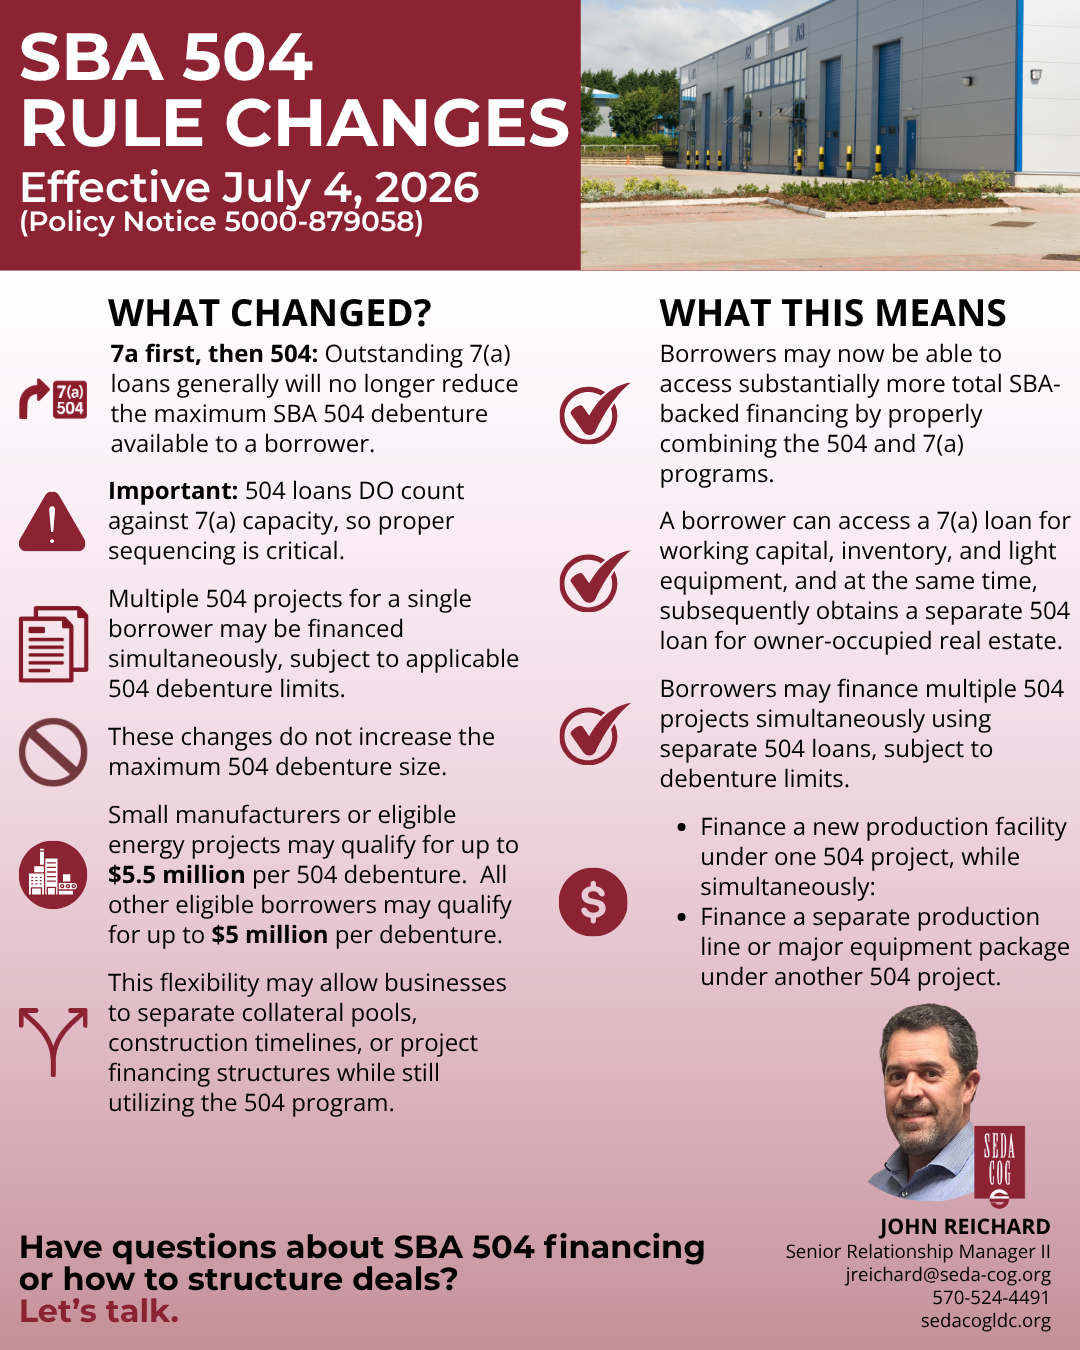
Despite the recent rising rates, SBA 504 loans continue to be very attractive, as it reduces the down payment on commercial real estate projects to as low as 10% and provide a 20 or 25-year fixed rate for up to 40% of the borrower's financing need.
For more information about the SBA 504 loan program, visit sedacogldc.org.
|