|
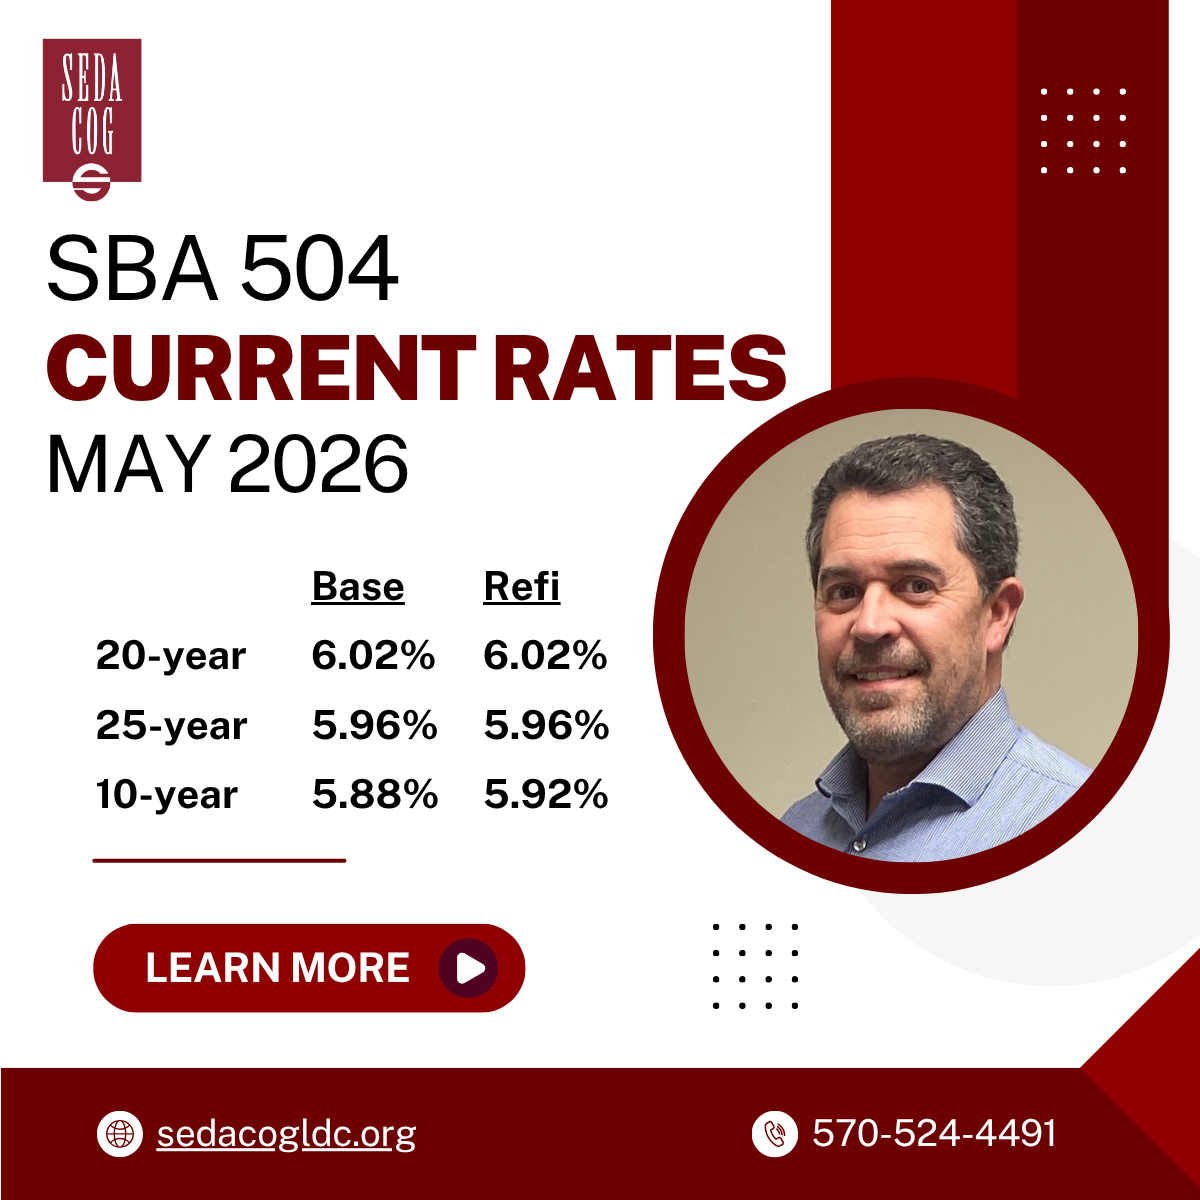
NADCO, the trade association for the nation's Certified Development Companies (CDCs), has released the SBA 504 fixed interest rates for May 2026. Eagle Compliance, the Fiscal Agent for the SBA 504 Loan Program, responsible for the marketing, pricing, and selling of the debentures sold to investors to fund the SBA 504 Loan Program, stated that May saw SBA interest rates inch higher on stable market conditions.
According to Eagle Compliance, a week before the SBA bond sales:
Dissent
In a week filled with significant events, reports, and commentary, one of the most significant is the details surrounding the Fed’s announcement of no policy change that included four dissenters (the most since 1992); three bank presidents who objected to dovish language in the statement and Stephen Miran, who maintained his preference for a 25 bps rate cut. Specifically, the issues that influenced the FOMC announcement and related comments are:
-
The three bank presidents (Lorie Logan, Beth Hammack, and Neel Kashkari) backed the rate decision but objected to retaining the phrase “easing bias” that, for the last two years, has suggested a rate cut is more likely than a rate hike.
-
Soon-to-be-elected Fed Chair Kevin Warsh and Treasury Secretary Scott Bessent both want to change the relationship between the Fed and Treasury, as Mr. Warsh has previously criticized the Fed for exercising powers that are the province of the Treasury Department.
-
Another one of the changes that Mr. Warsh wants to institute is to pull back on public communication by the Committee and to pursue a “new inflation framework” that involves a thinner version of the Personal Consumption Expenditures report that presents a more dovish interpretation of expenses.
- Jerome Powell’s term as Chairman will end on May 15th, and breaking with tradition, he announced he will become the first ex-Chairman in eighty years to remain as a Governor on the Fed Board. He intends to keep a low profile and not challenge Mr. Warsh’s authority, but his presence could be awkward.
While these developments don’t signal an imminent rate hike, they do indicate a serious shift in sentiment from an easing bias to a more neutral view as the Committee weighs the impact of higher oil prices on a resilient economy with an inflation rate almost 1% above target. A significant challenge for the Committee are events like war, a naval blockade, and a price surge are supply shocks that monetary policy is not designed to fix, especially at a time when central bank leadership is changing.
Reports
-
1Q2026 GDP improved to 2% from 0.5% as federal government spending rose 9.3% in the quarter, reversing its shutdown-affected (-16.6%) pace in the previous quarter.
-
Personal Income rose to 0.6% from -0.1%.
-
The Conference Board’s Consumer Confidence report improved to 92.8.
-
Core PCE, the Fed’s current preferred inflation gauge, rose to 0.3% and 3.2% y/y.
-
Jobless Claims unexpectedly declined to 189,000.
- The United Arab Emirates announced its withdrawal from OPEC to pursue independent energy policies and maximize production.
Markets
Oil prices rose for the second consecutive week while domestic equity indexes continue to defy the global conflict, and interest rates drifted higher with US debt reaching 100.2% of GDP. As we approach the May debenture sales for the SBA 504 program, the benchmark ten-year Note is at 4.38%, 7 bps higher than at the April sale.
At week’s end, President Trump was considering the latest Iranian peace proposal while also considering new strikes as the conflict entered its third month.
Following the bond sales, Eagle Compliance reported:
May SBAP Pricing, Positive Employment News, Equity Market Rise!
As we approached the May SBAP sale, market conditions were stable. The FOMC had met the week prior, left rates unchanged, and retained their easing bias; however, there were a significant number of dissenting votes. Subsequent to the meeting, Fed Presidents Neel Kashkari (Minneapolis) and Beth Hammack (Cleveland) each released statements clarifying their dissenting votes. Kashkari noted that he believes the Committee should “offer a policy outlook that signals that the next rate change could be either a cut or hike, depending on how the economy evolves.” Hammack said, “Uncertainty around the economic outlook has increased in 2026 and makes the future path for monetary policy more uncertain, as well. I see this clear easing bias as no longer appropriate given the outlook.” As recently as early March, market participants anticipated at least 2 eases by the FOMC in 2026; at present, no additional action is expected this year.
Early last week, since the March SBAP 10-Year pricing, 5-Year UST yields had risen 29 bps to yield 4.01% and the 10-Year UST yield had risen 7 bps since the April SBAP 20 and 25-Year pricings to yield 4.38%. Month over month, comparable ACMBS new issue and secondary market spreads were little changed. The MBS to U.S. Treasury basis had narrowed 14 bps month over month, and the FreddieMac 30-Year mortgage rate had risen 8 bps over the same period. The 2/10s, 5/10s, and 7/10s portions of the UST Curve were essentially unchanged at 50 bps, 37 bps, and 19 bps, respectively. Finally, the MOVE index had fallen slightly to 72.1. Collectively speaking, these factors painted a rather neutral picture; it was therefore decided that the suggested initial pricing spreads on the May offerings would be +40 bps on the 10-Year SBAP (over the 5-Year UST), +48 bps on the 20-Year, and +50 bps on the 25-Year SBAPs (both over the 10-Year UST). Each is unchanged from the last pricing of each issue. The week’s expected economic releases and U.S. Treasury auctions were expected to be very light, with the Employment report being released on Friday (post-SBA pricing).
Investor response to the $6.2 million 10-Year, $13.2 million 20-Year, and $490.7 million 25-Year 504 offerings was positive at the initial pricing spreads; within hours of announcement, the underwriters had received investor interest meaningfully greater than the par amount of each issue. It was therefore decided that the offering spread on the 25-Year could be narrowed 2 bps. This change in spread was well received by investors as the underwriter's books remained unchanged and reflected widespread distribution. The 10-Year SBAP offering was priced at +40 bps, and both the 20-Year SBAP offering and 25-Year SBAP offering were priced at +48 bps. The May debenture rate for the 10-Yr. was 4.38%, for the 20-Year and 25-Year it was 4.82%. The coupon level on the 10-Year issue was 26 bps higher than the prior offering, while the 20-Year and 25-Year coupons were each 1 bp more than their prior offering. The 25-Year rate is 54 bps under the program life average of 5.36%, and the spread over Treasury (+48) was 30 bps below its program life average of T+78.
On Friday, the nonfarm payrolls report revealed an increase of 115k in April, well surpassing the 65k rise expected, and marking the first back-to-back months of positive job creation since May of last year. The unemployment rate held steady at 4.3% in April for the second consecutive month, as expected. This increase in job creation reinforces the domestic economy’s relative position of strength to weather ongoing challenging conditions. The pickup in hiring momentum will further shift the FOMC’s focus to still-elevated inflation. The news was well received by the equity markets as the DJIA, S&P 500, and NASDAQ all ended the week near all-time highs.
Next week will be a rather busy week from both an economic and Treasury auction perspective. April’s CPI will be released on Tuesday, and Wednesday brings April’s PPI; clearly, very important inflation gauges for all market participants and the FOMC. The U.S. Treasury will conduct its quarterly refunding this week with the auction of 3, 10, and 30-year notes/bonds.
_______________________________________________________________________________
As SBA 504 rates continue to be very attractive, it is a great time to take advantage of the SBA 504 loan program, as it reduces the down payment on commercial real estate projects to as low as 10% and provides a 20 or 25-year fixed rate for up to 40% of the borrower's financing need.
For more information about the SBA 504 loan program, visit sedacogldc.org.
|