Not displaying correctly? View the web version of this newsletter. 

September 1, 2023  |  CBIAONLINE.ORG  |  SUBMIT NEWS  |  2023 EVENTS  |  CONTACT

Advocacy  |  Education  |  CONVENTION  |  Foundation |  Leaders of Tomorrow |  Services

CBI Endorsed Member ICBA Securities and its exclusively endorsed broker-dealer Stifel opened registration for the 2023 Balance Sheet Academy.


Scheduled for Oct. 16-17 in Memphis, the live event will focus on managing balance sheets, liquidity and capital, loan and investment portfolios, and more.1 |1 View Agenda.


|1 Register here.

LESS THAN 2 WEEKS! REGISTRATION IS OPEN

CBI Member Article:

Remember the Munis

Don’t go to sleep on a profitable bond sector


by Jim Reber - ICBA Securities


“As you get older, three things happen: the memory goes, and I forget the other two” —Erma Bombeck


Being one who can empathize with the late, great humorist Ms. Bombeck, I thought it might be interesting to discuss a segment of the fixed income universe that has served community banking well over the decades. It’s been many months since I’ve covered it, for two practical reasons. The first is that it doesn’t present relative value in the current cycle, and the second is that, because of the first, portfolio managers haven’t been buying many of them recently.


I’m speaking of the municipal bond market. It is a maxim of community banking that the more munis a bank owns, the higher performing the portfolio will be. This has been true for decades and in whatever part of the rate cycle we’re currently residing. But since we haven’t visited muni-land for a while, now is a perfect time for a sector update, complete with reminders about nuances and opportunities with state and local government bonds.


Value measures

Tell me if you’ve heard this: The interest rate curve is inverted. It’s now been 16 months and counting since we’ve had a positively sloped curve and that includes the muni sector. A buyer has to invest in a 12-year or longer muni to get a higher yield than a 1-year bond.


Also, the retail sector continues to gobble up the majority of supply, which is barely running in place. A number of governmental borrowers in 2023 have delayed issuance, probably hoping for some relief on rates.


Mom-and-pop investors will typically have higher marginal tax brackets than corporations, and that translates into higher tax-equivalent yields—hence the retail demand. The current impact is such that on the short end of the curve (i.e., 10 years and in), munis produce lower tax-equivalent yields than comparable maturity treasuries. In bond-speak this is known as “trading through the curve.” Although this is an anomaly, it has persisted for most of 2023. Hence, the relative value, or lack thereof.


Still the favorite

Notwithstanding the preceding paragraph, a hallmark of a high-performing bond portfolio remains a high allocation of munis, although that’s changing some. According to Stifel, top-quartile portfolios had 31% of their dollars in munis in June 2023, compared to 42% a year earlier. Interestingly, the top quartile also had a dramatic drop in its effective duration year-over-year from 5.3 years to 4.2. The shape of the curve again has played a role, as the dollars reallocated out of the munis space went into short-duration taxables such as treasuries, agencies and Small Business Administration (SBA) floaters.


|1 Keep reading....1 |

CBI Office Closed for Labor Day


The Community Bankers of Iowa office will be CLOSED on Monday, Sept. 4 for the Labor Day holiday. It will re-open Tuesday, Sept. 5.


The CBI Staff and Board of Directors wish you all a safe holiday weekend!


Dickinson Law's 2023 Banking Law Seminar Next Week


Join CBI Affiliate Member Dickinson Law on September 7 at the Hilton Rewind Hotel in West Des Moines for their 2023 Banking Law Seminar. Here they will Navigate the Future of Banking by focusing on the emerging issues in the banking industry. The full seminar runs from 8:30 am-3:30 pm.


View the complete agenda here. Seats are limited, so register today. Contact Sarah Ruba at 515-246-4508 or sruba@dickinsonlaw.com with questions.


| 1REGISTER NOW 1|

Webinar: Today's Loan Review for Today's Loan Risk


Loan review is a vital part of early detection—and can lead to fewer credit losses. Heightened credit stress due to higher inflation and interest rates has examiners placing even more emphasis on credit risk, plus the safety and soundness of lending programs.


In this webinar to be held Wednesday, September 6 at 10:00 am CT, David Ruffin, principal of CBI Endorsed Member QwickRate's IntelliCredit will discuss how loan reviews play a big role in managing credit risk and share new approaches your institution can take to identify portfolio risk earlier. Register now.


SBA Announces 7(a) Fees Effective October 1, 2023 for Fiscal Year 2024


SBA issued Information Notice 5000-848801 announcing the 7(a) Lender’s Annual Service Fee (also known as the “Lender’s Annual Service Fee”) and the SBA Guaranty Fee (also known as the Upfront Fee) for 7(a) loans for fiscal year 2024 (FY 2024), and the exceptions to those fees authorized for FY 2024 for the 7(a) loan program.


The following fees are effective for all 7(a) loans approved on October 1, 2023, through and including September 30, 2024. For guidance on when all 7(a) loan fees are due, see SOP 50 10 7, Section A, Chapter 4, Para. C. All loan amounts are based on the gross loan approval amount, including the SBA-guaranteed and unguaranteed portions.


SBA Guaranty Fee (Upfront Fee):

Except for Export Working Capital Program (EWCP) loans and SBA Express loans made to veteran-owned businesses, the FY 2024 Upfront Fee, based on gross loan approval amount, including SBA-guaranteed and unguaranteed portions, will be:


For loans with a maturity that exceeds 12 months, the Upfront Fees are:

1 • 1For loans of $1,000,000 or less: 0.00%. 


1 • 1For loans of $1,000,001 to $2,000,000:

1 • 11.45% of the guaranteed portion of the loan

1 • 1up to and including $1,000,000, plus 1.70%

1 • 1of the guaranteed portion of the loan over

1 • 1$1,000,000. 


1 • 1For loans $2,000,001 and greater: 3.50% of

1 • 1the guaranteed portion of the loan up to

1 • 1and including $1,000,000, plus 3.75% of

1 • 1the guaranteed portion of the loan over

1 • 1$1,000,000. 


For 7(a) loans with a maturity of 12 months or less (Short-term loans):

1 • 1For loans of $1,000,000 or less: 0.00%. 


1 • 1For loans $1,000,001 and greater: 0.25% of

1 • 1the guaranteed portion. 


|1 Keep reading....1 |

FDIC updates EHL posters


In April, the FDIC issued a Federal Register notice to update and clarify the requirements for Equal Housing Lender posters that are required to be displayed in FDIC-supervised institutions. These changes were necessitated by a name change of the FDIC’s entity that receives complaints and the introduction of the web address of the FDIC’s web-based complaint portal. The effective date for these changes was June 23, 2023.


Financial institutions are reminded that the NCDA’s address to physically mail complaints will be maintained at FDIC.gov, and EHL posters should reflect the correct address. FDIC-supervised banks may, but are not required to, obtain posters from the FDIC Online Catalog. Institutions may also wish to create their own posters or use third-party providers. Institutions are expected to make good-faith efforts to update the EHL posters as soon as reasonably practicable.


To request copies of the EHL posters from the FDIC, financial institutions must be registered users of the FDICconnect (FCX) system and provisioned for the FDIC Online Catalog.

Labor Department proposes revised overtime rules


The U.S. Department of Labor has announced a notice of proposed rulemaking that would restore and extend overtime protections to 3.6 million salaried workers. The proposed rule would guarantee overtime pay for most salaried workers earning less than $1,059 per week, about $55,000 per year.


The NPRM proposes to update and revise the regulations issued under section 13(a)(1) of the Fair Labor Standards Act implementing the exemption from minimum wage and overtime pay requirements for executive, administrative, and professional employees. Proposed revisions include increasing the standard salary level and the highly compensated employee total annual compensation threshold, as well as providing an automatic updating mechanism that would allow for the timely and efficient updating of all the thresholds to reflect current earnings data.


Comments on the proposal will be accepted for 60 days following Federal Register publication.


|1 Notice of Proposed Rulemaking: Defining and Delimiting the Exemptions for Executive, Administrative, Professional, Outside Sales, and Computer Employees


|1 Frequently Asked Questions About the Proposed Rule

DHS proposing temporary REAL ID waivers for mobile state IDs


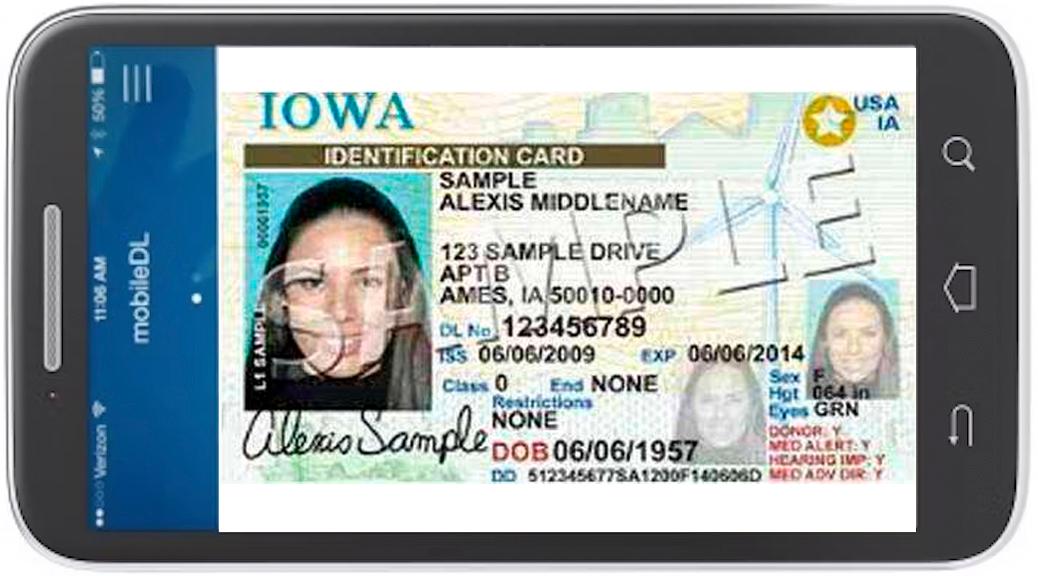
The Dept. of Homeland Security has published in the Federal Register [88 FR 60056] a proposal that would amend the REAL ID regulations to waive, on a temporary and state-by-state basis, the regulatory requirement that mobile or digital driver’s licenses or identification cards (“mobile driver’s licenses” or “mDLs”) must be compliant with REAL ID requirements to be accepted by Federal agencies for official purposes, as defined by the REAL ID Act, when full enforcement of the REAL ID Act and regulations begins on May 7, 2025.


This proposed rule is part of an incremental rulemaking that would temporarily permit Federal agencies to accept mDLs for official purposes until TSA issues a subsequent rule that would set comprehensive requirements for mDLs. TSA believes it is premature to issue such requirements before the May 7, 2025, deadline due to the need for emerging industry standards and government guidelines to be finalized.


Comments on the proposal will be accepted through October 16, 2023.

FS-ISAC Weekly Risk Summary:

August 21, 2023


CBI Member CSI: How to Mitigate Cybersecurity Risk with Penetration Testing

How community banks can combat the rise of check fraud


CFPB settles with credit repair group for $2.7 Billion

Q. If a customer calls and asks about our current deposit rates do we need to include a statement of “annual percentage yield” along with the rate?


A. In any oral response to a consumer inquiry on deposit rates, Regulation DD requires that you state the annual percentage yield. The interest rate may be stated in addition to the annual percentage yield as set out here:


"(e) Oral response to inquiries. In an oral response to a consumer's inquiry about interest rates payable on its accounts, the depository institution shall state the annual percentage yield. The interest rate may be stated in addition to the annual percentage yield. No other rate may be stated." 


Regulation DD § 1030.3(e)

AROUND IOWA

USDA Invests $16.3 Million to Strengthen Infrastructure and Create Jobs in Rural Iowa


State grain fees will resume this week


Cedar Rapids, Marion, Hiawatha, Economic Alliance launch workforce recruitment campaign

OPERATIONS/MARKETING

How to Turn Your Execs into Expert Media Spokespeople


Zillennials: The Millennial & Gen Z Mash-Up with Unique Financial Needs


The Hybrid Workplace is One Huge Work-In-Process for Banks

LENDING / INVESTMENTS

CBI Member UMB: Developing meaningful loan portfolio stress tests


After 25 years, women’s investing club finishes profitable run


CBI Member Compliance Alliance: RESPA Section 8: Back in the News

DIRECTORS

Discretion in Incentive Plans: Taboo or a Must?


Banking Supervision in the Aftermath of Recent Bank Failures


Reviewing Recent Bank Guidance on Third-Party Risk

AGRIBUSINESS

Annual lease termination: Standard practice or unnecessary risk?


Ag Economists Turn More Bullish On Soybean Prices, Corn Prices Are a Big Red Flag

TECH & PAYMENTS

PODCAST: How to Budget for Innovation


Swift reports successful blockchain experiments


FDIC hosting forum on account access innovations


STAY CONNECTED:

Facebook  LinkedIn  Twitter  Web

CBI attempts to publish as many different viewpoints as possible to provide you with information on what is being said and read in the banking industry. CBI does not necessarily endorse or support the opinions given in these third-party news sources. Send news from your bank or company to CBI by contacting Krissy Lee, Communications Director at klee@cbiaonline.org. ©2023 Community Bankers of Iowa. You are receiving this message because you are a listed recipient of Community Bankers of Iowa's communications.