|
Stubborn Inflation Keeps the Fed Cautious
Greetings!
The Federal Reserve left its benchmark rate unchanged this week, which was widely expected. The more important question is why—and what that means for anyone watching mortgage rates or home values.
Inflation is moving further above the Fed’s 2% target, adding to the challenge facing policymakers. The Fed’s preferred inflation measure, the Personal Consumption Expenditures (PCE) Price Index, rose 0.5% in September and 3.6% from a year earlier. Core PCE, which strips out food and energy, rose 0.3% for the month and 3.1% annually.
Fed Chair Kevin Warsh said the committee wants more time to assess incoming data before deciding what comes next. While the Fed does not set mortgage rates directly, its decisions can influence borrowing costs and investor expectations.
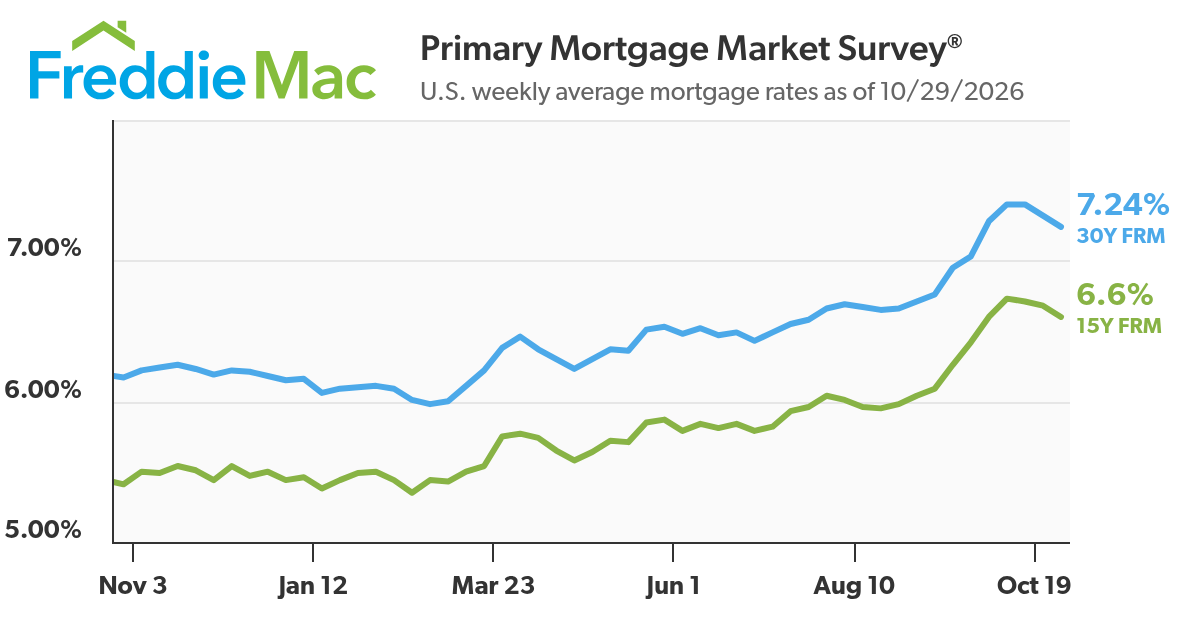
Mortgage Bankers Association Chief Economist Mike Fratantoni expects mortgage rates to ease from their recent highs, but cautioned, “I don’t think they’re going to come down that far.” MBA’s October forecast puts 30-year mortgage rates above 7% through 2027. Still, housing markets and interest rates move through changing conditions, and even the best-informed forecasts can change. Actual rates could end up higher or lower than MBA expects.
Inflation Takes a Bite Out of Home Gains
Borrowing costs are only part of the picture for homeowners. Inflation also affects how much a home’s increase in value is really worth. The latest S&P Cotality Case-Shiller Index showed home prices up 2.1% from a year earlier in August. But when inflation is running faster than home prices, the real increase in value can disappear.
For example, consider a home worth $1.2 million. A 2.1% increase would add $25,200, bringing its value to $1,225,200. If inflation were 3.6% over the same period, the home would need to be worth $1,243,200 just to keep pace—$18,000 more. So, while the homeowner gained value on paper, the home’s value still fell behind inflation.
Cotality Principal Economist Thomas Malone noted that, after adjusting for inflation, home prices have been mostly flat since 2022. Sales turnover also remains unusually low as many homeowners hold onto low mortgage rates and substantial equity rather than move into a more expensive loan. That helps explain the strange housing market we are still living with: prices remain relatively firm even though sales are weak, while buyers continue to wrestle with high borrowing costs.
For buyers and sellers, the takeaway is that headline numbers do not tell the whole story. Mortgage rates may remain elevated until inflation cools further, and modest home-price gains may feel less impressive after adjusting for inflation. We’re here to help you understand what those trends could mean for your plans to buy, sell, refinance, or simply decide whether now is the right time to make a move.
|