The Capital Stack

April 2, 2026 | BWE Arizona | Putting clients first. Trusted to be part of their future.


Outlier Pricing

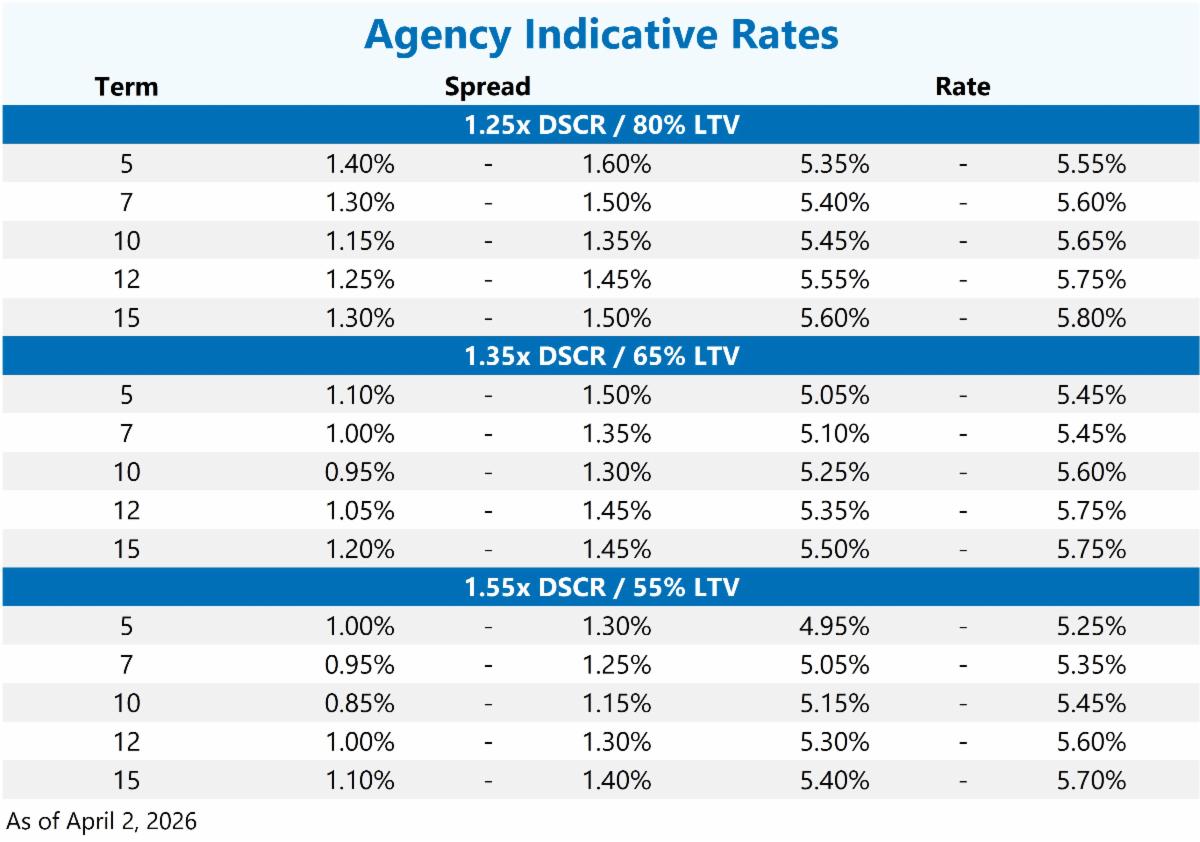
Agency

Life Company

5.15%

0.85% + 10yr UST

Low leverage multifamily refinance

5.50%

1.20% + 10yr UST

Low leverage multifamily refinance


Market Commentary

Key takeaways

  • Risk shift underway: Inflation-only concern; inflation + growth slowdown dual risk
  • Borrower behavior turning defensive: Accelerated rate locks suggest fear of worsening conditions
  • Agency CMBS remains a relative winner: Stable spreads + strong demand vs. corporates
  • Policy uncertainty remains elevated: Fed likely on hold unless labor materially weakens


Macro and geopolitical backdrop

  • Middle East tensions (Iran conflict) are the dominant market driver
  • ~20% of global oil supply at risk via Strait of Hormuz disruption
  • Brent crude at ~$113/barrel — highest since mid-2022
  • Inflation risk re-emerging through energy channel
  • Simultaneously, markets are beginning to price growth downside risk


Labor market

  • Heavy labor data calendar culminating in nonfarm payrolls (Friday)
  • Expectations:
  • Payrolls: +60K rebound (from -92K prior)
  • Unemployment rate: Stable at 4.4%
  • Key interpretation:
  • Labor market is slowing, but not deteriorating sharply
  • Fed and markets are increasingly concerned about downside employment risks


Rates and monetary policy

  • Treasury yields modestly lower (↓ ~5-8 bps) but still significantly higher vs. late February (~+40 bps move prior)
  • Market positioning:
  • Flat Fed Funds path remains base case
  • ~10% probability of a rate cut by year-end (slightly more dovish)
  • Key tension: Inflation risk (oil + tariffs) vs. growth slowdown risk
  • Overall: Markets lack conviction → “placeholder” macro assumptions dominate


Consumer and economic outlook

  • Increasing pressure on consumers from:
  • Higher gasoline prices
  • Tariff pass-through costs
  • Slowing job growth
  • Risk scenario forming:
  • Stagflation-lite environment
  • Slower growth + elevated short-term inflation


Lending and origination activity

  • Strong surge in rate lock activity (~$2B Fannie DUS/MBS)
  • Driven by:
  • Quarter-end dynamics
  • Borrowers locking ahead of potential spread/rate deterioration
  • Concentration: ~$1.15B from just four large transactions
  • Interpretation:
  • Borrower fatigue + defensive behavior
  • “Take the deal now” mindset emerging


Market tone and positioning

  • Markets are:
  • Highly reactive to geopolitical headlines
  • Lacking clear directional conviction
  • Current “base case” thinking:
  • Slow but stable labor market
  • Temporary inflation bump from energy + tariffs
  • However confidence in this base case is fragile 
 

Agency

Weekly Fannie Mae DUS/MBS rate lock volumes jumped to approximately $2 billion amid heightened market volatility, with Agency CMBS borrowers securing financing on their loans before quarter-end. The week marked the highest level of activity for new issue DUS locks this year, with approximately $1.15 billion attributed to four large block transactions. Fannie Mae DUS/MBS investor spreads drifted slightly wider over the week, though held in well relative to other investment-grade assets.


Freddie Mac was active last week as well, with the sale of $750 million of Participation Certificates and a $1.3 billion K-178 10-yr K-loan week that was priced slightly softer than preliminary guidance.


Ginnie Mae's new issue activity continued to be light heading into quarter-end, as its corresponding spreads held steady. In the broader investment-grade (IG) debt market, despite March issuance is on track to be the second busiest on record. Bloomberg reported Thursday that stresses from private credit's concentrated exposure to the software sector, which has been vulnerable to AI disruption, along with renewed inflation pressure from the Iran war, are starting to bleed into IG credit markets.


Some syndicate desks were advising corporate borrowers to wait another week as credit conditions deteriorated further last week. Bloomberg’s Single-A Industrials 10-yr and CDX IG 5-yr Indices were wider by 3-5 basis points by the end of the week. Despite marginal widening these past few weeks, Agency CMBS spreads have held up better than other fixed-income products such as single-family MBS. The outperformance reflects Agency CMBS's prepayment protection, which gives investors more predictable cash flow through yield maintenance provisions that discourage early prepayments, unlike residential mortgages.


Agency 5-year loans remain in favor

  • Over 50% of agency loan volume has originated through 5-year terms. Investors in Agency loans remain most interested in 10-year terms as there has been a flight to safety provided by the Agency secondary investment market during the volatility resulting from the Iran conflict.


Dynamic” nature of Fannie pricing

  • Historically, affordability was the primary driver to pricing reductions with Fannie Mae.
  • Fannie remains focused on winning business, but less focused on affordability.
  • For borrowers, this means…
  • Reductions from the top of the pricing grid could change week to week,
  • Varying reductions between leverage tiers, and
  • Daily communications with Fannie Mae to identify the best quote scenario week to week.


Loan highlights


Fannie Mae Near Stabilization/Construction Take Out – Davenport, FL

  • $60.5 million
  • 65% LTV
  • 135 bps spread with 1% buydown
  • 7-yr term / FTIO


Freddie Mac Floating Rate – Boston, MA

  • $34.8 million
  • 65% LTV
  • 129 bps spread
  • 5-yr floating / 2 yrs IO
 

Life Company

The recent increase in the U.S. Treasuries has slowed Life Company activity over the past couple weeks partly due to market expectations that the Federal Reserve will keep interest rates higher for longer and rising concerns over geopolitical tensions. This uncertainty has led to borrowers delaying the start of the refinancing process, and not wanting to rate lock at the top of market.


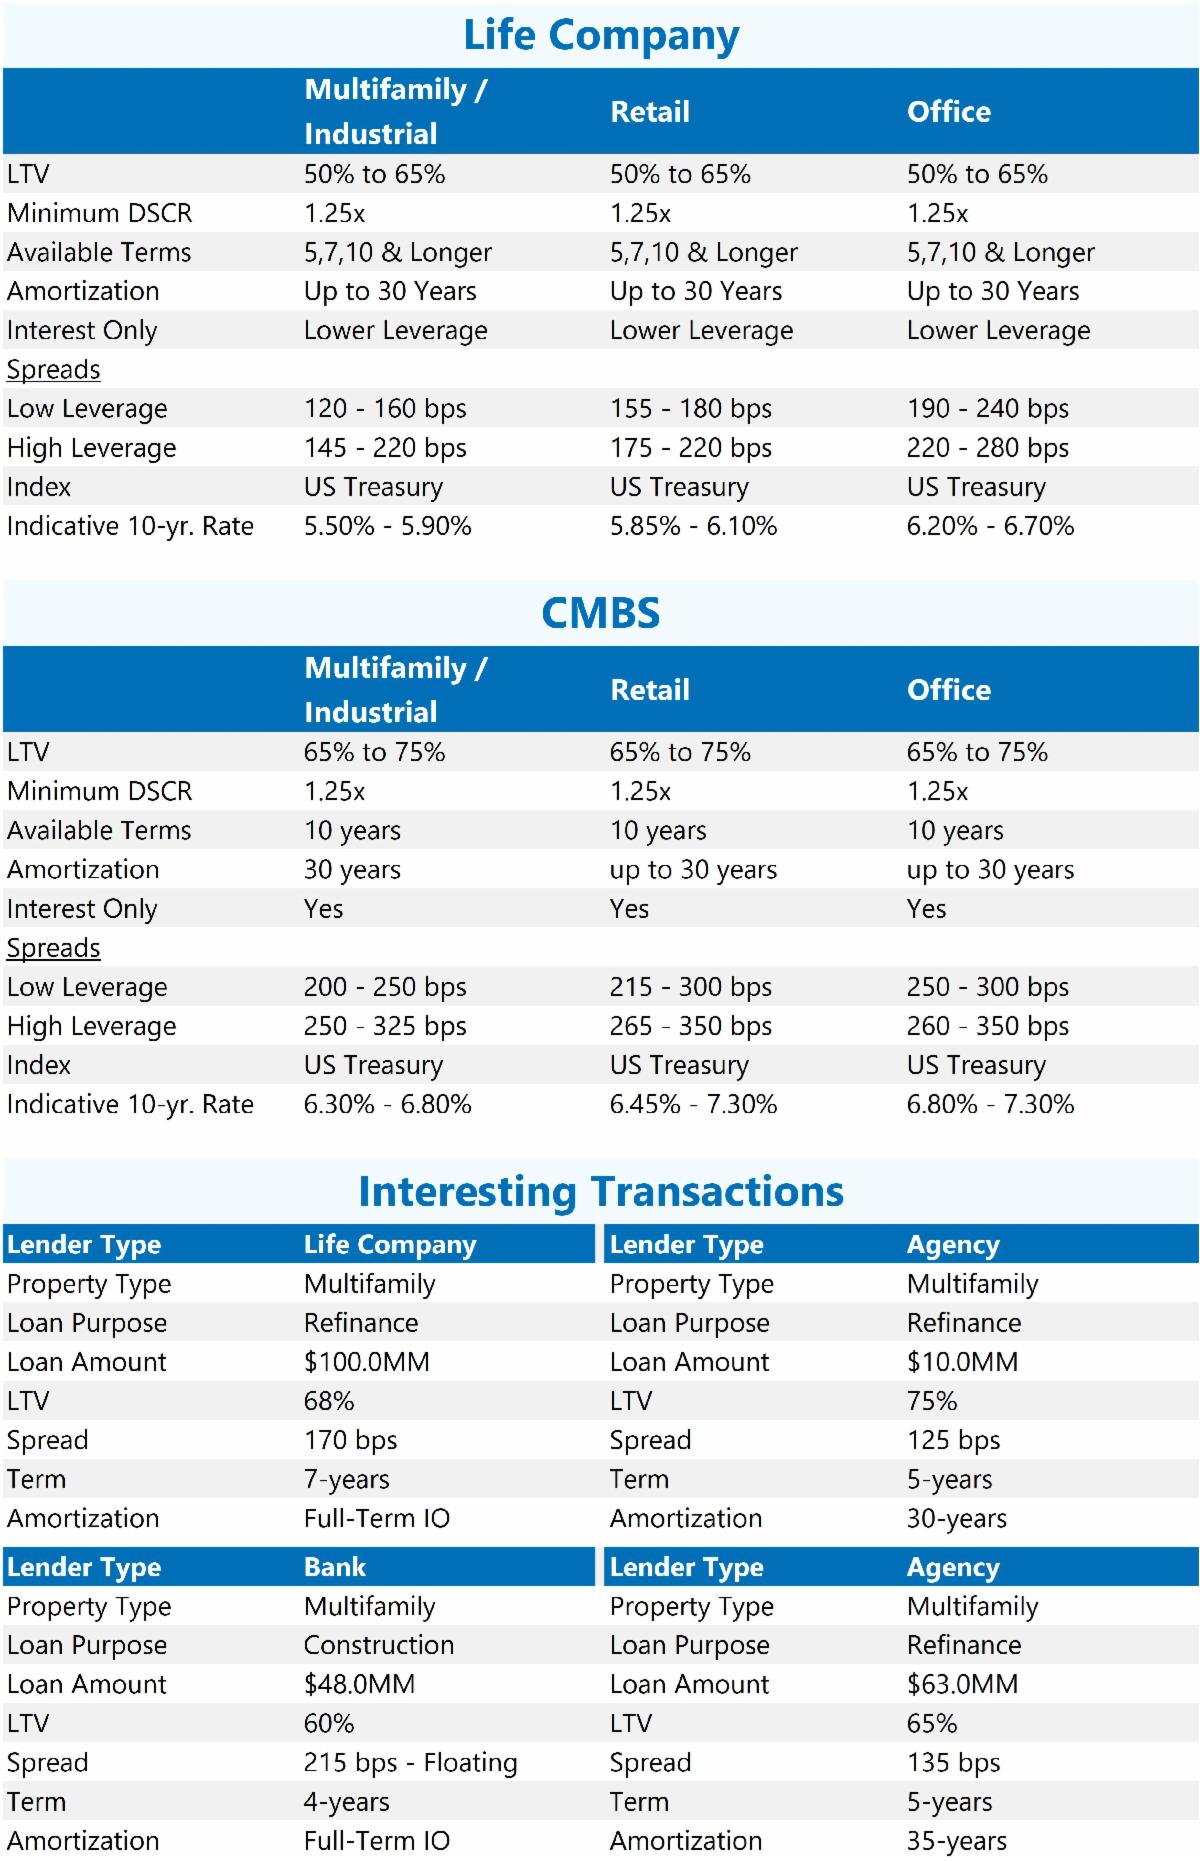
Life Company lenders have maintained their spreads. However, they are starting to impose index floors to stave off substantial downward UST fluctuations. Indicative spreads continue quote between 130-180 bps for quality properties in good locations.


Outlier pricing for highly desirable properties in primary markets with strong sponsors are quoting lower by 20-30 bps. The lending environment is highly competitive with many lenders having substantial capital allocations to place for the year and having shown a willingness to win loan opportunities they really want.


CMBS

U.S. CMBS issuance volume is $33.2 billion YTD, down 13% ($38.1 billion) YoY. Conduit spreads have widened in recent weeks with 10-year AAA spreads currently at approximately 82 bps over Treasuries, slightly wider than the 78-bps average over the past year.


However, borrower spreads have remained range bound over the last several months. Ten-year CMBS loans are pricing 200-225 bps over Treasuries, while 5-year CMBS loans are pricing in the low-to-mid 200-bps range. Pricing may be as low as 140 bps for quality, low leverage business.


Multifamily properties continue to attract strong interest from CMBS lenders, who are still offering full-term, interest-only financing. This structure allows borrowers to maximize loan proceeds, with underwriting typically supporting a 1.25x DSCR on an interest-only basis. Several CMBS lenders have also secured B-buyers for multifamily-only securitizations, enabling them to offer a “stretch senior” product priced at 180-225 bps over Treasuries and sized down to a 1.20x DSCR (interest-only).


Other asset classes, including office properties, have also benefited from full-term, interest-only structures. However, these loans generally require more conservative leverage, higher debt yield thresholds, and stricter underwriting criteria.


About BWE

Bellwether Enterprise (BWE) is one of the nation's largest privately-owned real estate financing companies. Its trusted advisors combine innovation, extensive experience and strong lender relationships to optimize a loan's capital stack for commercial and multifamily investors, developers and property owners. For more information, visit BWE.com.


Opinions, estimates, forecasts and all other information contained in this document are those of Bellwether Enterprise Real Estate Capital, LLC (“Bellwether”) and should not be construed as indicating Bellwether’s business prospects or expected results. Although Bellwether attempts to provide reliable, useful information, it does not guarantee that the information or other content in this document is accurate, current, or suitable for any particular purpose. All content is provided on an “as is” basis, with no warranties of any kind whatsoever and is subject to change at any time without notice. Information in this document may not be used without permission from Bellwether. This document is not intended to be an offer to buy or sell or a solicitation of an offer to buy or sell securities, if any, referred to herein.


Bellwether Enterprise Real Estate Capital, LLC (BWE) conducts business through Bellwether Enterprise Mortgage Investments, LLC – Mortgage Banker license #BK-1007784 – the Department of Financial Institutions State of AZ (Fannie Mae transactions), as well as Bellwether Enterprise Real Estate Capital, LLC – Mortgage Banker License #BK-1007825 – the Department of Financial Institutions State of AZ (all other transactions).