The Capital Stack

May 14, 2026 | BWE Arizona | Putting clients first. Trusted to be part of their future.


Outlier Pricing

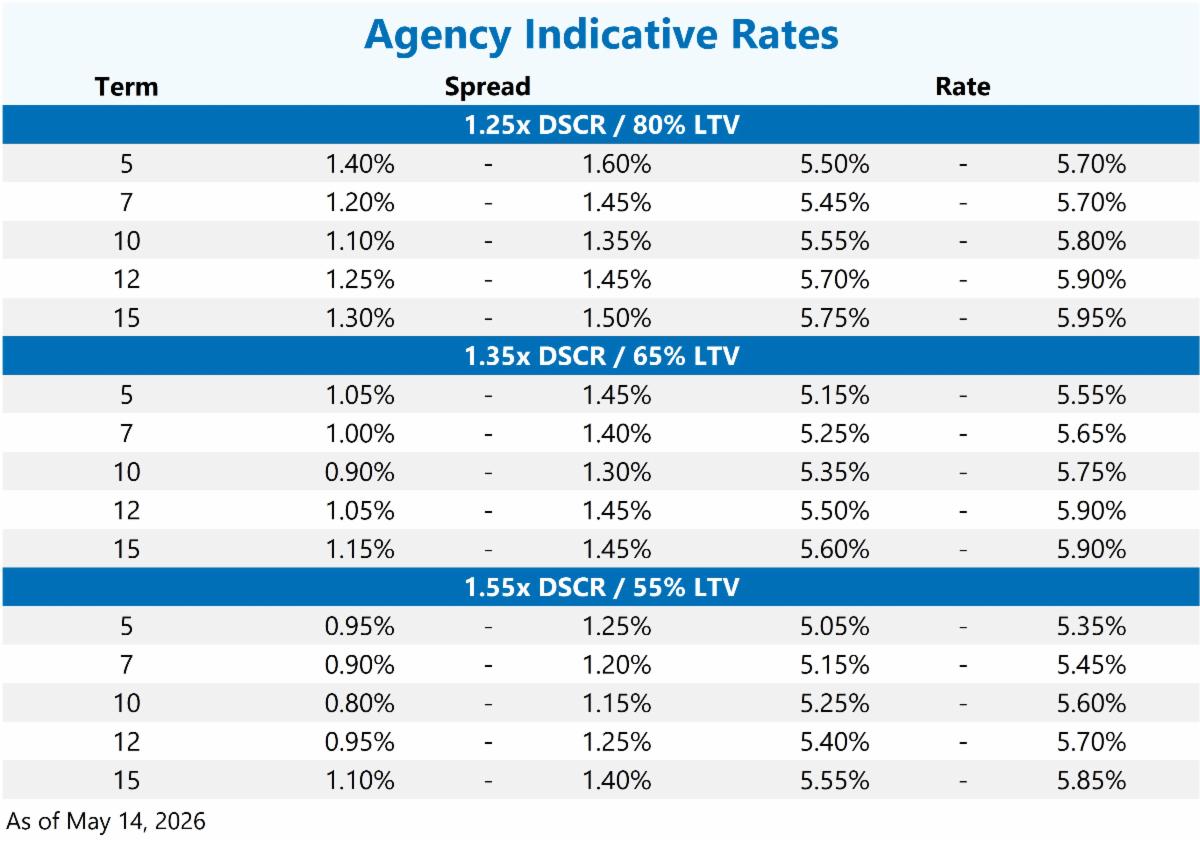
Agency

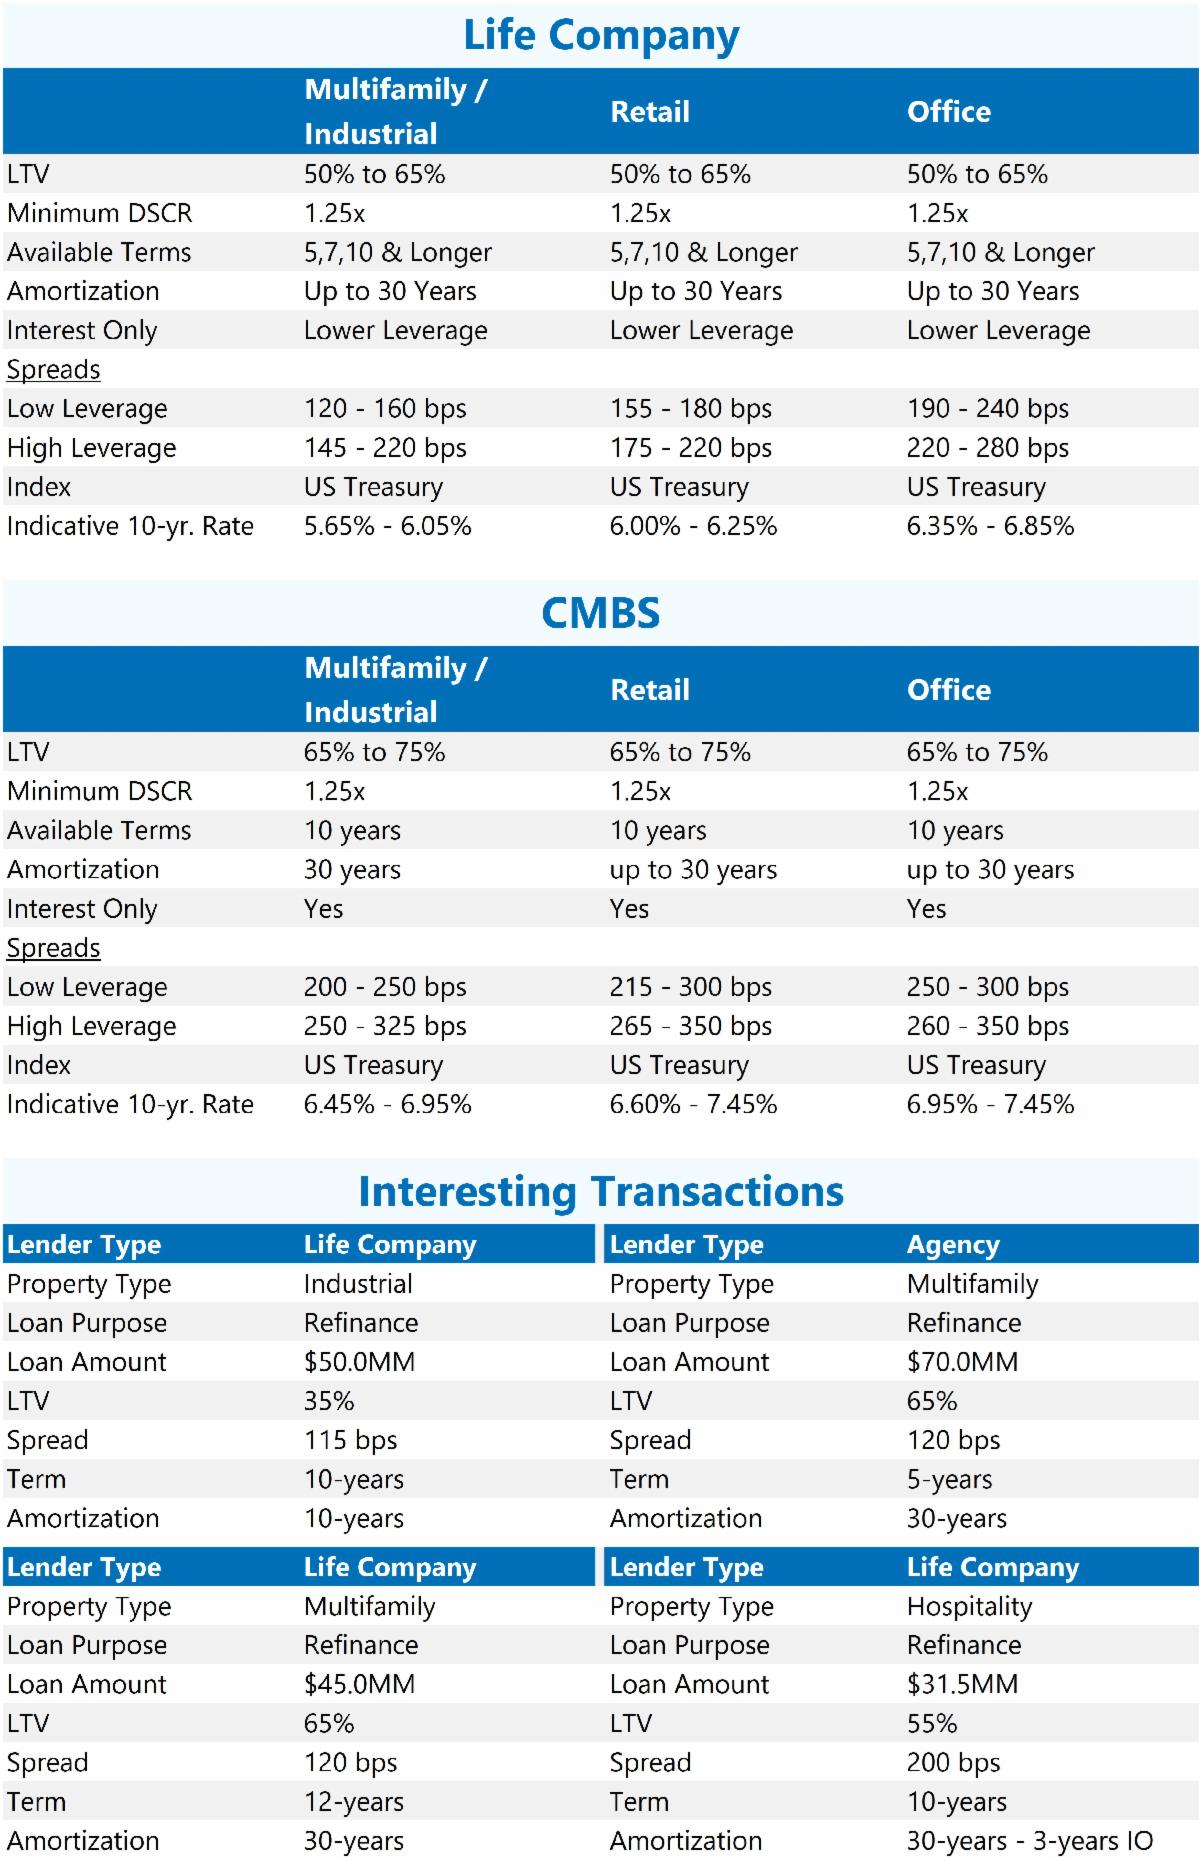
Life Company

5.25%

0.80% + 10yr UST

Low leverage multifamily refinance

5.65%

1.20% + 10yr UST

Low leverage multifamily refinance


Market Commentary

Key takeaways

  • Treasury yields are near YTD highs, ~4.3% to 4.45% on 10-yr
  • Rate cuts appear increasingly unlikely in the near term
  • Markets are beginning to price in a small probability of future rate hikes
  • Persistent geopolitical risk is keeping upward pressure on energy prices and yields
  • Strong labor data supports a resilient economic backdrop, April nonfarm payrolls +115K vs. +65K expected


Macro and geopolitical overview

Market sentiment into early May has been dominated by geopolitical tensions in the Middle East, particularly disruptions in the Strait of Hormuz. Ongoing diplomatic uncertainty between the U.S. and Iran has contributed to elevated oil prices and increased volatility in global markets. Efforts to reopen shipping lanes have produced some progress, keeping energy supply risks elevated and prolonging inflation concerns.


Interest rates and Fed outlook

U.S. Treasury yields have trended higher, with the 10-year yield hovering in the mid-4% range and testing year-to-date highs. Market expectations have shifted meaningfully: while the Federal Reserve remains in a 'wait-and-see' stance, investors are increasingly assigning a small but growing probability to additional rate hikes rather than cuts. Fed commentary and strong economic data have weakened the prior easing bias, reinforcing expectations that policy will remain restrictive for longer.


Labor market strength

April employment data surprised to the upside, with Nonfarm Payrolls increasing by 115,000 versus expectations of 65,000, and the unemployment rate holding steady at 4.3%. Job gains were concentrated on healthcare, transportation, and retail, while wage growth remained moderate. Overall, the labor market continues to demonstrate resilience, reducing urgency for near-term monetary easing.


Energy markets

Oil prices have remained elevated due to supply disruptions, with Brent crude trading above $100/barrel throughout the period. Energy price volatility continues to be a key driver of inflation expectations and interest rate movements.


Inflation and economic data

Inflation remains a central focus, with rising energy costs posing risk that CPI might increase in the near term. Upcoming data releases, including CPI, PPI, and Retail Sales, are expected to provide further insight into inflation trends and consumer strength. While core inflation remains the key metric for policymakers, elevated oil prices may complicate progress toward the Fed’s 2% target.


Agency

Quick hits

  • Pricing remains tight on spreads with buydowns readily available up to 48 bps off.
  • Freddie Mac increases maximum 5-year buydown
  • Increased the max 5 yr 2% buy to 46 bps from 38 bps previously
  • Freddie Mac lowers adders for flexible prepay
  • 5 yr / 2 yrs open at 1% = +18
  • 7 yr / 2 yrs open at 1% = +18
  • 10 yr / 3 yrs open at 1% = +19
  • Observations on recent quotes
  • Freddie Mac has quoted with stronger pricing and more aggressive terms.
  • They are winning more on portfolio refinances, acquisitions, and floating rate loans.


Quiet week for DUS rate locks: Agency CMBS rate lock volume noticeably moderated last week amid persistently elevated yields. The 10-year Treasury remained well above its 100-day moving average, and markets continue to process geopolitical uncertainty. Approximately $300 million in Fannie Mae DUS/MBS rate locks last week, a paltry total that ran well below the $727 million 4-week moving average.


Standard structured DUS/MBS investor spreads were flat over the week, with a slight tightening bias. Given the slim new issuance supply and “safe-haven” characteristics of Agency CMBS, spreads ticked marginally tighter week-over-week. Additionally, some traders noted that investor risk sentiment seems to be improving as evidenced by higher equity prices and a gradual tightening in credit spreads across investment-grade corporate debt products.


Agency CMBS investors continue to bid most aggressively on standard structured loans with full-term interest-only payments, interest rate buydowns, and loans with strong sizes of $25+ million. Freddie Mac priced their $840 million K-561 5-year K-deal transaction within market expectations. There were over half a billion Freddie Mac Participation Certificates (PC) auctioned last week. The CDX Investment Grade 5-year and Bloomberg Single-A Industrials were flat to slightly tighter over the week.


Loan highlights


Freddie Mac refinance in Las Vegas, NV - sub 100 bps spread

  • $59 million
  • 5 year Fixed / 3 years IO
  • 70% LTV / 1.25x DSCR
  • 137 bps spread over 5-year Treasury (no buydown), 91 bps with buydown


Freddie Mac refinance in Springfield, MO - 5th phase of development

  • $18 million
  • 5 year Fixed / 5 years IO
  • 65% LTV / 1.35x DSCR
  • 158 bps spread over 5-year Treasury (no buydown)
  • Prepay flexibility
 

Life Company

Life Company origination activity has stalled over the past two weeks. The previously strong inflow of loan requests during March and April has slowed with lenders citing borrower concerns with inflation and the ongoing geopolitical tensions in the Middle East.


As a result, Life Company lenders have actively quoted opportunities being presented, however, with higher overall loan coupons, they have converted few quotes into loan applications these past few weeks. The opportunities continue to be quoted aggressively, with spreads consistently ranging between 130-180 bps for quality properties in good locations.


Some recent examples include a multifamily property at 65% LTV under application at a spread of 120 bps on a 12/30 structure and a retail building on a 5-year, interest-only loan at 45% LTV quoted at 150 bps. With substantial capital allocations to place, there is a preference for larger loan opportunities.


Lenders are showing creativity to win loans by relaxing certain loan metrics and lowering spreads. Outlier pricing for strong properties in primary markets with good sponsors have been quoted 20-30 bps lower than noted above. Lenders noted a preference for 10-year and longer loan terms, however, there is abundant capital for shorter-term fixed and floating rate requests.


About BWE

Bellwether Enterprise (BWE) is one of the nation's largest privately-owned real estate financing companies. Its trusted advisors combine innovation, extensive experience and strong lender relationships to optimize a loan's capital stack for commercial and multifamily investors, developers and property owners. For more information, visit BWE.com.


Opinions, estimates, forecasts and all other information contained in this document are those of Bellwether Enterprise Real Estate Capital, LLC (“Bellwether”) and should not be construed as indicating Bellwether’s business prospects or expected results. Although Bellwether attempts to provide reliable, useful information, it does not guarantee that the information or other content in this document is accurate, current, or suitable for any particular purpose. All content is provided on an “as is” basis, with no warranties of any kind whatsoever and is subject to change at any time without notice. Information in this document may not be used without permission from Bellwether. This document is not intended to be an offer to buy or sell or a solicitation of an offer to buy or sell securities, if any, referred to herein.


Bellwether Enterprise Real Estate Capital, LLC (BWE) conducts business through Bellwether Enterprise Mortgage Investments, LLC – Mortgage Banker license #BK-1007784 – the Department of Financial Institutions State of AZ (Fannie Mae transactions), as well as Bellwether Enterprise Real Estate Capital, LLC – Mortgage Banker License #BK-1007825 – the Department of Financial Institutions State of AZ (all other transactions).