|
The lanes are merging.
For the past decade, there's been a subset of luxury buyers — frequently international and pied-à-terre purchasers — whose entire map of New York consisted of new development. They rarely toured, and almost never bid on, anything that wasn't ground-up new construction.
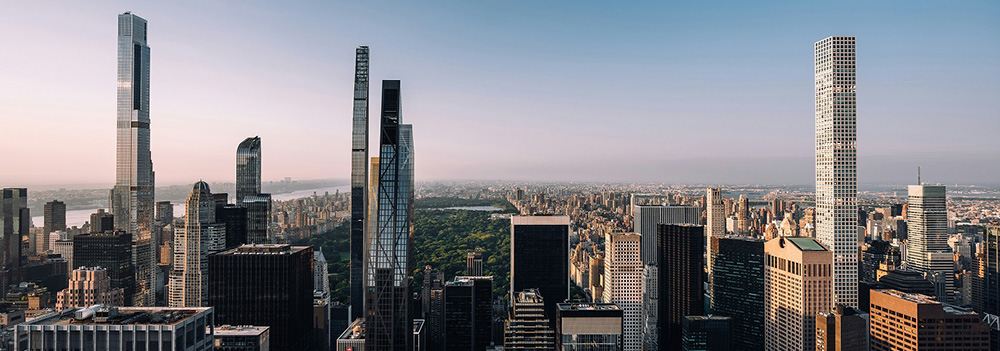
That's starting to change, and the reason is simple math: active new development condo inventory in Manhattan is down roughly 60% since 2020 because developers launched far fewer projects between 2022 and 2025 in the face of rising financing and construction costs. Projects not started then can't deliver now — and won't for years.
I'm seeing it in real time: Miami and Dubai buyers touring a Park Avenue co-op listing of mine. Inquiries on resales of 2022/2023 new developments I represented the first time around. Showing days with my own clients weighing a prewar co-op with Central Park views against a mint, never-occupied condo. These are comparisons that simply weren't being made a few years ago — and each option carries a genuinely different value proposition. Worth knowing: many of the most prestigious co-ops from Park to Fifth can make excellent homes for pied-à-terre and international purchasers, provided their profile is shaped correctly for the board.
For owners, the story isn't price — resale pricing remains disciplined. It's depth. If you own a co-op in a prime location or a recent-vintage condo, there is demand looking at your property class today that wasn't there two years ago.
My read: this is the early edge of a trend, not a blip. New development isn't going away — projects will keep delivering, just fewer of them, and skewed toward the top end of the market. And no, a prewar co-op doesn't price like new construction today. They're different products, and the spread between them is exactly what makes the comparison worth making. What's changed is the menu: smaller than it was, but more varied than it's been in years.
Buyers are weighing genuinely unlike products; owners have a broader — and more international — audience for their properties.
This market requires judgment over autopilot.
|