The Reliant Review
November 2022
|
|
|
Our Most Commonly Asked Questions |
|
What follows are some answers to the questions we are receiving most frequently from our clients. We are happy to set up a call or meeting to discuss them in greater detail should you have further questions about our answers. |
|
Why are the values of my bonds down so much this year? Are bonds still a safe investment? Are bonds a good value now?
The answer to that question lies in the huge upward move we have seen in US Treasury rates over the past year. The first thing to remember is that as market interest rates rise, prices on existing bonds go down. The second thing to remember is that unlike stocks or bond funds, if an individual bond is held to maturity all of the losses will be recouped and your principal returned in full at maturity.
Since the height of the pandemic in mid-2020 and until early 2021, rates remained extraordinarily low. This was largely due to the Federal Reserve keeping its benchmark rate near zero and buying bonds to help support the economy. Longer maturity bond rates gradually rose over the course of 2021. By early 2022, with inflation hitting 40-year highs and the economy running hot, rates rose dramatically across the yield curve. Rates have continued to steadily climb most of this year as inflation has proven to be quite persistent even in the face of tightening monetary policy. For reference, the 1 year US Treasury yield got as low as 0.10% and the 10 year US Treasury spent the majority of 2021 with a yield around 0.50%. As of this writing, the 1 year and 10 year Treasuries are currently 4.75% and 4.14%, respectively. And remember, as interest rates rise, the values of existing bonds decrease. The speed and magnitude of the sell-off in US bonds this year has been unprecedented. The Bloomberg US Aggregate Bond Index is down just over 17%, which is the largest yearly loss going back to its inception in 1977.
The Federal Reserve has taken steps to address rampant inflation by increasing the Fed Funds Rate and letting their balance sheet start to shrink – both forms of restrictive monetary policy meant to reduce inflation and slow economic growth. If successful, these actions should eventually cause interest rates to drop (and existing bond prices to rise). While losses on existing bonds certainly sting, the current market provides some of the best opportunities to invest in bonds we have seen in the past 15 years. Bonds remain an extremely safe asset class, and we actively monitor all bond positions held in your portfolio, only focusing on investment grade companies and municipalities that we have high confidence in their ability to paying their debt even in a slowing economy.
|
|
Why is there a larger cash balance in my account(s) than normal?
The primary reason we have held more cash than normal is due to our cautious outlook on the stock market and our desire to preserve and protect your investment capital. Stock returns from 2019-2021 averaged about 25% per year, so we feel there is great value in protecting your portfolio from some of the current volatility we are seeing. 2022 has been a bear market for stocks, the first true bear market we have faced since the financial crisis in 2008/2009. Bear markets are registered whenever an index goes down in value more than 20% from its previous high. As you know, 2022 has also been a down year for bonds. In fact, this is just the third year since 1926 that both the S&P 500 and US bond returns are negative. Bonds have traditionally provided a portfolio cushion in times of elevated stock market volatility; however, cash has been the best asset to minimize fluctuations this year.
Short term Treasury yields have increased dramatically throughout the year, and that has provided opportunities to purchase US Treasury bills for your portfolio that provide a higher return than a standard money market fund. Should we feel it necessary to maintain a significant cash cushion going forward, then we will continue to purchase short term treasuries to provide additional return.
|
|
What are your thoughts on the stock market right now? Do you think there is still room to go down more?
We remain cautious when it comes to the stock market. Inflation is still too high, both at home and abroad, which will cement a tightening monetary policy. Combined with the inflationary pressure is a strengthening US dollar against foreign currencies. This weighs on domestic companies with high international revenue exposure. Global interest rates are also surging and putting downward pressure on market multiples, so there are plenty of reasons to be cautious about equity markets in general. As we’ve mentioned in the past, making predictions about highs and lows can be a fool’s errand. History is not a perfect indicator, but current conditions in the stock market and within the economy have not deteriorated to levels found at previous stock market lows. We don’t know when the bottom will occur or if it already has, but we do believe that the damage done in many, many stocks will take time to repair, and we do not expect a swift move upward like we saw coming off the Covid lows in early 2020.
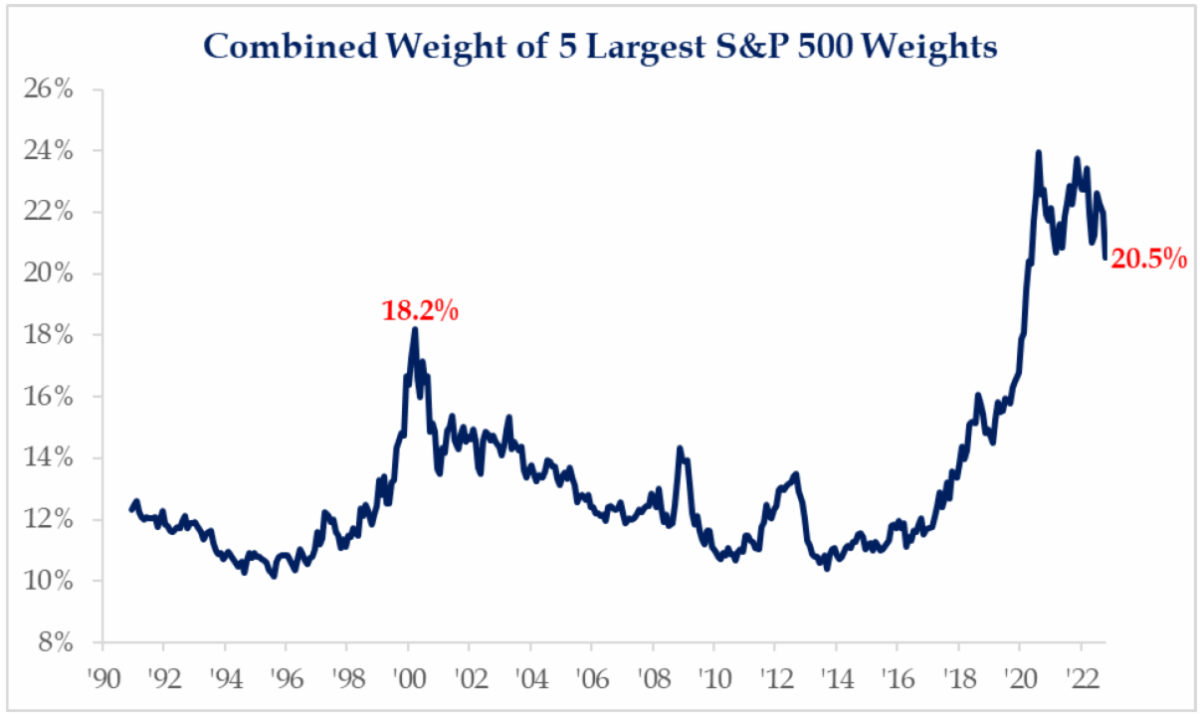
All of that said, we believe that there are strong sectors of the stock market that do warrant investment, with the energy sector being the strongest by a wide margin. Over the course of the year, we have shifted the portfolio to be more defensive by being overweight energy & industrial stocks and underweight technology & communication stocks. Despite the recent weakness from the market heavyweights, the 5 largest constituents of the S&P 500 still make up nearly 20% of the index (Amazon, Alphabet, Microsoft, and Telsa are all down in excess of 30%, while Apple is off about 20%). We believe there is great value to be added by diversifying into more "average stocks" instead of those that are more widely held. Companies with healthy balance sheets, moderate valuations, and pricing power have been the most attractive to maintain in and add to your portfolio.
|
|
What is your outlook for the US economy over the next year?
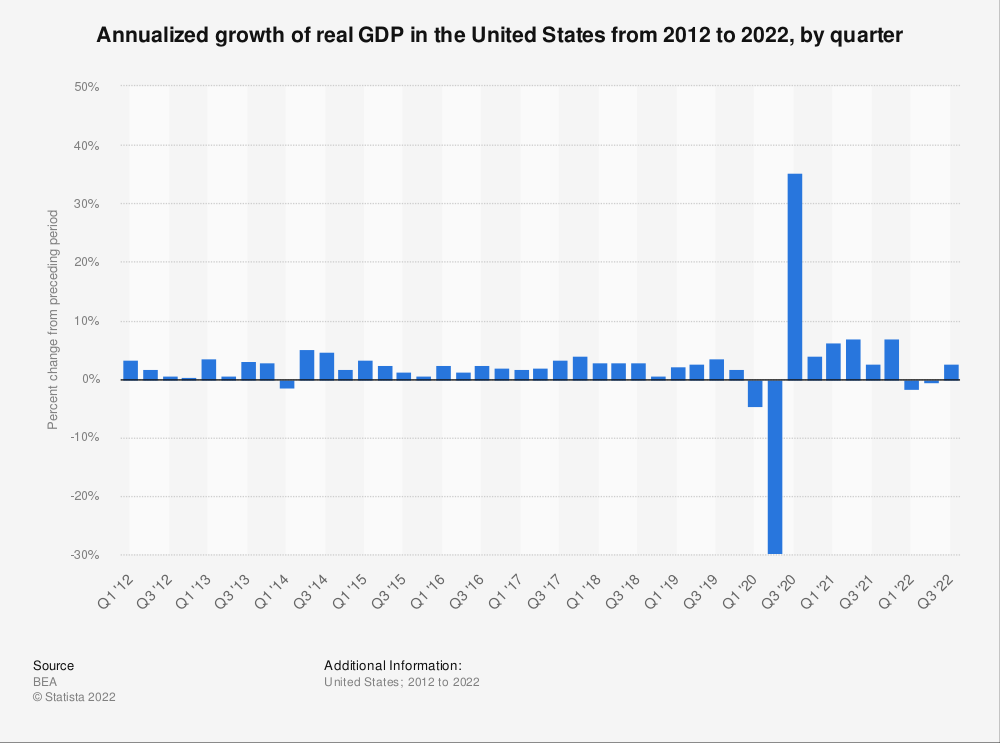
The outlook for the US economy is a little murky over the next year. Our economy has experienced several major shocks over the last few years – trade wars, COVID-19, international conflict. Each of these shocks has had its own adverse impact on our economy. Supply chains, while easing, are still snarled, and geopolitical threats persist – whether issues of warfare or global economic slowdowns. Companies are in the midst of announcing their quarterly earnings & future expectations and are warning of slowing consumer spending, which is consistent with consumer sentiment surveys. The Federal Reserve has made it abundantly clear that its number one priority is making sure that the inflation we are currently experiencing does not become entrenched in our economic life. Hence the fastest rate hiking cycle in nearly 40 years.
As you can see, there are plenty of headwinds facing the US economy, but there is also reason to believe that the coming months could bring some much-needed clarity. The Fed, while firmly committed to stamping out inflation, is beginning to acknowledge the economy’s reaction to higher interest rates as they see the housing market slow and available job openings diminish. US companies are providing much needed insight into consumer behaviors, and they’re detailing for us how they intend to react to changing consumer behaviors and tightening financial conditions. Fed, consumer, and corporate behavior shed light on the underlying state of the economy and provide us a clearer line of sight into what is happening and where things may head next. While we have expectation that the US economy is slowing just as the Fed intends it to, we also have every expectation that that it will reset, even change, and resume its growth trajectory, as has been the case with the ever resilient US economy. It will just take a little time for it all to play out.
|
|
If markets don’t rebound before the end of the year, does it still make sense to gift appreciated stock in 2022, especially if there’s still cash in my portfolio?
Yes, it still makes sense to gift appreciated stock in 2022, even if the markets don’t rebound before the end of the year. Even with the market is off its highs you may still have gains that can be distributed to charity. Remember, when you gift appreciated stock in lieu of a cash donation, you’re not only getting the benefit of the itemized deduction, but you are also able to avoid paying capital gains tax that you otherwise would pay if you sold the stock and then donated cash.
Additionally, now is a good time to have some cash available to redeploy into new investment opportunities as we wait for the stock market volatility to settle out. Gifting appreciated stock in lieu of cash allows you to have that cash available for new investments.
|
|
Additional Points of Interest |
|
Required Minimum Distributions (RMDs) must be taken by the end of the year. Retirement accounts that are funded with pre-tax contributions, such as an IRA or 401(k), are assigned a minimum amount that must be withdrawn each year beginning at age 72. If you have further questions about your RMD or how much you still might need to withdraw, please don't hesitate to give us a call.
Qualified Charitable Distributions (QCDs) are available to retirement account holders over age 70 ½. A QCD is a direct transfer of funds from your retirement account to a qualified charity. QCDs count toward satisfying your required minimum distribution for the year, so it can be a particularly effective tool to mitigate tax bills for those who do not need their RMD to live on during the year.
The annual gift tax exclusion amount for 2022 is $16,000. This annual exclusion means you can give anyone else, such as a relative or friend, up to $16,000 in assets this year, free of federal gift taxes. Payments made directly to a school for tuition or a health care provider for medical expenses on behalf of a another are neither subject to the gift tax nor do they count toward your lifetime exemption.
Social Security benefit payments are set to increase by 8.7% in 2023. Federal benefit rates increase when the cost of living rises and the adjustment next year will be the largest in four decades. Additionally, Medicare premiums for Part B will see a slight monthly decrease next year due to lower Medicare spending in 2021.
|
|
|
|
As always, please do not hesitate to contact us with any questions, ideas, or concerns. We are happy to meet with you in person or via video conference. |
|
|
1715 Aaron Brenner Drive Suite 504 | Memphis, TN 38120 | 901-843-0600
|
|
|
|
|
|
|
|