The Reliant Review
April 2022
|
|
|
The Context of the Quarter |
|
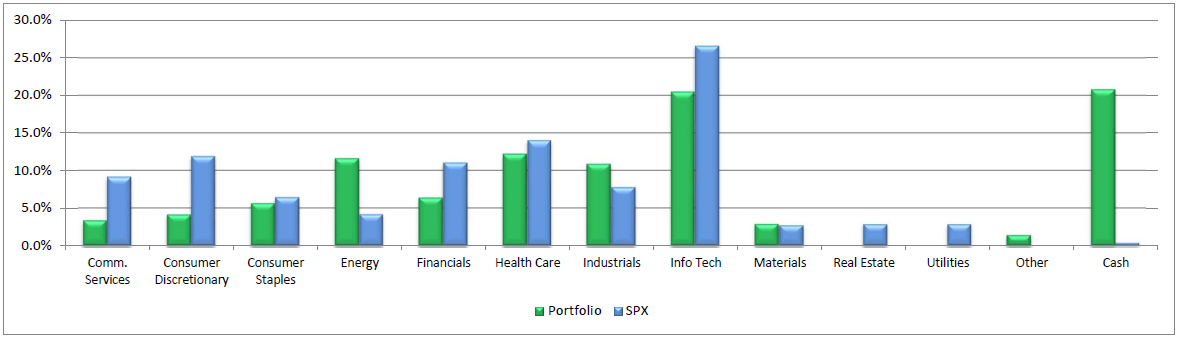
Reliant Strategic Stock Sector Weightings vs S&P 500 Sector Weightings |
|
In our January update, we highlighted the difficulty of making predictions in a world full of unpredictable elements. Since that writing, a war has broken out in eastern Europe, China has imposed its most stringent lockdowns of the pandemic, and inflation in the US has climbed higher with each passing month. Not all the news affecting the financial markets has been bad, but given the context of the economy and world at the moment, we have adjusted stock portfolios to be more defensive. One of our favorite quotes about investing is, “There are only 2 losses in the market, a loss of capital and a loss of opportunity. If we protect the capital, there will always be another opportunity.” (Louise Yamada) We are comfortable protecting capital through the turbulence we’ve experienced so far in 2022. |
|
Speaking of the current context, perhaps we are in the midst of a transition away from the post WWII international order into an era filled with more regular conflict and dispute. China has morphed from economic partner and sometimes rival to a potential enemy in the aftermath of the pandemic. Russia’s attack on Ukraine has upended the idea that countries lacking the Western values of democracy and self-determination can be transformed by greater trade and open communication into good faith citizens of the world. Globalization has been a common goal for many of the world’s most developed and emerging nations over the last 30 years. Many Western corporations have gained competitive advantages by spreading their products, technology, information, and jobs across borders to developing economies in an effort to lower costs and gain a greater market share. So, while we are not in the game of predictions, it does seem as if the current global economic system is on the precipice of yet another transformation. |
|
Globalization has undoubtedly helped to restrain inflation over the last 30 years, but what will a potential fracturing of the current system mean for the world’s largest economy and net importer of goods, the United States? Inflation has continued to increase in recent months on both the domestic and international fronts, and central banks (led by the Federal Reserve) have started the process of raising the costs of borrowing money. Labor conditions remain strong in the US, with millions of jobs still open and layoffs near record lows. Payroll growth has not kept up with the recent rates of inflation, but it has increased steadily as of late. Corporate earnings growth persists (perhaps not as robust as in 2021), and COVID impacts are clearly receding, as evidenced by where and how consumers are spending their money. |
|
Many argue it’s hard to have a recession with the job market so strong and consumers flush with cash from elevated savings rates over the past few years. However, it should be noted that unemployment has typically been a lagging, not leading indicator. And, who hasn't experienced paying more today for goods and services than you did a year ago? Considering these pressures, our focus in the coming months will be on leading indicators and the effect that supply chain constraints, the war in Ukraine, and a more aggressive Fed have on them. One thing is for sure, consumer sentiment indicators regarding the outlook for the economy are the lowest since 2014, and with the consumer representing roughly two-thirds of the economy, we need the consumer to keep spending to help stave off an economic slowdown. |
|
“I used to think that if there was reincarnation, I wanted to come back as the president or the pope or as a .400 baseball hitter. But now I would like to come back as the bond market. You can intimidate everybody.” - James Carville
The first quarter of 2022 proved to be quite a tumultuous ride for fixed income investors. Over the course of the quarter, rates on the short end of the treasury yield curve (2-year & 3-year bonds) rose from approximately 0.80% to 2.60%—largely due to more aggressive Federal Reserve commentary and a looming rate hike cycle. Intermediate bonds also rose considerably and are now close to the highest levels in a decade, recently peaking just under 3.00%. This is a dramatic improvement from the depths of COVID when the rate on the 10-year bond got as low as 0.50%. While the steep rise in yields caused fixed income underperformance for the quarter, many investors are excited at the prospect of being able to earn more income from the bond market again.
Discussions about the yield curve and the rise in interest rates highlight the importance of signaling and communication from the Fed. For example, while the Fed Funds rate has only been lifted by 0.25% so far, markets have quickly moved other bond yields higher in anticipation of subsequent rate hikes. This current rise in yields has indicated that the bond market believes the Federal Reserve will raise the Fed Funds rate to nearly 3.00% by the end of 2023.
We believe this preemptive shift in what you can earn is important because it provides the most compelling opportunity to invest in bonds since the COVID outbreak. Additionally, we don’t see the Fed having much room to be more restrictive with their policy (by hiking rates further) as it could lead to concerns that economic growth could slow and a recession could be imminent. As always, we will be closing watching the credit markets and credit spreads for any signs of stress as this could cause the Fed to shift policy. In the meantime, our focus will be on taking full advantage of this opportunity the market has provided in municipal, corporate, and other fixed income sectors.
|
|
Required Minimum Distribution (RMD) changes you should know about
- The beginning age for your first RMD has changed from 70 ½ to age 72. Retirement accounts that are funded with pre-tax contributions, such as an IRA or 401(k), are assigned a minimum amount that must be withdrawn each year after age 72.
- If you have been receiving RMDs in the past, you may have noticed a more significant change to the annual amount than usual. In addition to increasing the beginning RMD age, the IRS has also issued new life expectancy tables with which to calculate the distribution amount.
- We have made adjustments to any RMDs from Reliant accounts, but if you have further questions please don't hesitate to give us a call.
Qualified Charitable Distributions (QCDs) are available to retirement account holders over age 70 ½. A QCD is a direct transfer of funds from your retirement account to a qualified charity. QCDs can be counted toward satisfying your required minimum distribution for the year, so it can be a particularly effective tool to mitigate tax bills for those who do not need their RMD to live on during the year.
Post tax season is a great time to revisit and evaluate your financial position and plans. We would be happy to meet with you to discuss any changes you may feel are pertinent or to review your financial needs and goals.
|
|
|
|
As always, please do not hesitate to contact us with any questions, ideas, or concerns. We are happy to meet with you in person or via video conference. |
|
|
1715 Aaron Brenner Drive Suite 504 | Memphis, TN 38120 | 901-843-0600
|
|
|
|
|
|
|
|