The Reliant Review
October 2021
|
|
|
First introduced in 1759, Adam Smith’s theory of the invisible hand states that the free market forces of supply and demand will naturally lead to an equilibrium that best suits the interests of the participants within it. Said alternatively, the economy works best when information and goods are allowed to flow freely between buyers and sellers. Smith further argued that any imposition of free-flowing information leads to some form of market inefficiency. We aren’t trying to give you flashbacks to a freshman year Econ 101 class, but it’s clear that our economy is still feeling the effects of the 2020 shutdowns related to COVID. The dislocation has caused an 18-month supply chain disruption that is proving much harder to weather than initially forecast. Locking down our economy tangled intricate webs of commerce and has in turn affected nearly every corner of our marketplace. |
|
Lately, we’ve been reminded of a great example illustrating this phenomenon from the essay “I, Pencil” by Leonard Read. Written from the perspective of a pencil that details the complexity of its own creation, the essay begins with the pencil remarking, “I am seemingly so simple. Simple? Yet not a single person on the face of this earth knows how to make me.”
The parts of a pencil seem rudimentary (wood, graphite, paint, etc.) but there is a highly specialized and complex chain of events that are involved in the actual assembly. Loggers or paint makers need equipment and resources to operate, as do all other suppliers involved in the process. If just one part of the equation is delayed or impeded, then the whole method of making a pencil is made that much harder.
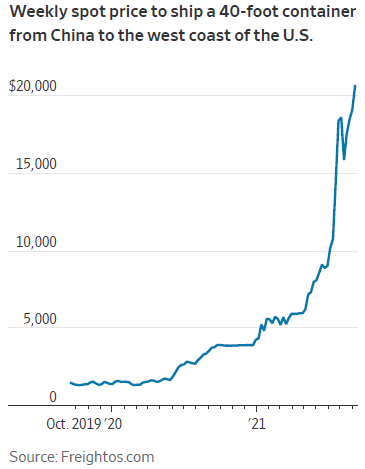
Cargo ship bottlenecks at ports, raw material & labor shortages, increased fuel costs—those are just some of the current factors companies face in their daily operations. Methods of business have become more costly and challenging, which ultimately affects consumers the most.
|
|
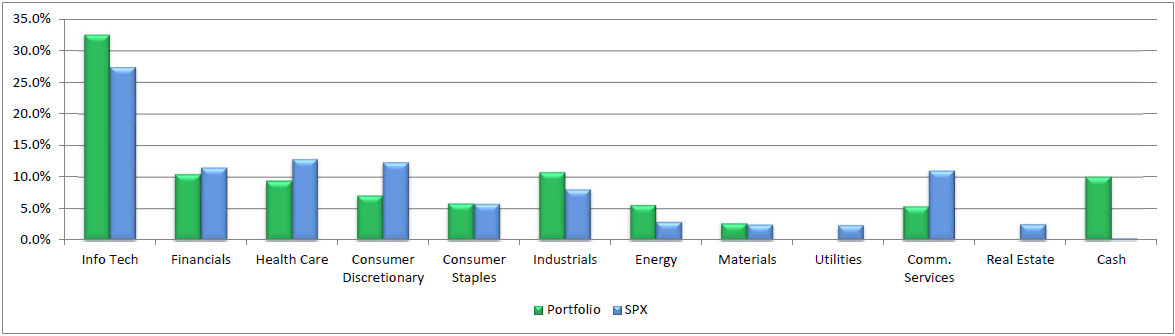
These underlying dynamics do give us pause. Longer supplier delivery times inevitably make price shocks less transitory, thus leading to more persistent inflation. Additionally, central bankers in the US and abroad now face the challenge of communicating their desire to pull back quantitative easing and lift interest rates to address inflation amidst choppy economic growth data (more on that below). We are comfortable with the recent actions we’ve taken to temporarily reduce exposure to stocks, mindful that we have cash available to deploy when opportunities arise. |
|
Reliant Strategic Sector Weightings vs S&P 500 Sector Weightings |
|
We added Autodesk to the portfolio during the quarter. Autodesk is a computer-aided design software company that professionals rely on to design and model buildings, animated films, manufactured products, and video games. More than 70% of Autodesk’s business is in the architecture, engineering, and construction industry, a segment of the economy we expect to continue its recent boom given the demand for new housing and improvements to existing infrastructure.
Willis Towers Watson, a diversified brokerage and consulting firm, was another recent addition. Like other insurance firms, Willis takes a percentage of premiums as commission, and is thus exposed to the direction of the insurance pricing cycle. Recent pricing momentum has picked up to its strongest level in almost 20 years, which we feel should boost growth in the near term and offset any negative impacts of COVID on the more discretionary areas of the business.
We sold PPG Industries due primarily to the negative impact supply chain disruptions are having on its business. Raw material inflation is providing stronger headwinds than management previously thought, and the effects of Hurricane Ida have hit companies dependent on polymer chemicals hardest. We still believe PPG’s core business and management team are well positioned to capitalize on emerging trends over the next decade, but in the near term we believe a timeout on the stock is warranted.
|
|
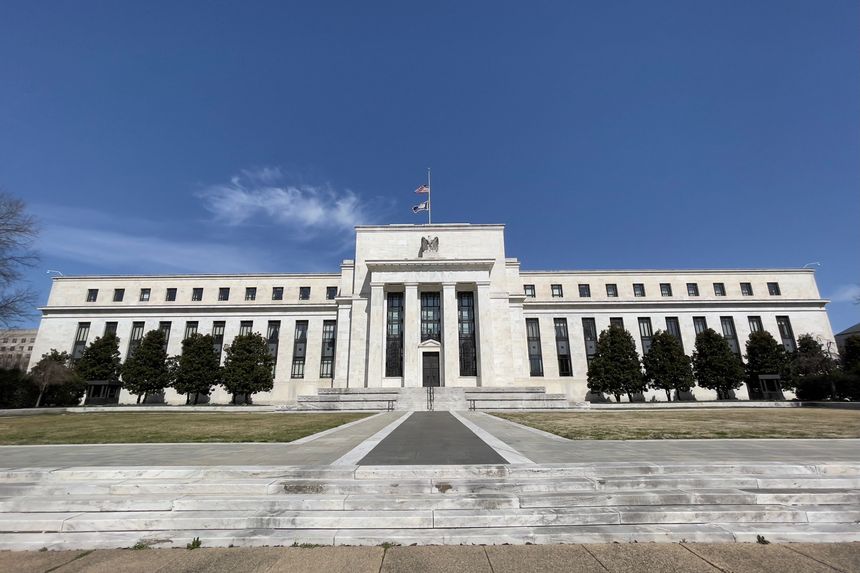
The September Federal Reserve meeting was highly anticipated as many investors awaited more specific guidance from Chairman Powell on the timing of bond tapering. As a reminder, bond tapering refers to the reduction in the $120 billion of US-Treasury and mortgage-backed bonds (MBS) that the Fed is purchasing monthly to help support the economy. It is the initial signal removing ultra-loose monetary policy. Once the tapering of bond purchases is complete, the next step will be the Fed raising interest rates, and thus both these actions from the Fed have direct impact on the bond markets.
There is ample evidence the Fed should start the taper sooner rather than later (notice we didn’t say hike rates), as the monetary stimulus is only adding to inflation as the economy emerges from the pandemic. This is concerning as there are economic signs pointing to stagflation, an odd combination of rising inflation and slowing economic growth. Stagflation was first recognized during the early 1970s oil crisis – spiking oil prices combined with stagnating growth and wages.
We now find ourselves in a somewhat similar situation with supply chain bottlenecks, factory closures, labor shortages, and general input costs rising while growth is expected to moderate as monetary and fiscal stimulus wanes. Stagflation can handicap the effectiveness of the Federal Reserve and put them in a catch-22: tightening monetary policy will only slow down growth more, but keeping monetary policy loose encourages more inflation. For stagflation to truly take root, we must determine if current inflation is transitory or of a longer lasting variety. Over the coming months we will be watching closely for signs of stagflation & the timing and speed of the Fed taper. Historically, Fed tapering and subsequent rate hikes have brought some much-needed yield to the front end of the treasury curve, while tightening policy has led to lower long-term interest rates as it dampens long-term inflation expectations.
|
|
The annual gift tax exclusion amount for 2021 is $15,000. As you may be aware, this annual exclusion means you can give anyone else, such as a relative or friend, up to $15,000 in assets this year, free of federal gift taxes. Payments made directly to a school for tuition or a health care provider for medical expenses on behalf of a another are not subject to the gift tax nor does it count toward your lifetime exemption.
Required Minimum Distributions (RMDs) must be taken by the end of the year. If you are 72 or older, we can help determine the amount required to withdraw from your retirement in 2021. Contact us to take your distribution.
Qualified Charitable Distributions (QCDs) are available to retirement account holders over age 70 ½. A QCD is a direct transfer of funds from your retirement account to a qualified charity. QCDs can be counted toward satisfying your required minimum distribution for the year, so it can be a particularly effective tool to mitigate tax bills for those who do not need their RMD to live on during the year.
Charitable gifts must be made before the end of the year to count towards your 2021 taxes. Keep in mind that appreciated stock can be transferred directly to an organization or Donor Advised Fund, thereby avoiding capital gains taxes. Please contact us no later than December 1st to ensure your gift is processed by the end of the year.
|
|
|
|
As always, please do not hesitate to contact us with any questions, ideas, or concerns. We are happy to meet with you in person or via video conference. |
|
|
1715 Aaron Brenner Drive Suite 504 | Memphis, TN 38120 | 901-843-0600
|
|
|
|
|
|
|
|