|
“'For the biggest investor to say I’m not putting another dime in was a huge vote of non-confidence. I could argue that had he not said anything we might have been in a very different situation,' says a person close to Credit Suisse’s top management.
On Wednesday, the so-called “trinity” of the Swiss National Bank, regulator Finma and the minister of finance summoned Credit Suisse chair Axel Lehmann, who was in Saudi Arabia for a conference, and chief executive Ulrich Körner for a call.
In the same meeting where they authorized a SFr50bn [($54bn) liquidity backstop from the Swiss central bank], they also delivered another message: ‘You will merge with UBS and announce Sunday evening before Asia opens. This is not optional,’ a person briefed on the conversation recalls.
[UBS Chairman Colm] Kelleher found out his weekend plans were ruined on Thursday afternoon. The trinity called UBS and ordered the group to find a solution to save its ailing peer from bankruptcy.
‘Resolution [a government-controlled wind-down] would have been a disaster for the financial system and introduced the threat of contagion around the world,’ says another person involved on the UBS side. ‘Our interests were also aligned because a failure is not good for the Swiss wealth-management brand. So we said, on the right terms, we would help.’
The takeover of its local rival could end up being a once-in-a-generation boon for UBS. But in exchange for taking on a bank wracked with litigation issues and billions of toxic assets, UBS was determined to extract the best deal that it could.”
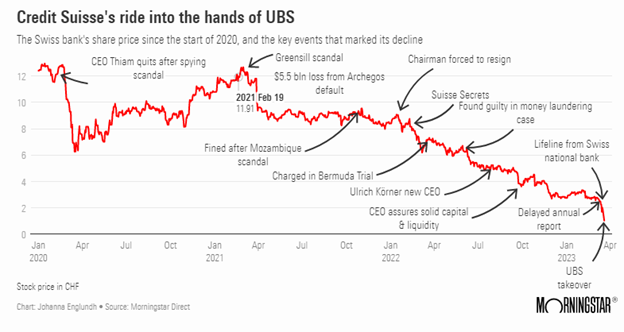
Credit Suisse has been on a slow death march since 2011 that only accelerated over the last 3 years until the forced buyout by rival UBS this past weekend. Internal spying operations on its own executives, the Bill Hwang family office blowup, fines for bribery in Mozambique, other scandals, and accounting issues never allowed the bank to fully recover from the Great Financial Crisis. The 166-year-old bank will fold into UBS before year-end.
|