|
Unfortunately, in order to gain some perspective on this year’s developments so far in the bond market, we do need to take a look back at the ‘year that should not be named’…2022. In other words, any positive performances here in 2023 must be looked at in the context of just how ‘bad’ 2022 actually was…
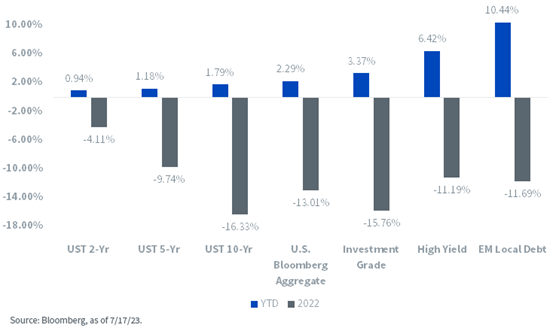
The best place to start would be the U.S. Bloomberg Aggregate Index (Agg), otherwise known as the benchmark for fixed income markets. In 2022, the Agg plummeted by 13%, as the four major areas that make up this index all struggled mightily. Through the first two weeks of July this year, the Agg has managed to rebound by almost 2.3%. While this performance does not come close to making up for last year’s loss, it’s still nice to be back in the plus column…
Conclusion
Obviously, the results outlined in this blog post are, to some extent, yesterday’s news. The natural question is where are we going from here? With the Fed, and perhaps other global central banks, nearing the end of their respective rate hike cycles, inflation continuing to cool and economic growth softening, it seems reasonable to expect fixed income returns will remain in positive territory through the second half of this year.”
I could have copied and pasted most of the same comments from stock markets’ polar opposite first half for fixed income markets.
After a rapid rise in rates during 2022, rates have stabilized across the yield curve allowing investors to pick much higher coupons. That stability led to a performance reversal on the U.S. Aggregate Bond Index from a 13% loss in 2022 to a 2%+ gain year-to-date in 2023.
|