RBGWA - Logo - Full Color.png
 

RBG Wealth Weekly

September 1, 2023


Ladies and gentlemen, the weekend! In this space each week, Greg and I share some of our favorite articles, notes, and graphics from the past week along with our commentary. Please feel free to provide feedback and forward along to others if you enjoy. We appreciate you taking the time to read. 


If you are a client, we truly appreciate your business. If you are not a client, please click below to learn more about our firm and contact us.

Visit our Website
 

Articles of the Week

Major Asset Classes | August 2023 | Performance Review


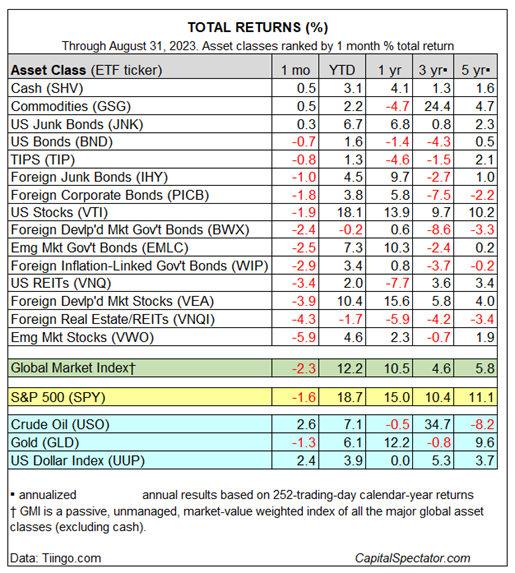
“Cash led the performance race in August for the major asset classes, based on a set of proxy ETFs. In fact, most markets posted losses last month. The handful of winners, in addition to cash: a broad measure of commodities and US junk bonds.


The iShares Short Treasury Bond ETF (SHV), a cash proxy based on short-term government bonds with maturities of 1-year or less, rose 0.5% in August. The gain edged out a virtually identical increase for iShares S&P GSCI Commodity-Indexed Trust (GSG). A close third-place performer: SPDR Bloomberg High Yield Bond ETF (JNK), which posted a 0.3% advance last month.


The rest of the major asset classes ended the month in the red. The deepest decline in August: stocks in emerging markets (VWO), which tumbled a hefty 5.9%, marking the fund’s deepest monthly setback since February.


US stocks (VTI) also lost ground last month, albeit by a comparatively middling 1.9% decline.


Year to date, most of the major asset classes are still posting gains, led by a sizzling return for US shares (VTI), which are up 18.1% so far in 2023.”

Unemployment Up 0.3% = Fed on Hold


“The Fed is done.


It’s unimaginable that they will do anything at the September FOMC meeting, and barring any radical change in the data, it’s unlikely they will be doing anything in November.


I have been saying since June 2022 that inflation had peaked; the data has been leaning that way since May 2022. If you were watching the video instead of the still pic, it was apparent that the biggest risk to the economy then was less rising prices than a tardy FOMC over-tightening.


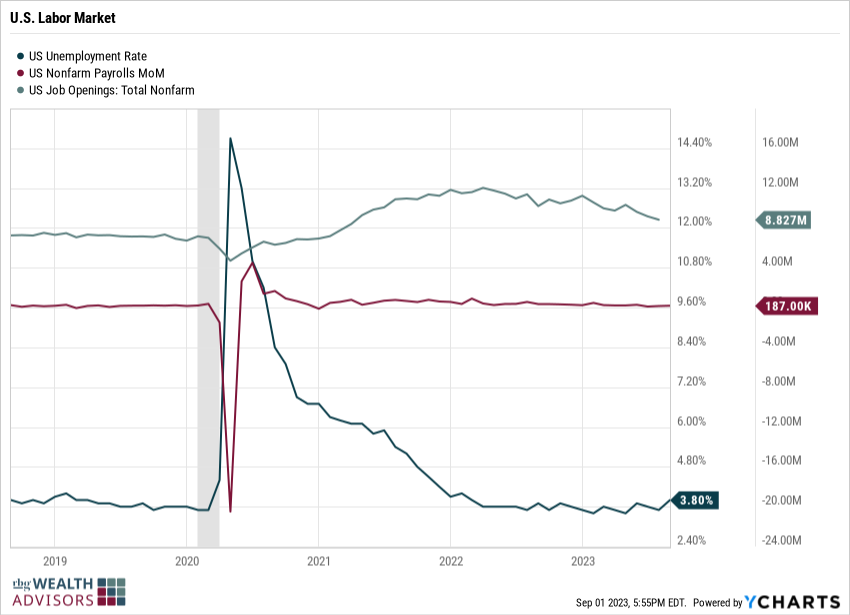
Not only did U3 unemployment tick up 0.3%, wage data continued to decelerate and revisions were downwards. Perhaps most intriguing is total employment: After collapsing during the pandemic, and then spiking upwards as we re-opened, this report shows it has returned to its long-term trend.”


Tuesday’s Jobs Opening and Labor Turnover Survey (JOLTS) report was a harbinger of some softening in the labor market. That report showed job openings dropped to the lowest level in 2 ½ years and workers quitting their jobs also decreased.


Friday’s jobs report showed +187,000 jobs, which was at expectations, but the prior two months were revised downward by 110,000. That plus an increase in the participation rate made the headline unemployment rate rise to 3.8%.


Fine, but softening. That should give the Fed something to think about. The stock market reaction was mixed-to-mildly positive.

Case of Buy on the Rumor, Sell on the News


“Since the last FOMC meeting last month, the only economic dynamic that occurred is an uptick in economic growth projections—particularly from real time forecasting models like those from the Atlanta Fed that show an over 5% estimate for Q3 real GDP.


But the stronger economic growth and forecasts are being caused by a jump in productivity. Powell did not mention productivity at all but rather seemed to worry that stronger economic growth could ignite more inflation from the labor market. There is no evidence the labor market is tightening further now. There's also no evidence that it's loosening all that significantly either. But the rate of hiring and hours worked is significantly down this year from last year. We’ll get more evidence with this Friday’s employment report…


All that said, we are still quite early before the next FOMC point. Most do not see a rate increase at the September meeting and all eyes go to November. The market has started pricing in a 50-50 probability of a November hike, but we will get a lot more data before the November meeting. We are seeing rising delinquencies on auto loans, on credit cards, and there are signs of a credit default cycle picking up. These are downside risks.


Nvidia earnings emphasize again that technology capital expenditures and advancement will spur economic growth into the future. Real GDP growth is going up, real interest rates are going up and that is going to keep these levels of interest rates firm. There's more talk about R*, the equilibrium real Fed Funds rate, being higher than 0.5% and I concur that it probably has moved up recently…


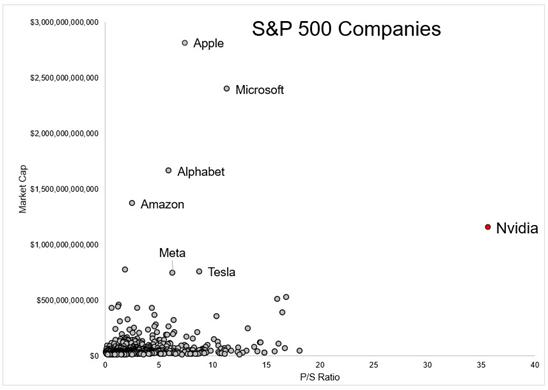
Nvidia’s earnings response shows the trouble of very high valuation multiples—even when the stock far surpassed what analysts estimated, the stock failed to hold its after-hours rally and declined through the end of the week. Were there any buyers left after so many were bullish? This was a classic case of buy on the rumor, sell on the news.”

Professor Siegel had a good write-up on the Fed’s Jackson Hole meeting and a topic that I covered last week – Nvidia.


One challenge that the market has been grappling with is a dislocation between profit margins and productivity growth, especially post-Covid pandemic. Capital investments should produce a lagged boost in productivity; however, you have to be cautious in trying to ride out growth waves in high valuation companies (e.g., Nvidia). 

Read More
 

Graph of the Week

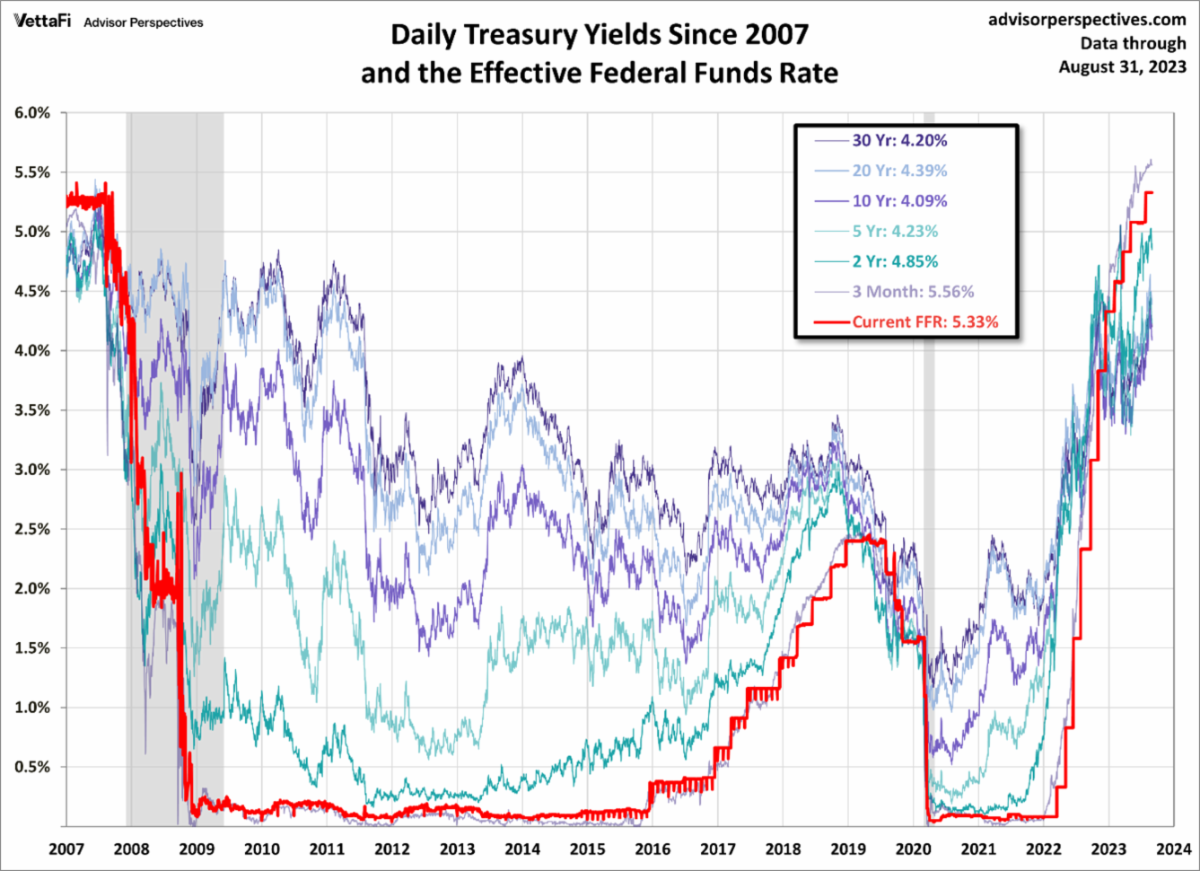
The Fed funds rate is now above most of the yield curve with the exception of 3-month Treasuries.

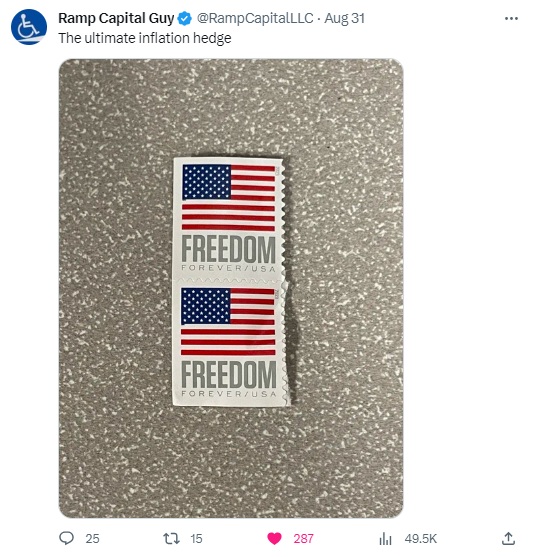
Tweet (or maybe X) of the Week

Thanks for reading. Have a great Labor Day weekend!


Guidance for today. Growth for tomorrow.


RBGWA - Logo - Full Color.jpg

Tim Ellis, CPA/PFS, CFP®

CIO and Wealth Advisor

RBG Wealth Advisors

O: 901.244.2891 | C: 662.444.1415

E:  tellis@rbgwa.com

A:  5100 Wheelis Dr., Ste. 211, Memphis, TN 38117

W: rbgwa.com

LinkedIn  Twitter  Facebook

RBG Wealth Advisors LLC is a registered investment adviser. Information presented is for educational purposes only and does not intend to make an offer or solicitation for the sale or purchase of any specific securities, investments, or investment strategies. Investments involve risk and, unless otherwise stated, are not guaranteed. Be sure to first consult with a qualified financial adviser and/or tax professional before implementing any strategy discussed herein. Past performance is not indicative of future performance.