RBGWA - Logo - Full Color.png
 

RBG Wealth Weekly

September 8, 2023


Ladies and gentlemen, the weekend! In this space each week, Greg and I share some of our favorite articles, notes, and graphics from the past week along with our commentary. Please feel free to provide feedback and forward along to others if you enjoy. We appreciate you taking the time to read. 


If you are a client, we truly appreciate your business. If you are not a client, please click below to learn more about our firm and contact us.

Visit our Website
 

Articles of the Week

Is It Risk-Off Yet? Price Trends Still Leave Room for Debate


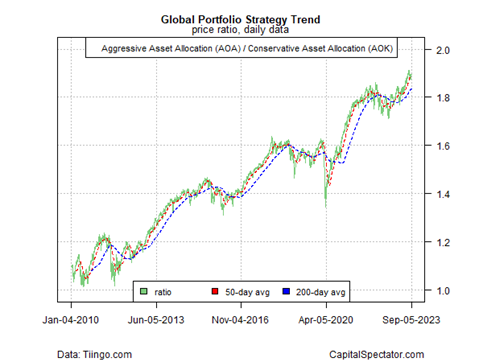
“Financial markets have had a bumpy ride lately, inspiring fresh concerns that this year’s rebound from 2022’s sharp loss has run its course. It’s premature to dismiss that possibility, but a review of several sets of ETF pairs for markets still leave room for debate, based on prices through yesterday’s close (Sep. 5).


Let’s start with the ratio for aggressive (AOA) and conservative (AOK) asset allocation ETFs. For the moment, this global proxy of risk appetite suggests that a bullish trend remains intact. The latest downturn may turn into a deeper rout, but for now the upside bias endures.

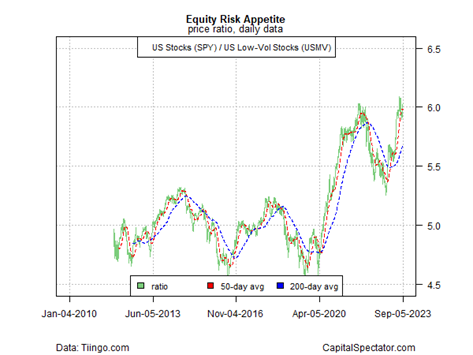
The risk appetite for US shares also looks solid, based on the ratio for US stocks (SPY) vs. low-volatility shares (USMV), the latter being a proxy of demand for a relatively conservative/defensive equities strategy…

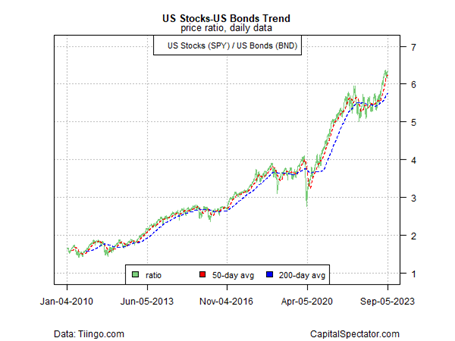
The rise in bond yields recently suggests that the allure of fixed income threatens the outlook for stocks. Why take the risk of the equities market when you can earn a safe yield in government securities? That view is starting to resonate, but price action of late has yet to reveal a clear reversal for the risk appetite. Note that the relative strength for US shares (SPY) vs. US bonds (BND) continues to indicate a strong upside bias.

The caveat is that market trends end eventually, but calling the exact point when a genuine reversal begins is impossible. Only with hindsight will major tops and bottoms become obvious. For the moment, it’s not clear that this year’s recovery in the demand for risk has run out of road. A turning point will become obvious in time, but for now the trend signals for risk still skew positive.”


The trend is your friend. A soft August and first week of September for the stock market has not disrupted risk-on trends in capital markets, yet. After the hot start to the year and looking at standard seasonality, this is likely just normal market behavior.

What do I need to know after summer vacation?


“The best place to start is the labor market. The Job Opening and Labor Turnover Survey (JOLTS) highlighted that job openings fell to a level of 8.8 million in July, the lowest level since March 2021. Additionally, quits and layoffs both increased; while all three of these metrics are elevated relative to pre-pandemic levels, they are beginning to signal that the labor market is moderating…


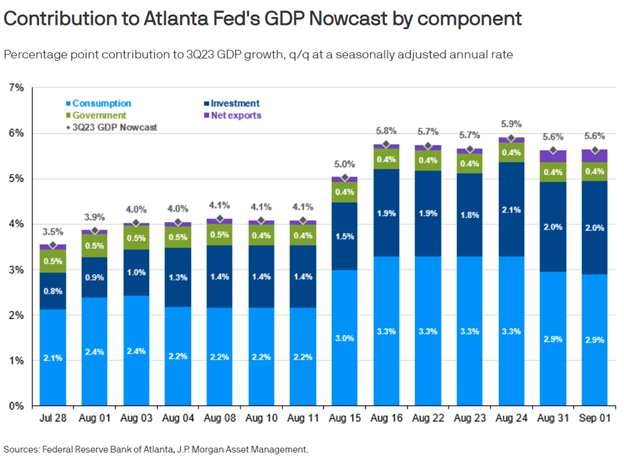
While we are seeing signs that the labor market is cooling, other economic data released last week reinforced the idea that economic growth may have accelerated in the third quarter relative to what was observed during the first half of the year. Real consumer spending remained strong in July, growing 0.6% month/month. Services and goods spending picked up as well on the back of a declining savings rate. At the same time, nominal construction spending picked up in July, with particularly strong growth in private residential spending.


Looking ahead, recent softness in the labor market, coupled with a downward trend in inflation, should be enough to keep the Federal Reserve on hold at the September meeting. Whether this trend persists going forward, however, remains to be seen, as there is a tension evolving between better economic activity and cooler inflation data.”

This was a good concise review of economic growth factors and the inputs that the Federal Reserve is reviewing going into year-end. Fed policy decisions (FOMC meetings on Sept. 20-21, Oct. 31 - Nov. 1, and Dec. 12-13) may be the driving factor of market returns in the 4th quarter.

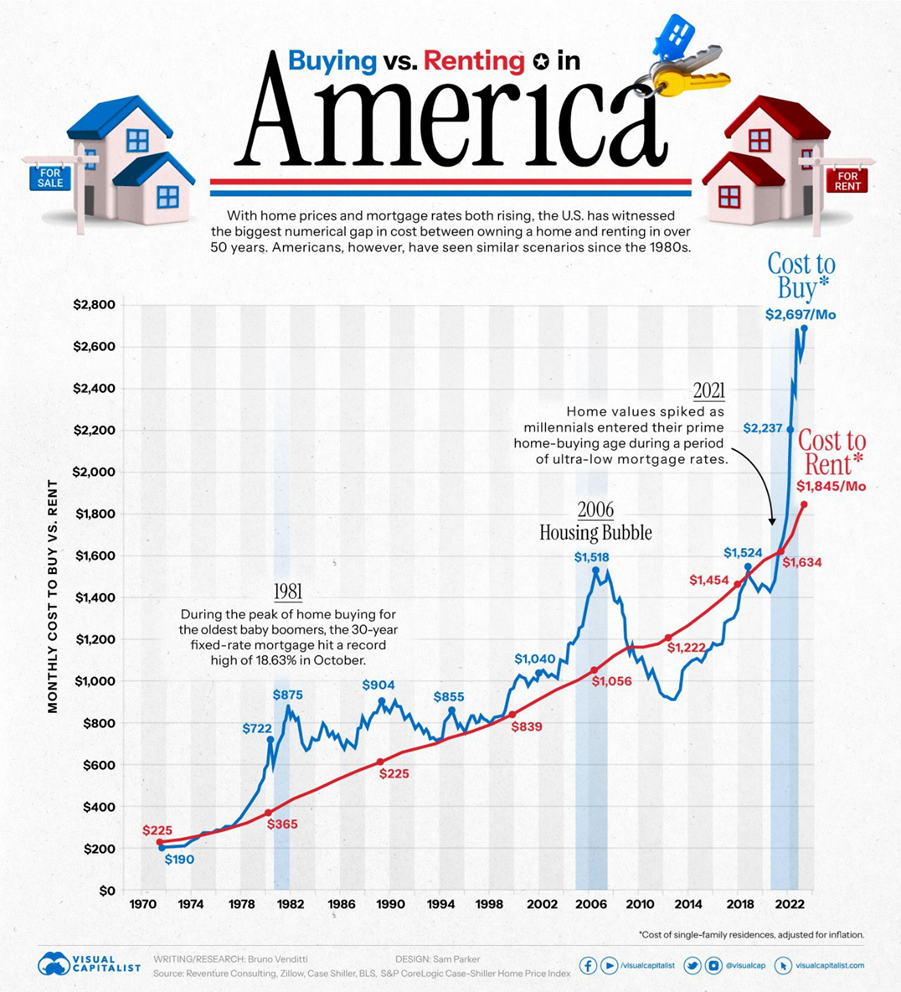
The Monthly Cost of Buying vs. Renting a House in America

“With home prices and mortgage rates both rising, the U.S. is now witnessing the biggest numerical gap in the monthly cost between owning a home and renting in over 50 years.


Americans, however, have seen similar scenarios occur since the early 1980s.


Today’s chart uses data from Reventure Consulting to highlight the cost of buying vs. renting a single-family residence in the U.S. since 1970, adjusted for inflation.


In August 2023, mortgage rates rose to the highest level in 23 years, with the national average 30-year fixed mortgage hitting 7.48%.


As a result, the median rent in America is approximately $1,850 per month, about 30% cheaper than the median cost to buy, standing at $2,700 per month. This gap represents the largest difference between renting and buying in U.S. history.


While the difference was less than $200 in 2022, in 2023 the gap surpassed $800.


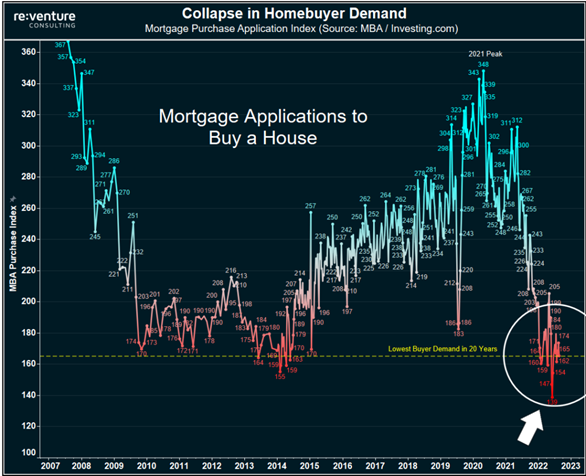
Many buyers, particularly those seeking their initial home purchase, have now been priced out of the market with concerns that they cannot afford home ownership. As a result, mortgage applications for home purchases have hit their lowest point in 20 years:”

As a simple guy who loves charts, the folks at Visual Capitalist do it the best. And, I really enjoyed this look back at buying vs. renting a home and how generational booms have likely impacted cost dislocations.


The recent spike in interest rates is delaying a generation of peak home-buying demand. Of course, the supply side has also been affected by the underdevelopment of housing post-Great Financial Crisis, institutional buyers, and short-term rentals. It’s going to be a case study that ripples through the housing market for years.

Read More
 

Graph of the Week

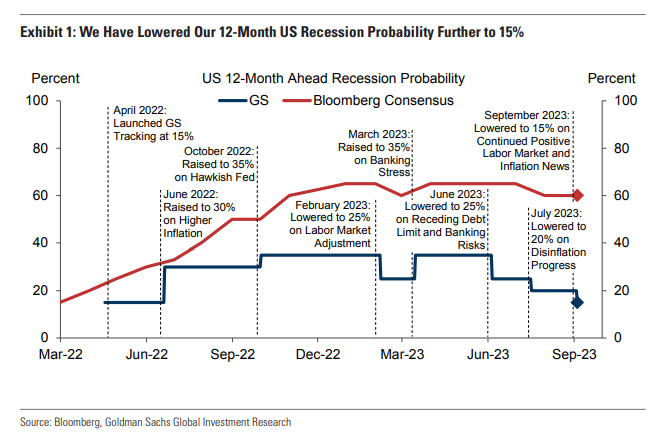
Goldman cut its 12-month probability of recession again to 15%. It was 35% as recently as last March. However, they are still lower than the pessimistic group of Street banks and economists polled by Bloomberg.

Tweet (or maybe X) of the Week

Thanks for reading. Have a great weekend!


Guidance for today. Growth for tomorrow.


RBGWA - Logo - Full Color.jpg

Tim Ellis, CPA/PFS, CFP®

CIO and Wealth Advisor

RBG Wealth Advisors

O: 901.244.2891 | C: 662.444.1415

E:  tellis@rbgwa.com

A:  5100 Wheelis Dr., Ste. 211, Memphis, TN 38117

W: rbgwa.com

LinkedIn  Twitter  Facebook

RBG Wealth Advisors LLC is a registered investment adviser. Information presented is for educational purposes only and does not intend to make an offer or solicitation for the sale or purchase of any specific securities, investments, or investment strategies. Investments involve risk and, unless otherwise stated, are not guaranteed. Be sure to first consult with a qualified financial adviser and/or tax professional before implementing any strategy discussed herein. Past performance is not indicative of future performance.