| | Volume 41 | October 2026 (Q4) | | Each quarter, I like to share a few personal thoughts, lessons, or experiences from life and business. Sometimes they connect directly to financial planning, and sometimes they are simply things that have been on my mind lately. | | |
A Lot Can Change In A Year
Something I’ve been reminded of this year is just how quickly life can change.
We all make plans and set goals for ourselves. Some are a little spontaneous and short-lived, and some are serious. We plan where we want to live, when we want to retire, how much we want to save, what our careers might look like, and what we hope the next few years will bring.
But life rarely follows the exact plan we had in mind.
Sometimes the changes are exciting. You get married. You have a child or two. You adopt a pet. You decide to go back to school, change careers, travel more, or pursue a goal you never really considered before like running a half-marathon!
Other times, life makes the decision for you. A close family member passes away. A marriage ends. A major health diagnosis comes up. The car breaks down or the A/C decides to stop working during the worst part of the Summer.
Or sometimes, you just simply change your mind.
I recently met with a retired client for their annual Medicare review. During our conversation, he was excited to let me know that they had decided to sell their house, buy an RV, and travel around the country for the foreseeable future. Because of this, both he and his wife wanted to both apply for a Medicare Supplement plan (and choose a Part D plan) to make it easier to use doctors around the country.
That obviously wasn't something we had discussed years ago when planning for retirement, but their priorities changed. Their retirement plan now looks a little different because their life looks different.
I think that's an important reminder that a retirement plan isn't supposed to lock you into one path forever. It's supposed to help support the life you want to live.
Sometimes that means increasing your savings. Sometimes it means changing investments, adding or adjusting insurance, reevaluating retirement timing, helping a family member, spending more on experiences, or completely rethinking what retirement looks like.
That's one of the reasons I believe planning should be an ongoing conversation instead of something you do once and forget about. Every so often, it's worth asking yourself a simple question: Does the plan I made then still fit the life I'm living now?
If the answer has changed, that's okay. Your plan can change too.
| | I use this section to break down a simple financial planning idea, strategy, or concept that may be worth understanding. The goal is to keep it practical, easy to follow, and relevant to everyday financial decisions. | |
What is a CD Ladder?
A recent client conversation reminded me of a simple strategy that doesn’t get talked about very often: laddering CDs (Certificate of Deposit).
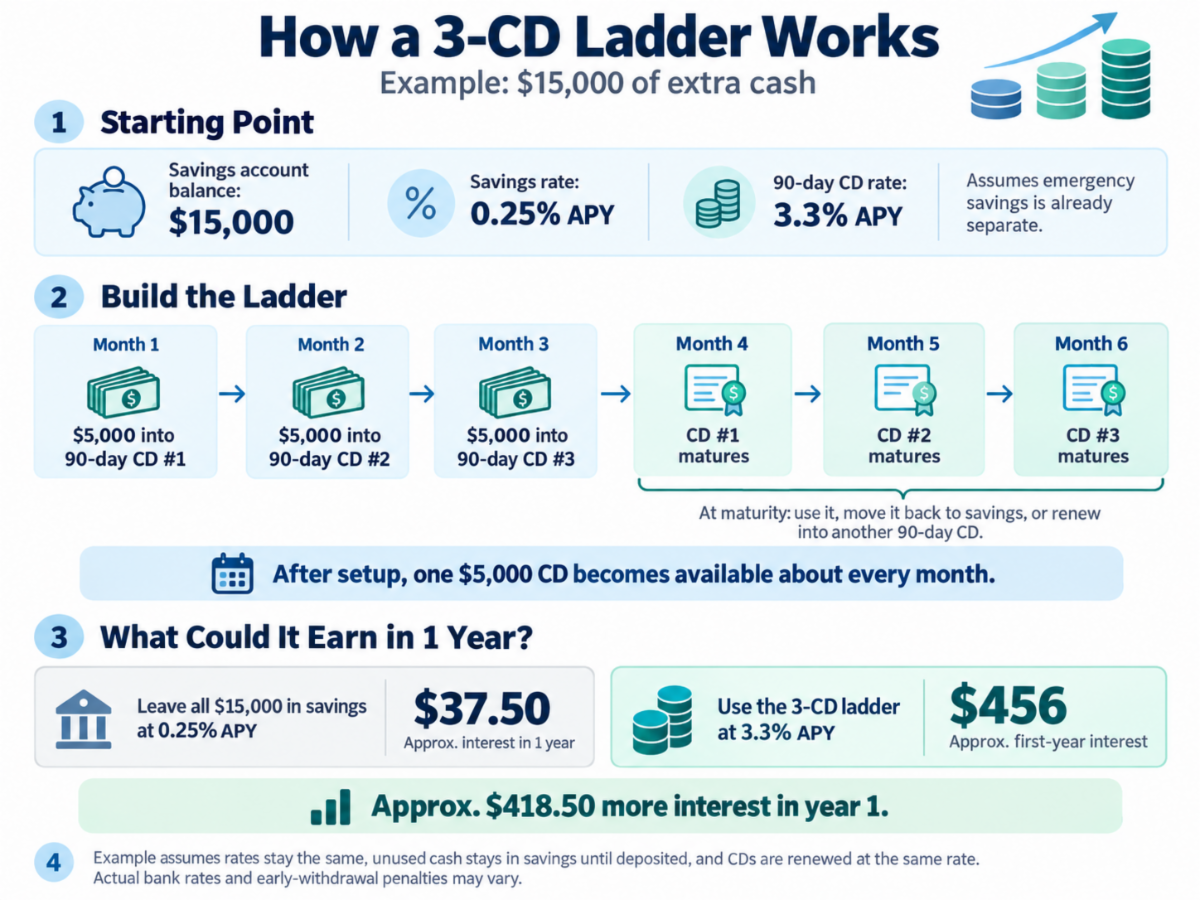
Let’s say someone has an extra $15,000 sitting in a savings account earning 0.25% APY (and they already have a separate emergency fund).
At this hypothetical bank, a 90-day CD is currently paying 3.3% APY.
Instead of putting all $15,000 into one CD and locking it up at the same time, they could stagger three separate CDs:
-
Month 1: $5,000 into a 90-day CD
-
Month 2: $5,000 into another 90-day CD
-
Month 3: $5,000 into the final 90-day CD
Once all three are established, one $5,000 CD will mature every month going forward. At each maturity, they can use the money if needed, move it back into their savings, or renew it into another 90-day CD at whatever rate is available.
| |
So, what’s the difference?...
If the entire $15,000 stayed in the 0.25% savings account for one year, it would earn approx. $37.50 in interest.
If that same $15,000 were continuously earning 3.3% APY, it would earn about $495 in interest. A difference of over $400 in one year!
The goal isn’t to chase huge investment returns. It’s to ask yourself whether some of the cash you don’t need immediately could be working a little harder.
Look, CDs aren’t right for every situation. You still want accessible emergency savings, CDs can have early-withdrawal penalties, and future CD rates could be higher or lower when it’s time to renew.
But for someone keeping more cash in savings than they realistically need in the short term, a CD ladder can be a simple strategy worth understanding.
| | I use this section to highlight an important Medicare update, rule, or trend that may affect current or future beneficiaries. The goal is to keep you informed without overwhelming you with Medicare jargon. | |
AEP Is Here, But Medicare Is Changing Too
Medicare’s Annual Enrollment Period runs from October 15 through December 7, but this year I think the real conversation is how the Medicare landscape continues to evolve.
In 2027, we’re seeing some Medicare Advantage plans reduce service areas, tighten provider networks, adjust premiums and cost-sharing, and scale back some of the “extra” benefits people have become accustomed to.
At the same time, Medicare itself keeps introducing new programs and updates.
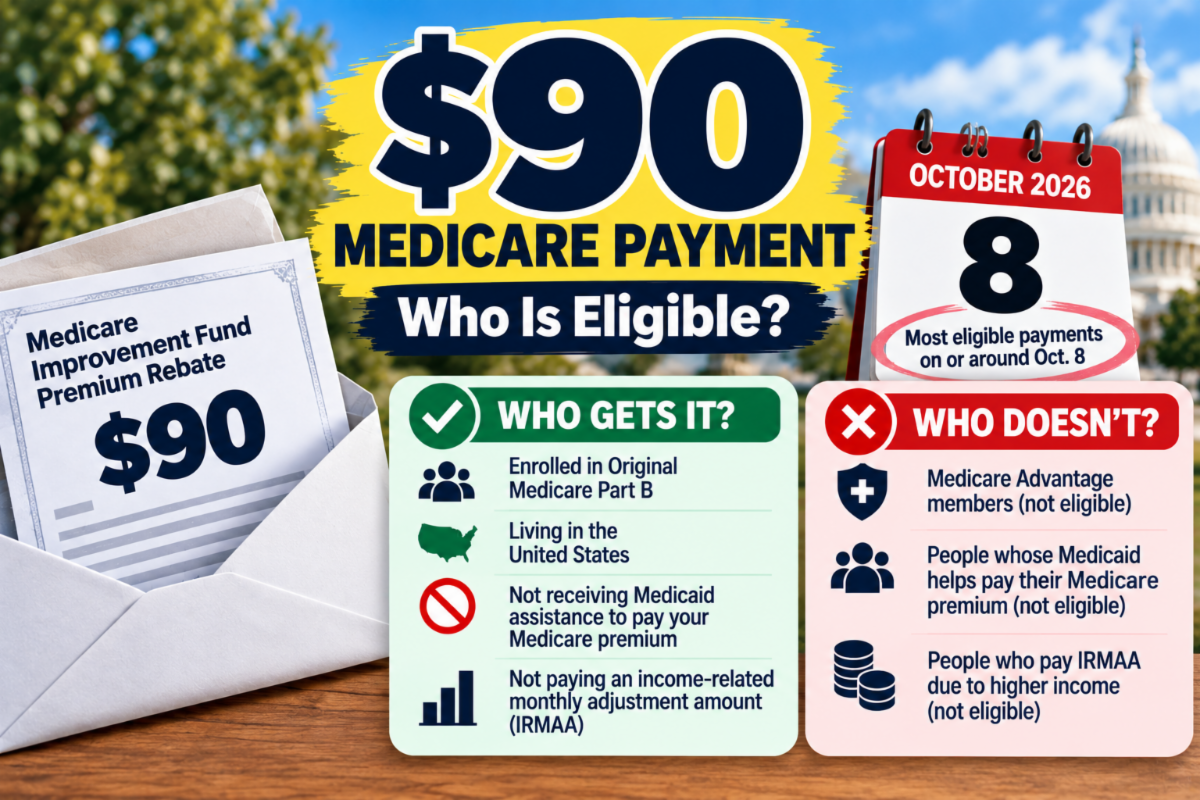
For example, most recently, some Original Medicare beneficiaries became eligible for a one-time $90 Medicare premium rebate (pictured below) in October.
| |
The Medicare Prescription Payment Plan now allows people with Part D coverage to spread costs throughout the year.
There’s also the new Medicare GLP-1 Bridge, which gives some beneficiaries access to select GLP-1 medications for weight management at a lower cost through the end of 2027.
That’s why I believe having a trusted Medicare resource matters more than ever. A good Medicare agent shouldn’t just help you enroll in a plan once and disappear. They should help you understand what’s changing, review how those changes affect your doctors, prescriptions and budget, and keep you informed when new Medicare programs or benefits are introduced.
If you’re already one of my Medicare clients, that ongoing relationship is exactly what I want to provide.
| | |
Each quarter, I take financial (primarily retirement, insurance and Medicare) questions from clients, subscribers and followers.
To individuals who submit questions (if desired), I will reply via email with my answer right away. Additionally, I will highlight 1-3 of the submitted questions and answers in the following quarter's newsletter.
| |
Question #1: How do I know if I’m saving enough for retirement?
Answer: There is not a perfect answer that simply works for everybody.
How much you should save depends on things like your age, income, pension or Social Security benefits, current savings, debt, retirement timeline, the lifestyle you're comfortable living now and the lifestyle you want in retirement.
That sounds like a lot, but that's because it is and it all goes into figuring our your "enough".
Rather than getting discouraged by a big dollar amount or percentage, I usually think the most important thing is to start with an amount you can comfortably maintain and increase it over time.
One simple approach is to create a routine of increasing your contribution by $10 to $20 per month each year. Then, when you have more room in your budget, such as after paying off a debt or receiving a larger raise, you can make a bigger increase. Over time, those smaller and larger adjustments can add up to meaningful progress.
---
Question #2: Can I take the money in my TRS account and invest it somewhere else?
Answer: If you are still working in a TRS-covered position, the answer is generally no. The money in your account is tied to the TRS pension system while you remain employed.
If you eventually leave TRS-covered employment, you may have the option to withdraw from your account and/or rollover the funds elsewhere. But doing that can mean giving up the service credit connected to those contributions which means giving up a future lifetime pension.
That is why I usually encourage educators to think of TRS and personal retirement savings as two different pieces of the puzzle. TRS can provide future pension income, while accounts such as a 403(b), 457(b), or IRA can give you additional retirement savings to help fill the income gap.
| 📝 Please note that this information is for educational purposes only and should not be considered investment or financial advice. It is always recommended that you consult with a qualified and licensed professional before making investment decisions. | | Articles shared below should not be considered advice nor are they necessarily endorsements by Zachary G. Espericueta. Any company, entity, or product discussed is not guaranteed to be the right fit for you. It is always encouraged to discuss these topics with a trusted advisor and/or tax expert. | | Kiplinger: Don't Leave Your Family Guessing | |
"How much do you know about your family's life insurance and other major financial decisions? Talking about it will create clarity now, before it becomes urgent."
Read Article
| | | CMS: CMS Proposes Stronger Medicare Advantage Network Protections | |
"The CMS proposal, released October 16, 2026, would require Medicare Advantage plans to verify and update provider directories at least every 90 days."
Read Article
| | | |
As a reminder, I help individuals with:
-
Retirement plans + rollovers (IRA, 403b, Roth, etc.)
-
Life insurance (Term, permanent, and final expense)
-
Medicare insurance (Supplement plans and Medicare Advantage)
-
Ancillary Plans (Dental/Vision plans, Cancer coverage, Copay Reimbursement, etc.)
| | Do you know someone who could use my help? | |
You could earn up to $25 for each qualified referral. Here's how:
- Click "Submit A Referral" below
-
Fill out the Google form and pass along my contact info.
- I’ll contact your referral to schedule a meeting.
- Once your referral is qualified, I’ll send a thank-you reward!
If you know someone who could use some guidance, I’d be happy to help.
| | What To Do In San Antonio | | If you’re looking for something to do around San Antonio these next few months, here are one or two local events worth checking out! | | |
SAMMinistries Empty Bowls
"This beloved community event showcases the incredible talent of local artisans, live music, a raffle, food, fun, and fellowship, all while increasing awareness of homelessness and food insecurity."
When: Sun., Nov. 15th from 11am-2pm
Where: UTSA Southwest Campus, 300 Augusta St. San Antonio, TX 78205
Price: Free to Enter
🔗 More Details
| | | |
All articles, tips, and other material is for informational purposes only, and should not be considered as investment advice or a recommendation of any particular annuity product, security, strategy, or investment product. All products & investments contain risk and may lose value. Individuals should seek professional advice before making any financial decision.
We are not responsible for the availability of any external sites or their content, and we don't adopt, endorse or nor are we responsible or liable for any such sites or content, including advertising, products or other materials, on or available through such sites or resources.
| | | | |