|
What happened last week?
A significant of amount of news was focused on the U.S. midterm elections, and the strong results achieved by the Democrats. Not all results had been tabulated, but by Tuesday night it was clear that the House of Representatives and Senate will be controlled by Democrats beginning in January.
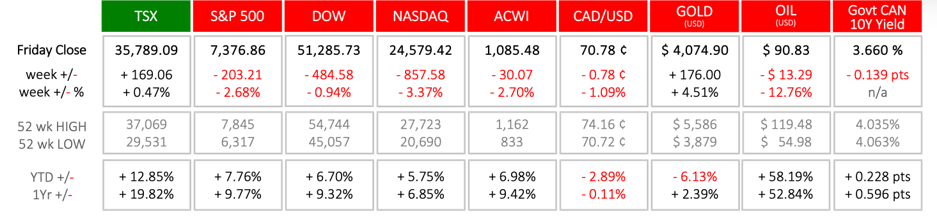
Equity markets greeted the news positively on Wednesday before a steep drop on Thursday before recovering slightly on Friday. The election results added to growing concern for Artificial Intelligence (AI) companies. Several successful candidates campaigned against AI and data centers, and the sell-off last week may have some investors contemplating the concentration within their portfolio. CNN and diversifying
On Thursday the governing Liberals tabled a budget through Finance Minister Champagne and Prime Minister Carney. In addition to the 500+ page budget, a summary was also published. Proposed changes include eliminating the administrative conversion of RRSPs to RRIFs and different treatment for dividends for Canadian corporations. Once the legislation is passed, more details will emerge.
In economic news, Canadian and American job data were released on Friday morning.
-
StatsCan reported that employment rose little in October (-4,700; 0.0%) and the unemployment rate rose 0.2 percentage points to 6.7%.” Employment fell in wholesale and retail trade, while increasing in construction and education. StatsCan LFS release
-
The U.S. Bureau of Labor Statistics’ Employment Situation Summary announced that total nonfarm employment increased by 165,000 in October, while the unemployment rate was unchanged at 4.1 percent. BLS ESS release
Both the Bank of Canada and Federal Reserve seek low and predictable inflation and maximum employment. Canada has heightened inflation and slow jobs growth, both of which cannot be addressed with the same monetary policy action. The Fed could raise rates to temper inflation while slowing its robust employment market. The likelihood that the Fed will increase interest rates at the next decision scheduled for December 9th is hovering in the 75-80% range. CME FedWatch tool
What’s ahead for this week and beyond?
In Canada, building permits, capacity utilization, manufacturing and wholesale sales, leading index and the Bank of Canada’s Summary of Deliberations from their recent rate hike will be released.
In the U.S., building permits, existing home sales, consumer inflation expectations, wholesale trade and inventories, Consumer Price Index (CPI) and Producer Price Index (PPI) will be announced.
Globally, Japan’s leading index, coincident indicator, household spending, lending and PPI, China’s imports, exports and trade balance, CPI and PPI, and the Eurozone’s investor confidence, economic forecast, employment, gross domestic product (GDP) and trade balance will be released.
|