hud certified housing counselor A housing counselor through a Housing and Urban Development (HUD)-approved agency who is specially trained and certified by the government to help you assess your financial situation, evaluate options, and make a plan to get
did you know? checking your credit report You can request your credit report weekly for free from the three credit reporting companies.
interactive intersection zogo financial education Use access code “ROADHOME” for CHFA’s free financial education app Zogo and earn gift cards while you learn.

understanding how the 5 cs of credit could impact the loan approval process when you’re thinking about buying a home

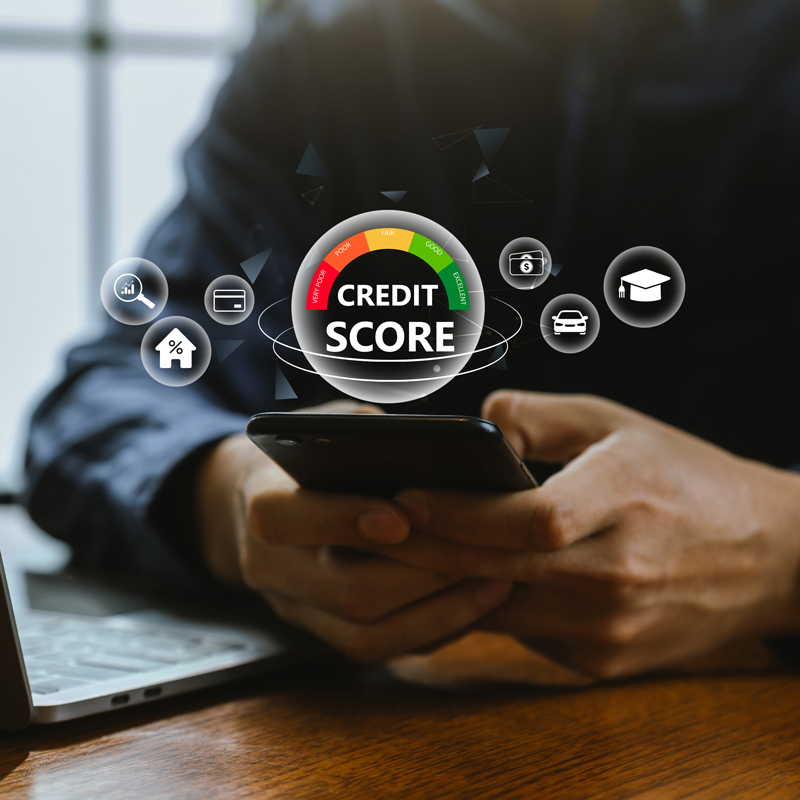
A pair of hands holding a phone with a credit score graphic with red yellow and green zones.

When you are thinking about buying a home it’s important to understand the loan approval process. Part of that is knowing how lenders assess your creditworthiness for a mortgage loan. Lenders generally use what is called the 5 Cs of Credit which combined make up your credit profile.


Character: As a lender reviews your mortgage loan application, they’re looking for clues into your financial character. This includes things such as a record of you paying your bills on time and a continuous employment history.

Improving your credit character:


  • Check your credit report regularly to ensure there isn’t any incorrect information.
  • Consider setting up automatic payments on recurring bills to ensure they are paid on time each month.


Capacity: A lender will want to know if you can repay your loan. They will look at all your outstanding debts and compare that total to your before-tax income. This is called your debt-to-income (DTI) ratio.


Improving your capacity:


  • Look at how you can pay down your debt.
  • Consider ways you can have stable income to show your pay will continue to be consistent.


Capital: A lender will look at the amount of money you are prepared to put toward your home purchase. They may also look at your savings and any other investments you have.


Improving your capital:


  • A large down payment may not be necessary to buy a home. Some down payment requirements are as low as 3 percent. Plus, there are down payment assistance options that you may qualify for from CHFA and other organizations.


Collateral: A lender may consider the asset you own and are pledging as collateral. It gives a lender some reassurance that if you can’t repay your debt, the lender can sell your asset to get their money back.


Conditions: A lender may look at external factors beyond your personal situation such as economic and market conditions and how those could impact your finances in the future. They will also look at the conditions and terms that come with the loan. 


You can find additional resources to help you understand credit on CHFA's website (PDF). 

support for women to become first-time homeowners

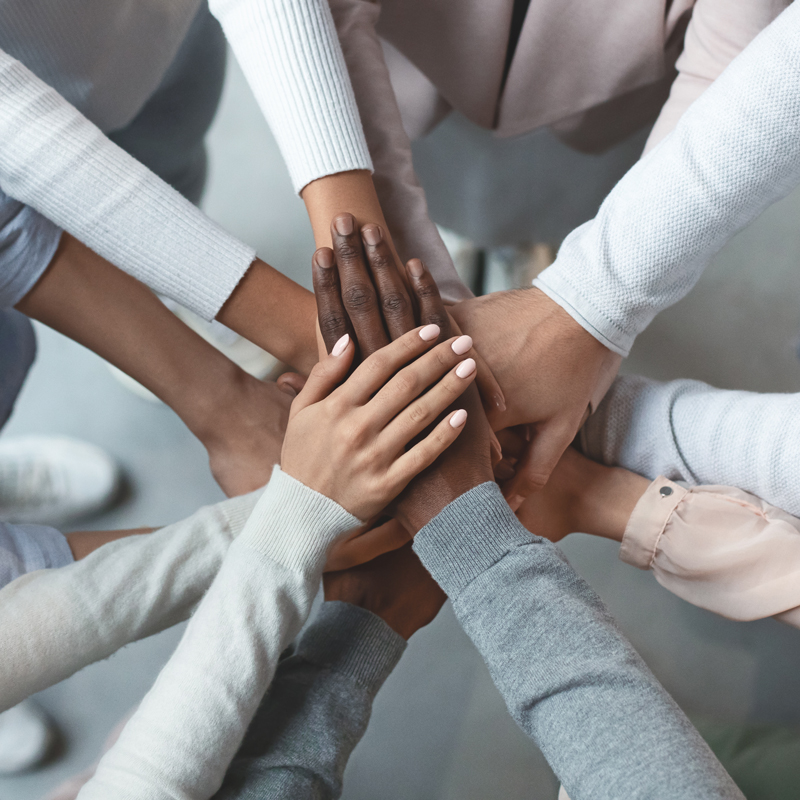
a circle of hands piled one on top of another.

CHFA was proud to support Project I See You with a $100,000 donation to support women in Colorado on their journey to homeownership. Project I See You is a 501(c)3 nonprofit dedicated to helping women take ownership over their lives and radically transforming the communities around them. The nonprofit reaches women across diverse cultural, racial, and socioeconomic barriers. Its Shared Power Initiative supports women to become first-time homeowners through grants and a network of support. Find out how to apply for Project I See You homeownership funds here.

Online resources

-

Colorado Housing and Finance Authority


www.chfainfo.com


This eNewsletter may contain links to other websites or third party materials. Links to external or third party websites or materials are provided solely for your convenience. The presence of a link does not imply any endorsement of the third party material, the website, its content or any association with the third party or website's operators by CHFA. Third-party websites or materials may be governed by their own privacy policy and terms of use, and the third party is solely responsible for the content and offerings presented on its website or in its materials. CHFA makes no representation and accepts no responsibility or liability regarding the accuracy, quality, safety, suitability or reliability of any third party material(s), external website or the content or materials of such websites. Use of linked sites is strictly at your own risk. 

With respect to its programs, services, activities, and employment practices, Colorado Housing and Finance Authority prohibits unlawful discrimination against applicants or employees on the basis of age 40 years and over, race, sex, sexual orientation, gender identity, gender expression, color, religion, national origin, disability, military status, genetic information, marital status or any other status protected by applicable federal, state or local law. Requests for reasonable accommodation, the provision of auxiliary aids, or any complaints alleging violation of this nondiscrimination policy should be directed to the Nondiscrimination Coordinator, 1.800.877.2432, TDD/TTY 800.659.2656, CHFA, 1981 Blake Street, Denver, Colorado 80202-1272, available weekdays 8:00am to 5:00pm MT.

 
Facebook  Instagram  LinkedIn  X