|
Good morning on this best day of the week, Wednesday, from your Hometown Lender,
Rate sheets today should be better as mortgage bonds start the day with some really nice gains as a solid blue wave sweeps the nation. Whatever your political outlook or affiliations, the reality is markets like what they’re seeing, and it’s helping rate sheets today.
From a higher and better view:
Washington supplied the drama. The economy supplied the homework. Today’s assignment: separate a market reaction from a lasting change in borrowing costs. Your mortgage payment does not get an election-night concession speech.
Quick Snapshot
-
Politics: Reuters reports Democratic control of both congressional chambers based on media projections; certification is separate. [3]
-
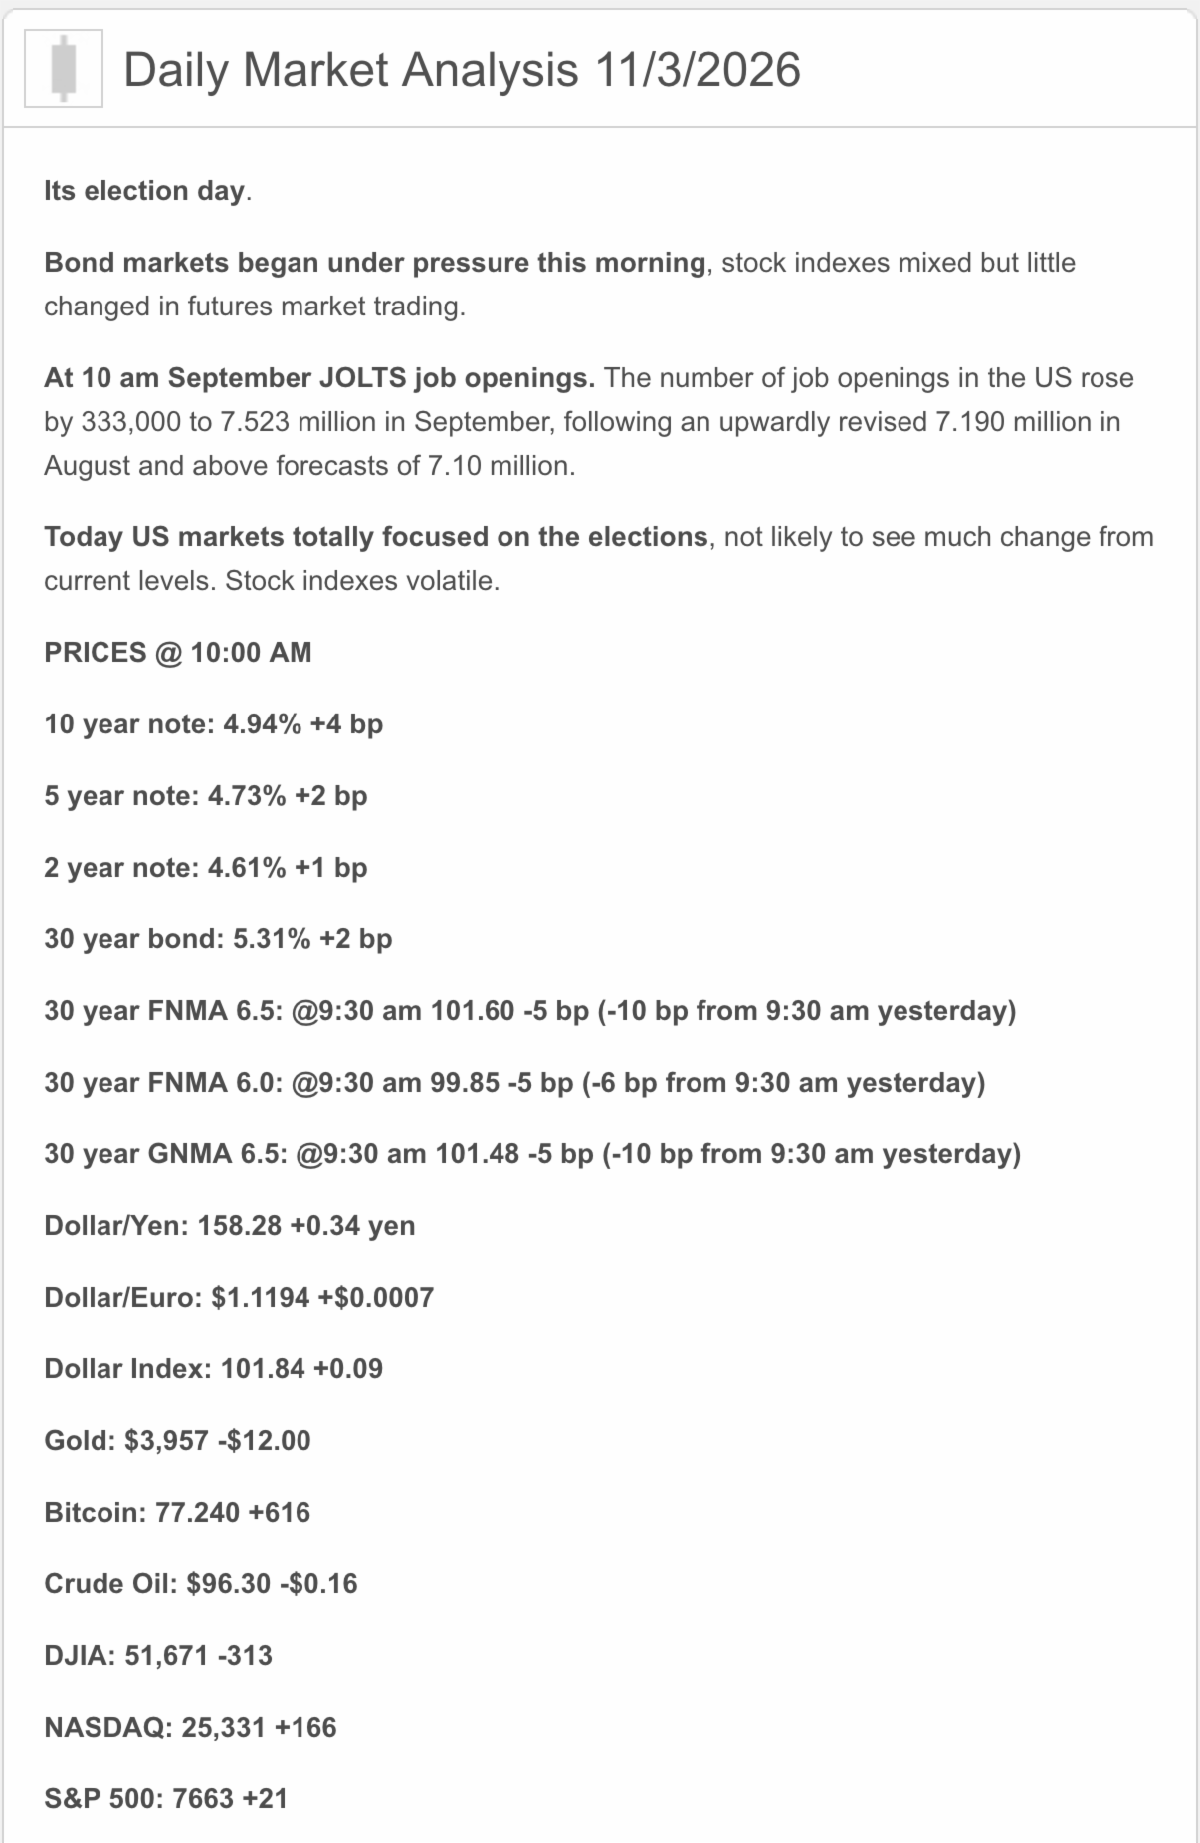
Bonds: MND’s Wednesday dashboard shows the 10-year Treasury at 4.937%, down 3.3 basis points, and UMBS 6.0 at 100.05, up 0.30. Intraday; exact quote time unavailable. [1]
-
Mortgage benchmark: Tuesday’s MND 30-year fixed index was 7.30%. [1]
1 | What Hit This Morning
ADP reported 86,000 additional private-sector jobs in October. Its report is distinct from Friday’s government employment release. [2] ISM services registered 54.5, down from 54.9 but still expanding. The prices index eased to 73 from 74—less heat, still plenty of steam. [7]
My read: activity remains resilient enough that one softer headline should not be mistaken for an all-clear on inflation.
2 | Fed Watch
The Fed held its policy range at 3.75%–4.00% on October 28. Two dissenters preferred a quarter-point increase. That is a pause with disagreement, not a promise of cuts. [4]
Friday’s October jobs report arrives November 6 at 5:30 a.m. Pacific. Watch wages, unemployment and revisions alongside the headline payroll number. [5] Mortgage rates reflect longer-term bond pricing and lender conditions; the Fed’s overnight rate is only part of that story.
3 | Where Mortgage Rates Actually Are
MND’s completed November 3 benchmarks: 30-year fixed 7.30%; 15-year fixed 6.91%; 30-year jumbo 7.45%. These national indexes are not Noble loan offers or APRs. [1]
Today’s stronger mortgage bonds may help lender pricing, but that transmission is neither instant nor uniform. Compare written quotes using the same loan, points, fees and lock period. A smaller advertised rate can come with a larger receipt.
4 | Housing Market Check
MBA’s survey for the week ending October 30 showed applications down 1.2%, purchase applications down 2% seasonally adjusted, and refinance activity roughly flat. [6]
That suggests affordability remains a hurdle. For buyers, evaluate local inventory and seller flexibility. For agents, discuss credits and financing early; a national application report cannot tell us what one neighborhood will negotiate.
5 | Political Backdrop & Fed Independence
Projected divided government changes the legislative outlook; it does not automatically change existing tax or housing policy. [3]
My interpretation: spending negotiations and oversight deserve attention, while any specific policy outcome remains uncertain. Campaign promises need legislation, implementation and time before they belong in a household budget.
Political pressure also should not be treated as a guaranteed Fed decision. The latest policy statement still centers on inflation and employment. [4]
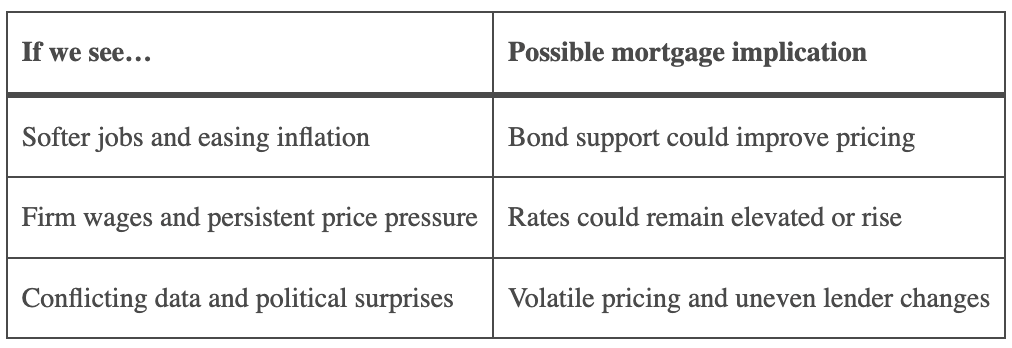
6 | Rate Scenarios
These are possibilities, not forecasts.
|