Introducing Our New Associate Attorney |
|
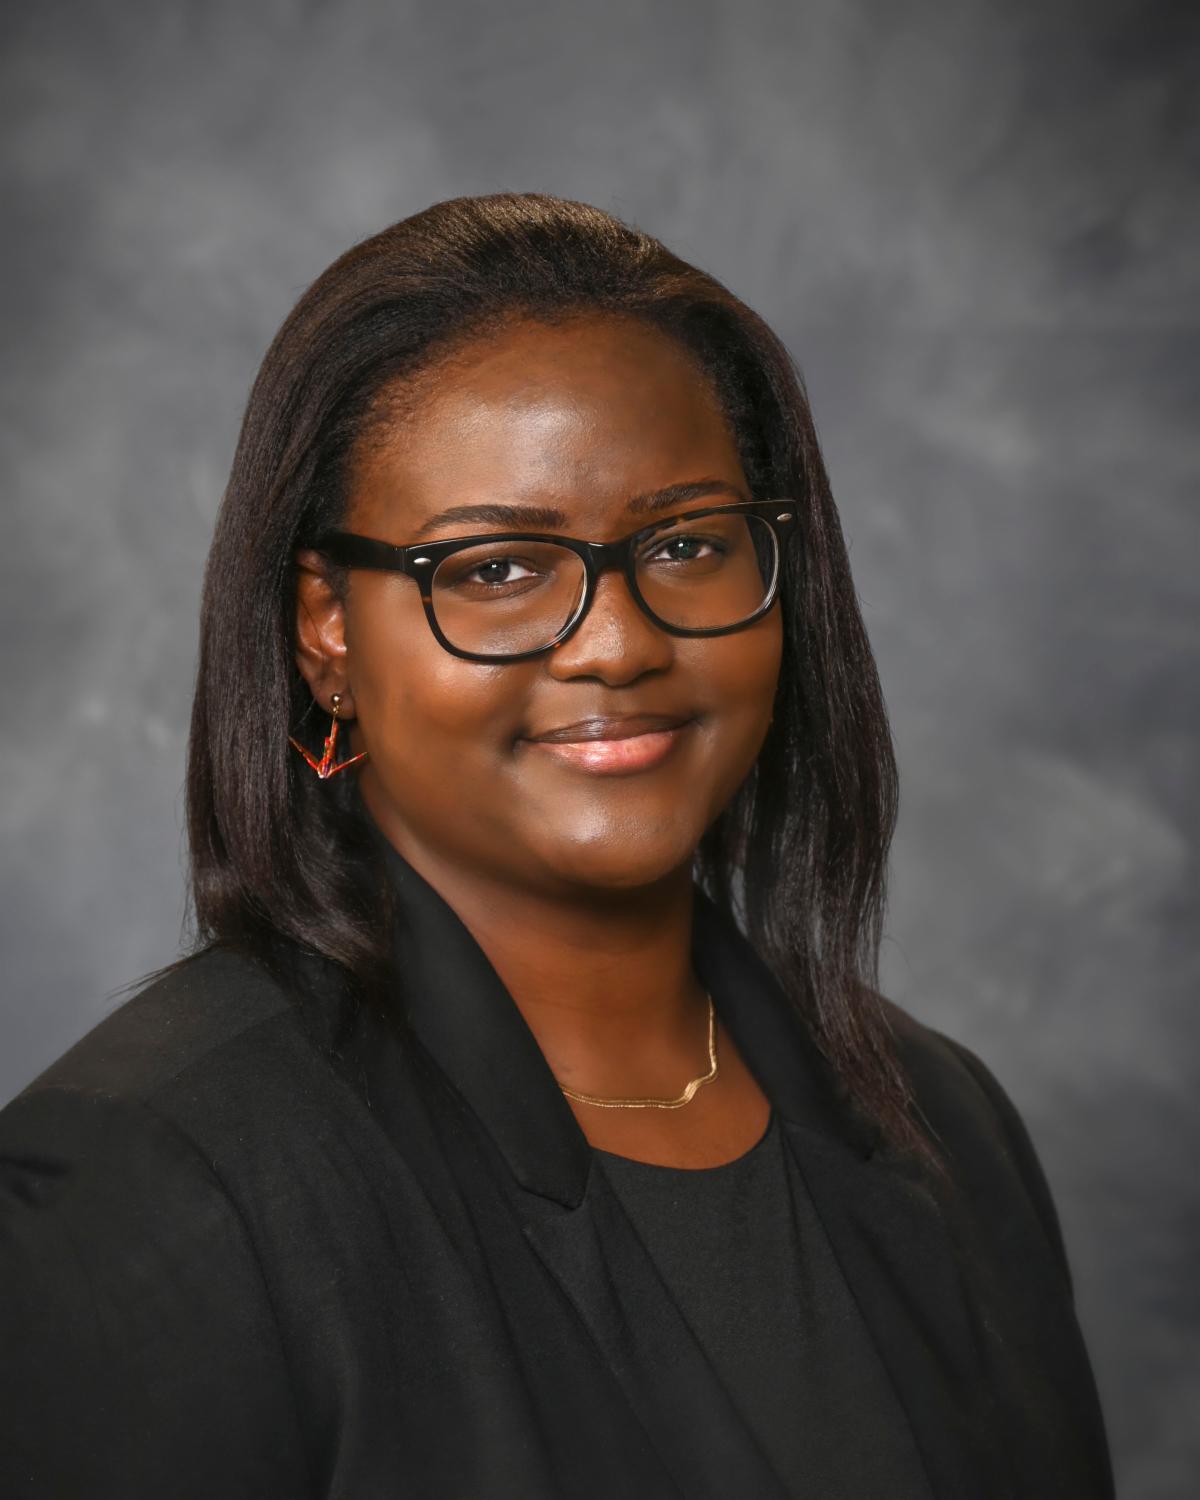
We are pleased to introduce our new associate attorney, Celyn O. Coker. Ms. Coker earned her bachelor’s degree in Sociology from the University of San Francisco and her Juris Doctorate from the University of San Francisco, School of Law.
During law school, Ms. Coker worked in the Frank C. Newman International Human Rights Law Clinic. Through the clinic, Ms. Coker attended the sixty-third session of the Commission on the Status of Women in New York (2019) where she advocated for the importance of sustainable educational programs that do not require foreign oversight.
While at USF, Ms. Coker worked as a legal extern at Baker McKenzie in Hanoi, Viet Nam (2018). Her developing practice includes complex and mass tort litigation.
|
Labor & Employment Updates
President Biden Announces OSHA Standards Requiring COVID-19 Vaccinations or Weekly COVID Test
On September 9, 2021, President Biden announced that in an effort to stop the spread of COVID-19, companies with 100 or more workers are required to ensure their employees are either vaccinated from COVID-19 or are receiving weekly testing.
In addition, employers must provide employees time off to get vaccinated and to recover from side effects.
This comes immediately after President Biden signed an executive order and instructed the U.S. Department of Labor’s Occupational Safety and Health Administration (OSHA) to develop a temporary emergency standard. The temporary emergency standard is expected to go through an expedited review process and be published in the upcoming weeks. Once the standards are in effect, OSHA will have the authority to fine businesses up to $14,000 per violation.
Our team will continue to follow OSHA’s temporary emergency standards and provide an update once the rule is in effect. We would recommend that employers have a plan to comply with the vaccination or weekly testing requirement. Many private employers with less than 100 employees are also implementing such requirements. If you have any questions about how the new standards may affect your business, contact a member of our employment law team: Amanda L. Riddle, Steven M. Berki, Sumble Manzoor, Max Neiman and Daniel G. Pohoretsky.
“Me Too” Expansion: California Legislatures are Waiting on Governor Newsom to Sign SB 331
California Legislatures recently passed Senate Bill (SB) 331 and placed the Bill on Governor Newsom’s desk for signature. While the Governor has until October 10, 2021 to sign the Bill, policy experts expect him to announce his decision shortly.
SB 331, also known as the “Silenced No More Act,” seeks to prohibit the use of non-disclosure agreements to settle harassment or discrimination claims in the workplace. As a result, employers would be prohibited from requiring an employee to sign an agreement that denies the employee the right to disclose information about unlawful acts in the workplace. Such acts include workplace harassment or discrimination. In addition, the Bill will prohibit employers from including provisions in a severance or settlement agreement that would restrict or prevent the disclosure of factual information of claims related to all forms of harassment, discrimination, and retaliation. Therefore, employers would be unable to include any terms or provisions related to discrimination or harassment based on race, religion, color, national origin, ancestry, physical disability, mental disability, medical condition, genetic information, familial status, sex, gender, gender identity, gender expression, age, sexual orientation, or veteran and military status in any agreement of any kind.
We will continue to track the Bill and update you when the Governor takes action. In the meantime, it is critical that employers are being compliant with all other California laws regarding workplace harassment or discrimination and settlement agreements. If you have any questions or concerns regarding your Company’s harassment and discrimination policies or what provisions are permitted in a severance or settlement agreement, contact a member of our employment law team: Amanda L. Riddle, Steven M. Berki, Sumble Manzoor, Max Neiman and Daniel G. Pohoretsky.
ICE Further Extends its Form I-9 Flexibility
The U.S. Immigration and Customs Enforcement (“ICE”) announced that it will extend the agency’s I-9 flexibility until December 31, 2021. You may read the announcement here.
As a reminder, employees hired on or after April 1, 2021, who work exclusively in a remote setting due to COVID-19 related precautions, are temporarily exempt from the physical inspection requirements associated with Form I-9. This flexibility permits employers to inspect I-9 documents, including an employee’s identity and authorization documents, through video link, fax, and/or email.
Employers should be aware that this flexibility only applies to employers and workplaces that are operating 100% remotely. As such, the flexibility will only continue until an employee undertakes non-remote employment on a regular, consistent, or predictable basis, or until the flexibility is terminated, whichever is earlier. Therefore, once the Company requires its employees to be physically present at the workplace, it must prepare to conduct in-person verification of the I-9 documents. If you have any questions about complying with this flexibility or Form I-9, contact a member of our employment law team: Amanda L. Riddle, Steven M. Berki, Sumble Manzoor, Max Neiman and Daniel G. Pohoretsky.
|
How the Latest Tax Proposals may Affect Your Estate Plan
On Sept. 13, 2021, the new Democrat tax plan was released by the House Ways and Means committee (the committee in the House of Representatives which takes the laboring oar in promulgating tax proposals). Although not yet enacted into law, the proposals are indicative of the types of changes that we might expect to see in some form.
Some highlights from the recent release:
Reduction of Estate, Gift, and GST Tax Exemptions as of January 1, 2022 Under current law there exists a lifetime exemption on estate, gift, and generation skipping transfer (GST) tax of transfers up to $11,700,000. This means you may gift during life, or after death up to $11,700,000 ($23,400,000 per married couple) without paying any gift, estate, or GST tax. Under current law, however, this exemption is set to revert to $5 million (indexed for inflation) beginning January 1, 2026. The proposed plan moves up the date of the reversion to January 1, 2022, at which time the exemption would be $6,020,000 ($5 million indexed for inflation).
Changes to Grantor Trust Rules For many years high wealth individuals have been using various forms of “Grantor Trusts” to remove assets from their taxable estate at death, but maintain some control over those assets during life. The proposals target these techniques in the following ways:
- Inclusion of grantor trusts in the estate of the grantor at death.
- Treatment of distributions from grantor trusts to beneficiaries during the grantor’s lifetime as gifts from the grantor.
- Gift treatment if grantor trust status is terminated during the grantor’s lifetime.
- Elimination of tax free transfers between Grantor Trusts and the Grantor.
These proposals together eliminate much of the wealth transfer techniques previously utilized to legally reduce estate and gift tax.
Conspicuously Not in Proposal - “Step-up in Basis” The Biden administration previously made two very troubling tax proposals: (1) the elimination of the “step-up” in basis of assets included in a decedent’s taxable estate on death, and (2) forced recognition of capital gains on death. These two proposals would eliminate the likely most universally beneficial and long-standing estate planning benefits available. The latest proposal, however, omits both controversial proposals. This is a good; however, these proposals could show up in later iterations of proposed legislation.
Additional proposals of interest:
- Increases to income tax brackets to high income earners.
- Increases to Capital Gains tax rates
- Additional “surcharge” (tax) added to high income earners with AGI over $5 million.
- Limitations on IRA benefits available to high income earners and IRAs holding significant assets.
Although we expect that final legislation may look substantially different from the current Ways and Means Committee proposals, nevertheless, they provide meaningful insight into upcoming changes, and provides an opportunity to consider your estate plan.
If you already have an estate plan, now is a perfect time to read through with the above proposals in mind; make sure it still matches your intentions. If you do not have an estate plan, now is the time to prepare one.
|
Community Partner Spotlight
Our firm actively supports many non-profit organizations in the Bay Area. In this edition, we want to draw readers’ attention to the Burlingame Community Education Foundation (BCE) . BCE is a non-profit, volunteer fundraising organization dedicated to enhancing the educational opportunities of the children of the Burlingame School District in kindergarten through eighth grade. Their annual fundraising provides the Burlingame School District with funds to help maintain important programs and staff in place, and offers a deeper investment in key areas. Our firm proudly sponsors the BCE Read-a-thon each year. Our managing partner, Amanda L. Riddle , is a Burlingame public school district parent.
|
|
Employment Law Litigation
When issues arise, our attorneys focus on early intervention to resolve problems within the business before the issue escalates ...
|
|
Business & Commercial Transactions
Since 1964, our firm has provided tailored advice to business clients of all sizes. From sole proprietorships to Fortune 500 companies ...
|
|
Probate & Trust Litigation
Along with the provision of estate planning legal services, we have extensive experience litigating matters resulting from estate disputes involving ...
|
|
Millbrae Office
700 El Camino Real
Millbrae, CA 94030
Phone: (650) 871-5666
Email: info@coreylaw.com
|
|
Half Moon Bay Office
625 Miramontes Street, Suite 106
Half Moon Bay, CA 94019
Phone: (650) 726-7578
Email: info@coreylaw.com
|
|
|
|
|
|
|