|
Good Monday morning from your Hometown Lender,
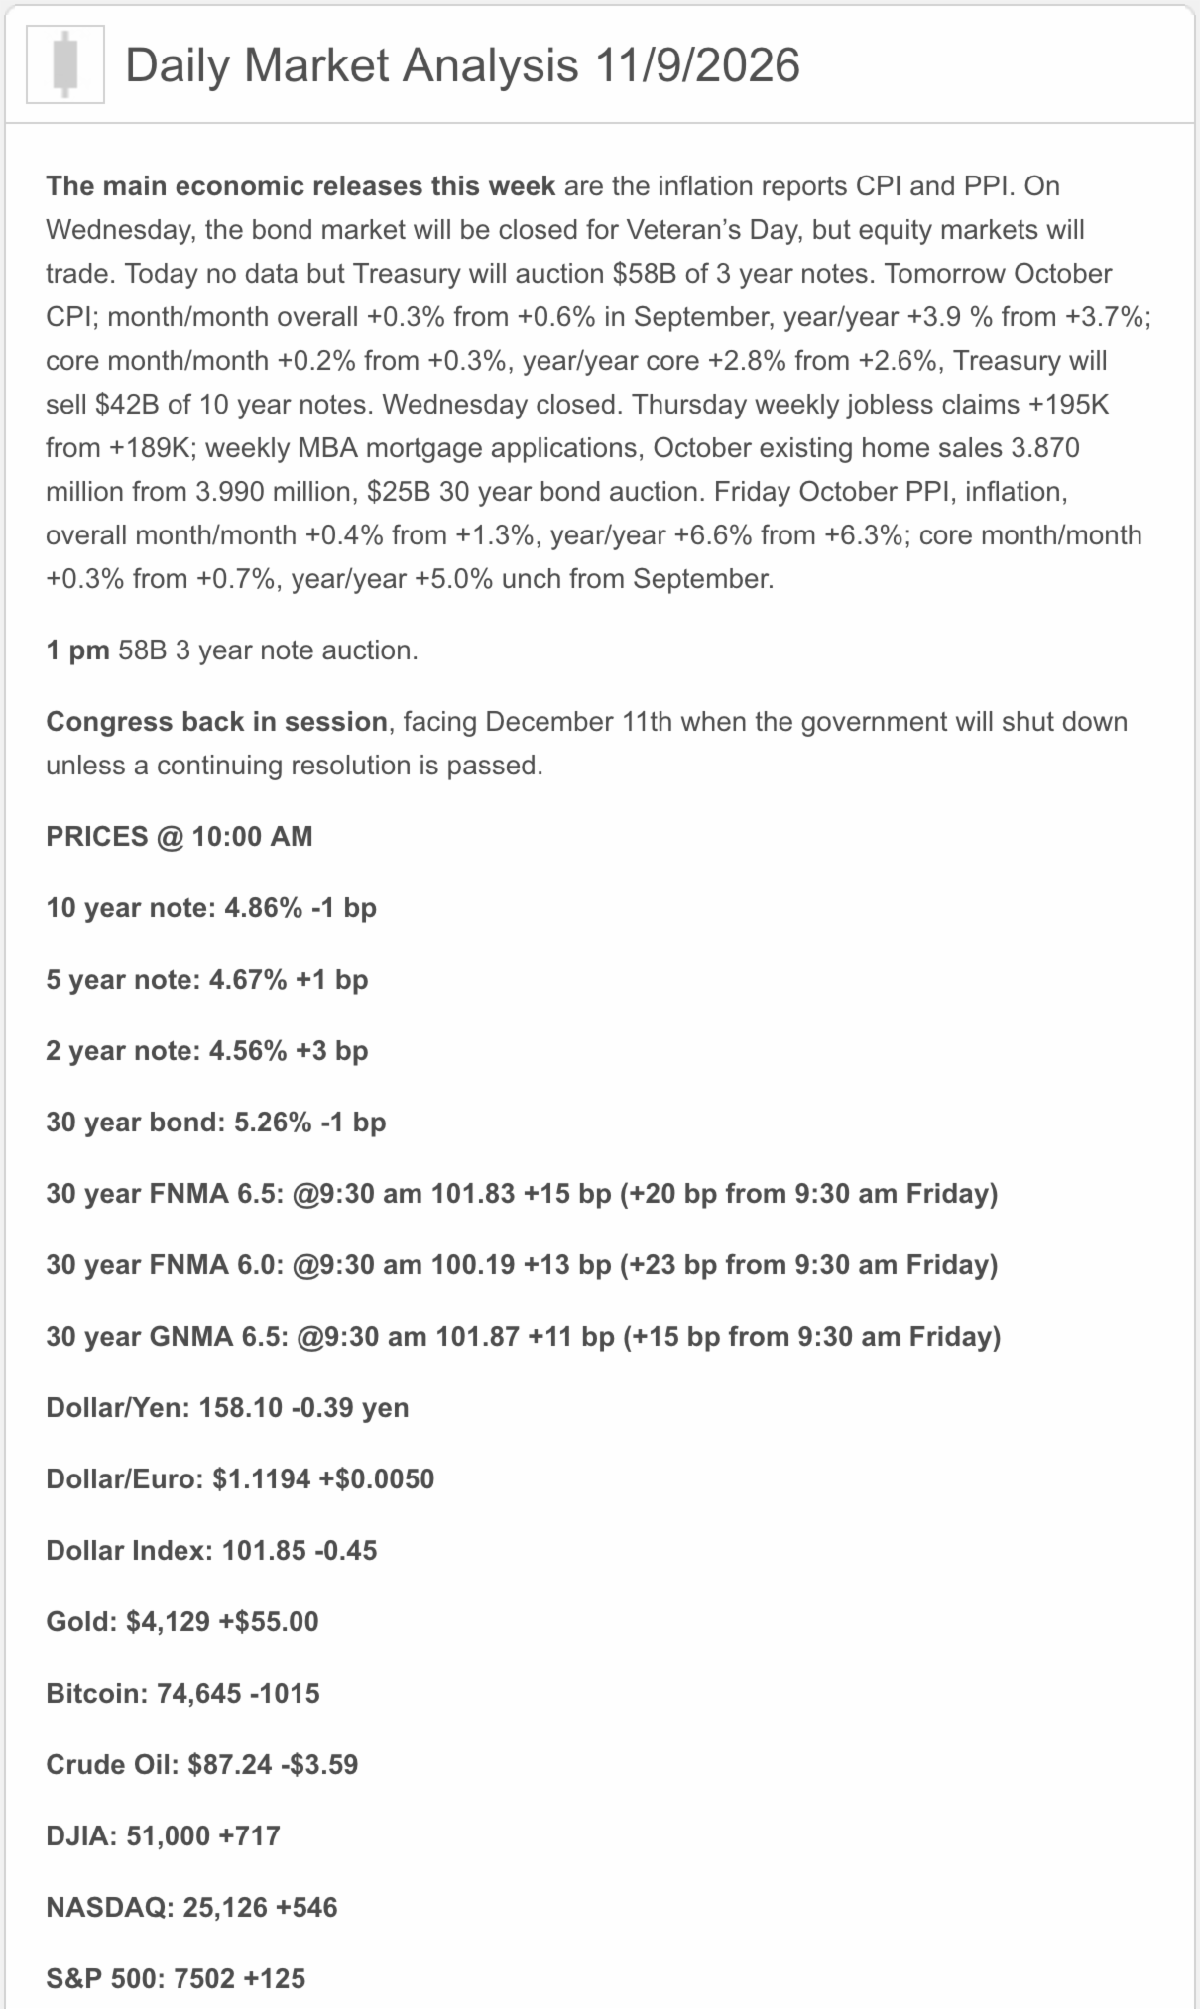
Rates are similar to Friday’s, with bonds seeing some early volatility as we’ve grown used to, although nothing changes the outlook. Today is a bond rollover day, so if you’re comparing numbers, mortgage-backed securities will appear to have lost some ground, but that doesn’t carry over to rate sheets.
From a higher and better view:
Markets are starting the week with a little more optimism. Tomorrow’s inflation report gets the microphone, so let’s enjoy the quieter opening without mistaking it for a permanent volume setting.
Quick Snapshot
-
Stocks: major U.S. indexes rose in early trading after last week’s AI-driven volatility. [8]
-
Bonds: 10-year Treasury 4.855%, down 0.7 basis point; UMBS 6.0 at 100.09, unchanged on the displayed quote. Intraday; exact quote time unavailable. [1]
-
Mortgage benchmark: Friday’s MND 30-year fixed index was 7.17%. [1]
-
Next test: Tuesday’s October CPI at 5:30 a.m. Pacific; PPI follows Friday at the same time. [5]
1 | What Hit This Morning
Lower oil prices helped ease inflation concerns, while stocks attempted a recovery. [3, 8] The next major U.S. inflation release is tomorrow—not today.
Friday’s jobs report remains relevant: October payrolls rose 165,000, unemployment was 4.1%, and revisions added 84,000 jobs to the prior two months. [2] My read: resilient hiring gives the Fed room to focus on inflation.
A stock rebound alone does not tell us where mortgage rates go next.
2 | Fed Watch
The Fed’s October 28 decision held its policy range at 3.75%–4.00%, with two dissenters preferring an increase. [4] Reuters reported an 80.5% market-implied chance of a December hike in its Monday coverage. That is changing market pricing, not a policy announcement. [3]
Tomorrow, watch headline inflation, core inflation excluding food and energy, and the monthly changes. Lower oil can help the headline, but it does not settle every part of the inflation story.
3 | Where Mortgage Rates Actually Are
MND’s completed November 6 indexes: 30-year fixed 7.17%, 15-year fixed 6.83%, and 30-year jumbo 7.38%. These national benchmarks are not Noble offers or APRs. [1]
They predate Monday’s lender pricing. Compare current quotes using the same loan, points, fees and lock period. The 10-year Treasury is a useful reference; mortgage-backed securities and lender pricing determine how much of a bond move reaches your quote.
4 | Housing Market Check
Freddie Mac’s November 5 weekly survey showed a 7.18% 30-year average, its third consecutive weekly decline. [6] This is last week’s survey, not a new Monday release.
That improvement can help affordability, but a purchase still needs to work with taxes, insurance and HOA costs included. For buyers and agents, compare a price reduction with seller-paid financing costs before choosing a concession. A lower sticker price and a lower monthly payment are different goals.
5 | Political Backdrop & Fed Independence
Markets continue to reassess AI regulation following Democrats’ congressional win. [7] Separately, Reuters linked softer oil to President Trump’s weekend indication that there would be no immediate re-escalation of the Iran conflict. [9]
My interpretation: regulation and energy policy can affect growth and inflation, but neither produces an automatic mortgage-rate outcome. The Fed’s stated focus remains employment and price stability. [4] Campaign headlines do not come with a rate-lock confirmation.
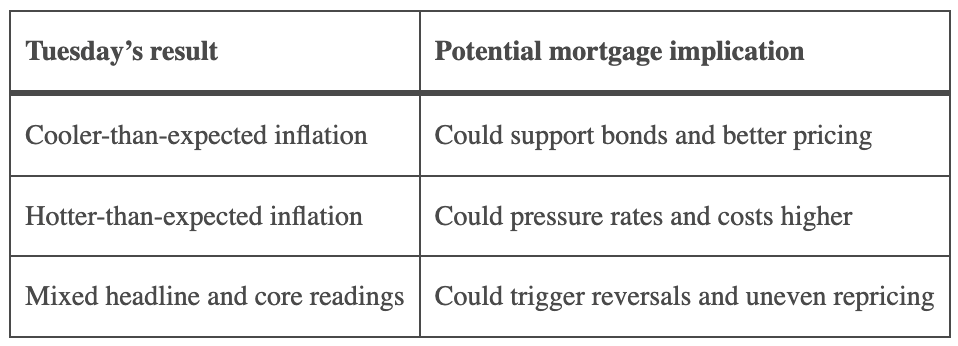
6 | Rate Scenarios
Possibilities, not forecasts:
|