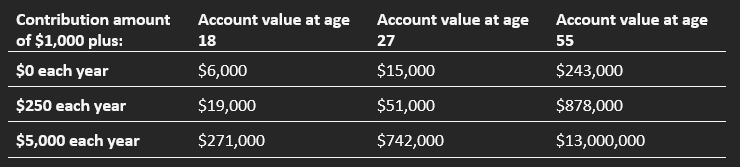|
Stocks Surge
The major U.S. stock indexes surged 3% to 5%, roughly matching the magnitude of the previous week’s gains. An easing of tensions in the Middle East sent oil prices down about 13%, providing lift for stocks.
The market’s back-to-back weekly gains went a long way toward reversing March’s declines. The NASDAQ’s cumulative gain for the two weeks was about 9%, the S&P 500’s was 7%, and the Dow’s was 6%. Year to date through Friday, the S&P 500 and the Dow were essentially flat on a total return basis while the NASDAQ was down about 1%.
Wall Street analysts modestly scaled back their expectations as major U.S. banks prepared to open quarterly earnings season. As of Friday, analysts surveyed by FactSet were forecasting an average first-quarter earnings growth rate of around 12.6% for companies in the S&P 500, down from a 13.2% forecast a week earlier. Either outcome would mark the sixth consecutive quarter of double-digit earnings growth.
A monthly gauge of U.S. consumer sentiment fell sharply, extending a recent decline amid conflict in the Middle East and the resulting spike in energy prices. The University of Michigan’s survey results released on Friday showed that sentiment fell to a preliminary April reading of 47.6, down from 53.3 in March and 56.6 in February.
An easing of Middle East tensions sent oil prices sharply lower, with U.S. crude dropping about 15% on Wednesday to as low as $91 per barrel following a cease-fire announcement. On Friday afternoon, oil was trading around $96, down about 13% for the week and well below a recent peak of around $119 reached in intraday trading on March 9.
Gold prices climbed for the second week in a row, regaining more of the ground lost in a mid-March sell-off. On Friday afternoon, gold was trading around $4,800 per ounce, up more than 2% for the week on the heels of a similar rise the previous week. Nevertheless, the precious metal remained well below the record high of around $5,500 set in late January.
Rising energy costs lifted the latest Consumer Price Index reading to an annual rate of 3.3%, well above the U.S. Federal Reserve’s long-term target of around 2.0%. March’s figure, released on Friday, was up sharply from the previous month’s 2.4% reading. The energy price component of CPI surged 12.5% year over year.
The U.S. economy expanded at a far slower pace in late 2025 than earlier estimates had indicated. Friday’s latest revision showed that GDP grew at an annual rate of 0.5% in the fourth quarter, down from a 0.7% estimate released in mid-March and an initial February reading of 1.4%. In contrast, the annual growth rate in the third quarter was 4.4%, the highest in two years.
Source: John Hancock Investment Management
| | Tennessee Federal Tax Filing Extensions | | |
The IRS recently made the following announcement:
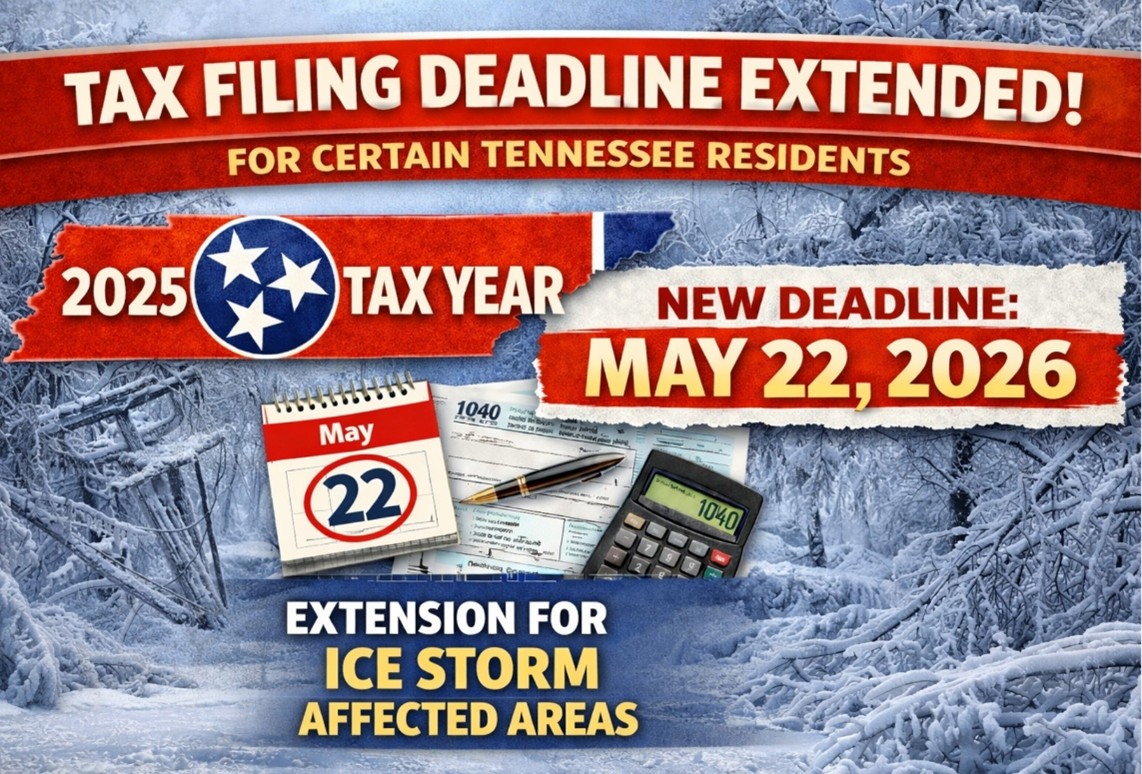
“Following the disaster declaration issued by the State of Tennessee, individuals and households that reside or have a business in Cheatham, Chester, Clay, Davidson, Decatur, Dickson, Hardeman, Hardin, Henderson, Hickman, Lawrence, Lewis, Macon, Maury, McNairy, Perry, Robertson, Rutherford, Summer, Trousdale, Wayne, Williamson and Wilson counties qualify for tax relief. The declaration permits the IRS to postpone certain tax-filing and tax-payment deadlines for taxpayers who reside or have a business in the disaster area. For instance, for certain deadlines falling on or after Jan. 22, 2026, and on or before May 22, 2026, taxpayers are granted additional time to file.
As a result, affected individuals and businesses will have until May 22, 2026, to file returns and pay any taxes that were originally due during this period.”
In addition to the main Form 1040 individual income tax return, the extension generally applies to a range of related filing obligations. These can include business tax returns (such as partnerships and S corporations), quarterly estimated tax payments, payroll and excise tax filings, and certain tax-exempt organization returns. Penalties and interest on these filings are typically waived during the extension period, provided they are submitted by the new deadline.
Note – this also extends the deadline to make 2025 IRA, Roth and HSA contributions to May 22, 2026.
It’s important to note that this extension is limited to taxpayers in specifically identified counties or areas impacted by the disaster, and normal deadlines still apply for those outside the designated zones. Taxpayers should verify their eligibility through IRS announcements or with a tax professional. Even with the extension, individuals are encouraged to file as soon as they are able, especially if they are expecting a refund or need to maintain compliance for financial or business purposes.
Here is a link to view the full announcement by the IRS.
| | New Retirement Account for Kids | | |
The One Big Beautiful Bill Act, which passed into law last summer, created a new type of retirement account known as the “Trump account”. Here’s what you need to know:
Who is eligible?
These accounts can be opened for any child who is younger than 18-years-old and has a Social Security number. To qualify the child must be age 17 or younger for the entire calendar year in which the account is opened, reported the Schwab Center for Financial Research (SCFR).
Who can contribute?
The U.S. Treasury will contribute $1,000 to the accounts of children born in the U.S. between January 1, 2025, and December 31, 2028, reported the Center for Retirement Research at Boston College (CRRBC).
Additional contributions (up to $5,000 each year) can be made by:
· Parents,
· Grandparents,
· Account beneficiaries,
· A parent or child’s employer (up to $2,500 that counts toward the annual limit),
· Charitable organizations (not subject to the $5,000 limit), and
· Federal, state, and local governments (not subject to the $5,000 limit).
Are contributions taxable?
It depends on who makes the contribution. Parents, grandparents, and other individuals do not get a tax break for contributions. However, contributions made by employers or other entities are made on a pre-tax basis, according to the CRRBC.
When can the money be withdrawn?
These accounts are intended to help young Americans fund their retirements. As a result, investment choices are limited and contributions cannot be withdrawn before the beneficiary reaches age 18. At that point, the account is subject to the same contribution rules as traditional IRAs, which means the account holder will owe taxes on any distributions, reported SCFR.
How much could an account be worth at retirement?
It’s difficult to know. The account value will depend on how much is contributed and how investments perform over time. The U.S. government’s website estimates account values at various ages, assuming an average annual return of for the Standard & Poor’s 500 Index. The average return is about 10.6%, which reflects the returns from 1957 through 2025, reported J.B. Maverick of Investopedia. Here’s what they estimate:
| | |
Is it better to contribute to a Trump account, a Roth IRA, or a 529 plan? It all depends. While the free money available to newborns is attractive, other types of accounts may offer greater flexibility and better tax advantages, reported Abby Schultz of Barron’s.
If you would like to learn more about ways to help young Americans save and invest for the future, please get in touch.
| | |
AJ Advisors
www.ajadvice.com
|
|
|
Phone: (615) 709-8709
Fax: (615) 709-8709
| |
| |
John Stauffer, CFP®
Partner
| |
Andrew Quinn, CFP®
Partner
| | Past performance does not guarantee future results. Different types of investments involve varying degrees of risk, and there can be no assurance that the future performance of any specific investment, strategy, or product (including those recommended or undertaken by AJ Advisors, LLC), or any non-investment related content, made reference to directly or indirectly in this communication will be profitable, equal any indicated historical performance level(s), be suitable for your portfolio or individual circumstances, or prove successful. Due to various factors, including changing market conditions and/or applicable laws, the content may no longer be reflective of current opinions or positions. You should not assume that any discussion or information contained in this communication serves as the receipt of, or as a substitute for, personalized investment advice. To the extent that a reader has any questions regarding the applicability of any specific issue discussed above to their individual situation, they are encouraged to consult with the professional adviser of their choosing. AJ Advisors, LLC is neither a law firm nor a certified public accounting firm and no portion of the content herein should be construed as legal or accounting advice. If you are an AJ Advisors, LLC client, please remember to contact the firm, in writing, if there are any changes in your financial situation or investment objectives or if you wish to impose, add, or modify any reasonable restrictions on our investment advisory services. Until so notified, AJ Advisors, LLC will continue to rely on the most recent information provided. A copy of our current written disclosure statement discussing our advisory services and fees continues to remain available upon request. | | | | |