Livestock Monitor
 
A Newsletter for Extension Staff
Livestock Marketing Information Center

July 17, 2026

Production

Week Ending 7/18/2026

Last

Year Ago

FI Cattle Slaughter (Thou Hd)

525

567

FI Hog Slaughter (Thou Hd)

2310

2333

FI Sheep Sltr. (Thou Hd)

33

36

Young Chicken Sltr. (Mil Hd)

174.7

172.5

-

Slaughter Cattle Live Weight

1448

1409

Slaughter Hog Live Weight

288

283

Sltr. Lamb/Sheep Live Wt.

117

119

-

Beef Production (Mil Pounds)

464.5

489.2

Pork Production (Mil Pounds)

496.7

492.3

Lamb, Mutton Prod. (Mil Lbs.)

2.0

2.2

-

Previous 6 Wk. Moving Avg.

Total Beef (Mil Lbs)

458.2

474.0

Total Pork (Mil Lbs)

494.2

480.8

Total Lamb, Mutton (Mil Lbs)

2.0

2.3


Source: Various USDA-AMS reports. Some data are preliminary.
Prices

Weekly Average ($/Cwt)

Last

Week Ago

Year Ago

Live Steer

238.59

248.01

237.78

Dressed Steer

377.33

391.49

379.36

Choice Beef Cutout

371.21

383.39

374.89

USDA Hide/Offal

14.08

14.12

11.68

OK City Fdr. Str. (6-7 Cwt.)

426.52

425.20

371.04

National Negotiated Hogs

99.70

97.22

111.79

Natl. Net Hog Carcass

95.15

93.23

105.32

Feeder Pigs (40 Lbs) ($/Head)

76.56

78.97

76.44

Pork Cutout

102.21

98.49

115.34

Lamb Cutout

671.84

658.50

458.03

Cheddar, 40 lb Block($/lb)

1.50

1.52

1.77

Corn, Omaha ($/Bu)

4.32

4.25

4.14

Soybeans, Cntrl IL ($/Bu)

12.29

12.09

10.30


Retail Meat Prices

Retail Meat Prices

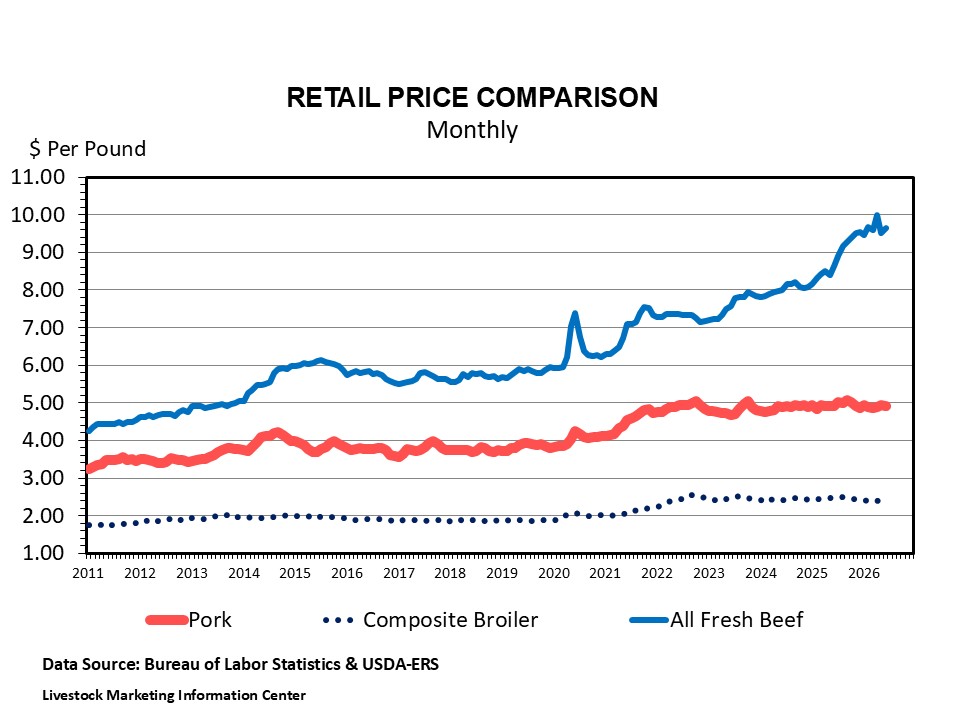
Retail price data for the month of June was released by the USDA-Economic Research Service (ERS), and retail beef prices continue to remain elevated while pork and broiler prices are steady. The All-Fresh retail beef price was $9.64 per pound in June, up $1.01 per pound (+12%) from last year. June’s All-Fresh retail beef price was the third highest on record behind $10.00 per pound in April and $9.69 per pound in February of this year. USDA-ERS reported June’s retail beef steak price at $12.88 per pound, an increase of $1.39 per pound (+12%) from last year and the second highest price on record behind $13.02 per pound in April 2026. Roasts increased $1.23 per pound (+15%) to a record of $9.43 per pound in June, surpassing the prior record of $9.41 per pound in April 2026. For the last three months, retail ground beef prices exceeded the $7 per pound mark. June was a record at $7.14 per pound, up $0.80 per pound (+13%) from last year.


June’s retail pork price was $4.92 per pound, down fractionally by $0.01 per pound (-0.1%) from last year. Since January 2022, the retail pork price has averaged $4.89 per pound and has remained within a $0.40 per pound range from $4.68 to $5.08 per pound. The retail bacon price has trended lower since the start of the year from $6.98 per pound in January to June’s price of $6.56 per pound, a decline of $0.42 per pound (-6%). Compared to a year ago, the retail bacon price was down $0.54 per pound (-8%). June’s retail pork chop price was up slightly by $0.07 per pound (+2%) to $4.34 per pound. The June retail ham price increased marginally by $0.06 per pound (+1%) to $4.46 per pound.


The June broiler composite retail price fell $0.11 per pound (-2%) from last year to $2.38 per pound, the lowest since February 2024 ($2.37). Since January 2022, the broiler composite retail price has averaged $2.44 per pound and has remained within a $0.33 per pound range from $2.22 to $2.54 per pound. The whole bird broiler retail price was $2.04 per pound in June, down $0.04 per pound (-2%) from last year. The retail egg price continues to decline from the record price of $6.23 per dozen in March 2025. June’s retail price was $2.14 per pound, down $4.09 per dozen (-66%) from the record and down $1.63 per dozen (-43%) from the prior year.

Poultry Production Boosted by Productivity


Chicken production in terms of ready-to-cook meat through the first half of 2026 is up +4% from a year earlier, a little more than had been expected at the start of the year. Almost all the increase can be traced back to hen productivity in the hatchery supply flock. Hatchings per hen in May were up +4.1% from May 2025, and the April increase was +3.6%. The year began with hatchery supply flock productivity being up +1.9% from a year earlier in January. Average bird weights at processing time have been up a little less than +1% so far this year, in line with expectations.


The additional supply appears to have caught processors with more product to sell than they expected, which has put some pressure on breast meat prices. Breast meat prices ended in 2025 at $1.15 per pound, moved up to average $1.42 per pound in the first quarter of 2026, and then was followed by an average of $1.53 per pound in the second quarter. This compares with $1.81 and $2.64 per pound in the same quarters of 2025, respectively. Even at the lower prices this year, processor margins have been positive, although nowhere close to a year earlier.


Leg parts prices have not shown much of an effect from the additional production. Wholesale prices have been about the same over the first six months of this year as in the similar period of 2025. Wholesale wing prices, which collapsed in the last quarter of 2025, remained under pressure in the first quarter of 2026, but consumer interest showed signs of improvement in the second half of the spring quarter.


Turkey production on a ready-to-cook pounds basis is up +6.5% from a year ago in the first half of 2026. Highly Path Avian Influenza (HPAI) took a smaller toll on commercial meat turkeys in the first half of the year. USDA-APHIS totals for HPAI deaths in the commercial meat flock in the first half of 2026 were 1.2 million birds versus 1.6 million birds in the same months of 2025. Average bird weights at processing time have averaged +2% to +3% heavier than a year ago. Turkey consumption during the first quarter was up 50 million pounds (+5%) from the same quarter in 2025, an encouraging sign for consumer demand. Preliminary measures of turkey consumption in the spring quarter point to only a +1% increase from a year ago, a trend that could cause problems for the industry if it extends over the second half of the year.

Food Sector Retail Sales Growth Steady at 3%

The Department of Commerce’s preliminary estimate of food sector retail sales in June registered a +2.6% gain from the same month in 2025. This was slightly less than the May increase of +3% but was close to the year-to-date average gain. Food service and drinking place sales in June were up +3.9%, the biggest increase since a +5.4% increase in February. Grocery store sales were up +0.9%, a pullback from a +1.9% increase in May that was the biggest year-over-year increase for grocery store sales this year. For the economy, retail sales were up +8.4% from June 2025, which was the biggest increase in more than three years. 

Livestock Marketing Information Center


Links

PDF Version


X Share This Email
LinkedIn Share This Email

State Extension Services in Cooperation with the USDA


Currently, 29 state Extension services participate in the LMIC - Alabama, Arizona, Arkansas, Colorado, Florida, Georgia, Idaho, Indiana, Iowa, Kansas, Kentucky, Louisiana, Michigan, Mississippi, Missouri, Montana, Nebraska, New Mexico, North Dakota, Oklahoma, Oregon, South Carolina, South Dakota, Tennessee, Texas, Utah, Washington, Wisconsin, and Wyoming. 


USDA members of the LMIC represent one of eight Federal partner agencies. Those participating agencies are the Agricultural Marketing Service (AMS), Animal Plant Health Inspection Service (APHIS), Grain Inspection Packers and Stockyards Administration (GIPSA), Economic Research Service (ERS), Farm Credit Administration (FCA), Foreign Agricultural Service (FAS), National Agricultural Statistics Service (NASS), and World Agricultural Outlook Board (WAOB).