|
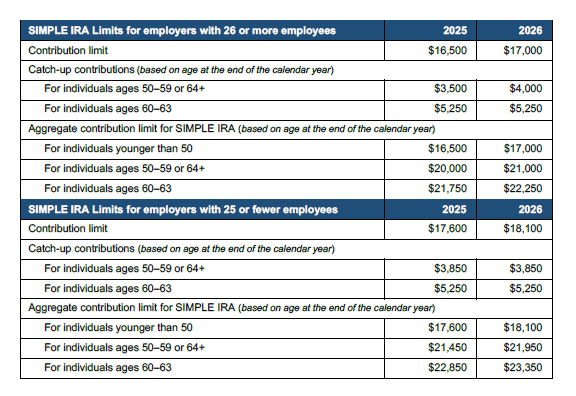
A note on SIMPLE IRAs: Employers with 26 or more employees can take advantage of these larger limits by increasing the employer contribution formula in the adoption agreement to a 4 percent matching contribution or a 3 percent nonelective contribution.
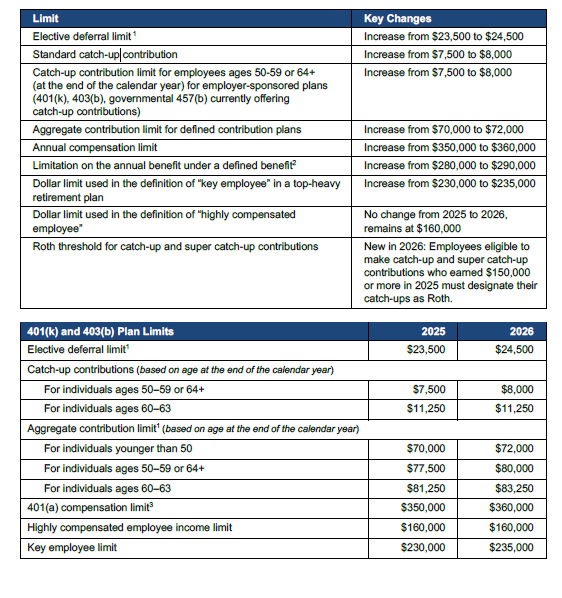
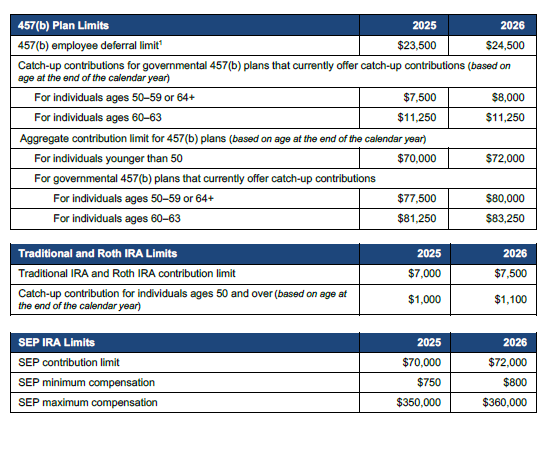
1 Employee deferrals to all 401(k) and 403(b) plans must be aggregated for purposes of this limit.
2 For a participant who separated from service before January 1, 2026, the limitation for defined benefit plans under Section 415(b)(1)(B) can be computed by multiplying the participant’s compensation limitation, as adjusted through 2025, by 1.0288.
3 401(a) compensation limit, the amount of earned income that can be used to calculate retirement account contributions. All compensation from a single employer (including all members of a controlled group) must be aggregated for purposes of this limit.
This material has been provided for general informational purposes only and does not constitute tax, legal, or specific investment advice. Although we go to great lengths to make sure our information is accurate and useful, we recommend you consult a qualified professional regarding your situation. Commonwealth Financial Network does not provide tax or legal advice
© 2025 Commonwealth Financial Network®
|