|
Market Navigator for the Quarter Ending September 30, 2025
Presented by Austin Fearon
Markets continued their upward climb in September, with U.S. stocks reaching new record highs despite the month’s historically weak reputation. Falling interest rates and stronger-than-expected earnings helped fuel the rally, while economic data showed steady growth. Although some risks remain, the overall tone was optimistic heading into the final quarter of the year.
1. Beyond the Headlines: Stocks Hit New Highs as Rally Extends into Fifth Month
2. Federal Reserve and Interest Rates: Fed Resumes Rate Cuts, Supporting Stocks and Bonds
3. Report Releases: GDP Revised Higher; Job Growth Slows Sharply
4. Looking Ahead: Political Gridlock and Global Tensions Could Test Market Resilience
Beyond the Headlines: Stocks Hit New Highs as Rally Extends into Fifth Month
September was another positive month for markets, as U.S. stocks gained on the back of continued growth and falling interest rates. The S&P 500 gained 3.65 percent for the month and 8.12 percent for the quarter. The Dow Jones Industrial Average returned 2.00 percent in September and 5.67 percent for the quarter. The Nasdaq Composite led the way with a strong 5.68 percent gain for the month, capping off a 11.41 percent rise in the third quarter.
The S&P 500, Dow, and Nasdaq all set record highs during the month, which was especially impressive given that September has historically been the worst month for investors. This now marks five straight months with positive returns for U.S. stocks, highlighting the strength of the current rally.
Fundamental factors were supportive of markets during the month. Second-quarter earnings season wrapped in September, and results came in better than expected. On average, companies in the S&P 500 saw earnings grow by 10.8 percent in the quarter, which was well above analysts’ estimates of 2.8 percent. Over the long run, fundamentals drive market performance, so this was an encouraging result for investors. Technical factors were supportive as well, as all three major U.S. indices spent the entire month well above their respective 200-day moving averages.
The story was similar for international stocks as well, with both developed and emerging markets gaining for the month. The MSCI EAFE Index gained 1.91 percent in September and 4.77 percent for the quarter. The MSCI Emerging Markets Index was up 7.18 in September and 10.95 percent for the quarter.
Even bonds were up, as falling interest rates supported all asset classes. The Bloomberg Aggregate Bond Index gained a solid 1.09 percent for the month, capping off a 2.03 percent gain for the quarter. High-yield bonds also participated in the ongoing rally as the Bloomberg U.S. High-Yield Corporate Bond Index was up 0.82 percent in September and 2.54 percent for the quarter.
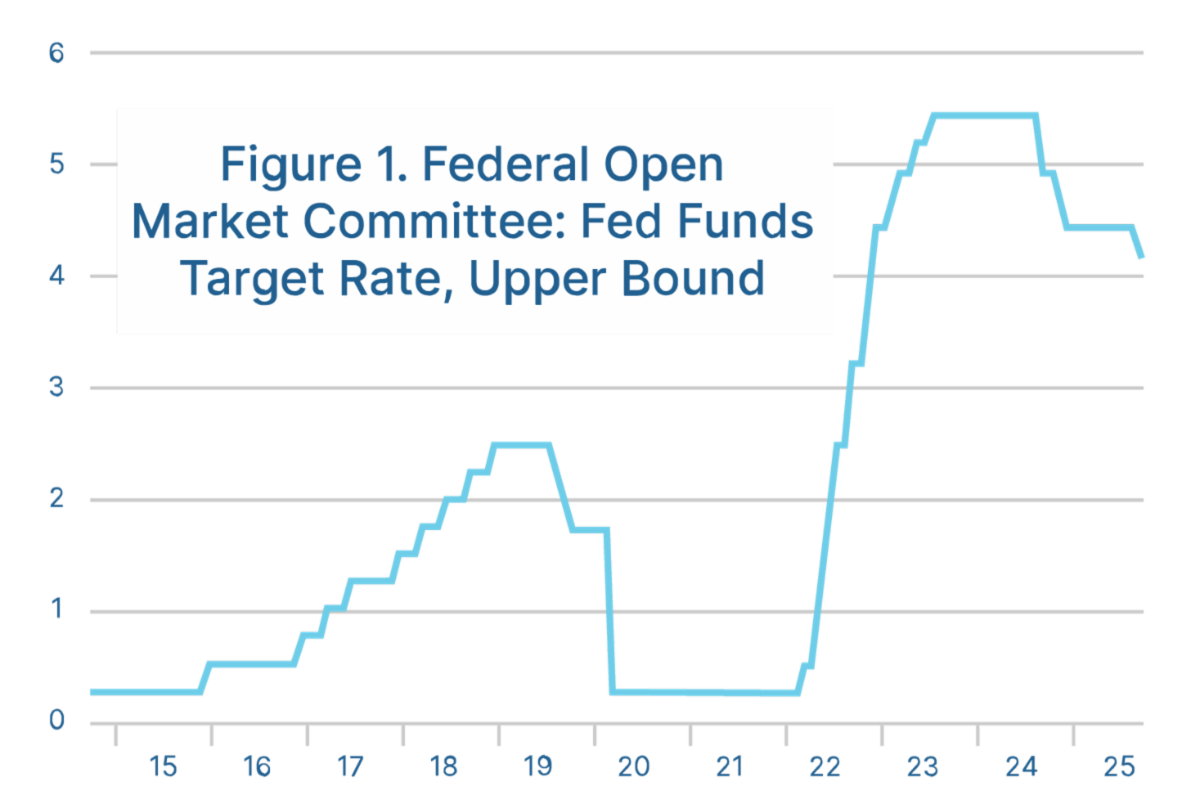
Federal Reserve and Interest Rates: Fed Resumes Rate Cuts, Supporting Stocks and Bonds Interest rates fell in September as the Federal Reserve resumed cutting rates at its mid-month meeting. This 25-basis-point rate cut was widely anticipated by investors and economists and signaled a new phase in the Fed’s attempts to normalize monetary policy. As seen in Figure 1, this marks the first rate cut in nearly a year following a series of rate cuts to end 2024.
|