The Miles Franklin Newsletter
|
|
From The Desk Of David Schectman
|
|
U.S. Debt to Quadruple to $3.8 Trillion; Total Budget Deficit Will Surpass World War II Record
– CRFB
American Workers Get a 4-Month Safety Net; Wall Street Gets a 4 to 5-Year Bailout
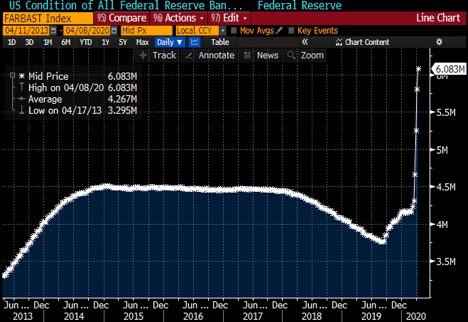
Bank of American analysts this week suggested the Fed's balance sheet could reach $9.0 TN by year-end.
M2 expanded an unprecedented $1.136 TN over five weeks (up $2.123 TN, or 14.6%, y-o-y). For some perspective, M2 has expanded more during the past six months than it did the entire nineties.
Never before has the world operated without limits to either the quantity or quality of "money" and Credit.
– Doug Noland
Last month I predicted that at least $10 trillion would be spent to mitigate the economic impact of this virus, and it appears as though we’re already there, with much more to go. And this is all before considering monetary stimulus in the form of near- zero rates and quantitative easing (QE).
– Frank Holmes
You’d think GLD investors would be getting very irked and switching to physical ownership by now. The GLD currently sits at $163.10 or $1,631. That’s a whopping 13% discount to physical, and 6% discount even to the bogus spot price. Look for GLD to increasingly lag physical as it too succumbs to the paper shenanigans.
– LeMetropole Café
If you hold a gold ETF, which you mustn’t, you know that it is unlikely to be backed by gold for more than a small portion of the fund total.
– Egon von Greyerz
"...the days where the dollar is the reserve currency are numbered and we’re going back to basics."
– Zero Hedge
|
|
David's Commentary (In Blue):
According to the most recent estimates, global GDP will fall 3% in 2020. To put that number in perspective, the global GDP fell 0.1% during the 2008-09 recession. We are staring down the barrel of a global depression, unlike anything we have experienced since the 1930s.
Should the Coronavirus still be with us a year from now, and that is a distinct possibility, then things will go from very bad to worse.
So how does Wall Street react to all of this? It really baffles the mind, but the stock market keeps moving back up toward the previous highs, which by all standards, were hugely over-valued at the start of the year, before the Coronavirus made its appearance.
How can this be happening? Well, the multi-trillion-dollar rescue plan and stimulus is working. Working for the top 1%, the banks and brokerages and large corporations. When it comes to main street, forget it.
So, the question becomes: Has The Fed Put In A Hard Bottom?
Here is a little history to show where we are in the cycle. As recently as just two months ago, on February 12th, the markets were sitting at all-time record valuations. The Dow topped out at 29,551. The stock markets were more extreme than in 1929, before the crash, more extreme than before the dot com crash in 2000, and way more extreme than before the housing bubble popped in 2008.
Here we are on April 14
th
, 19% below the all-time peak and it would still take more than a 65% retreat from this level to get back to what might be considered “normal.” There will be some very severe short-term and long-term consequences because of the Pandemic. We are no-where near a bottom, from a valuation point of view.
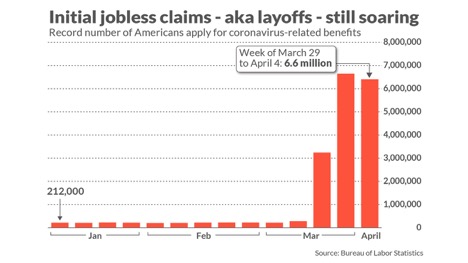
The stock market continues to rise in spite of the fact that more than 15 million people filed for unemployment in the past three weeks and that number will double or triple before it levels off.
|
|
One quarter of all home owners missed their mortgage payments last month and an even higher percentage of renters didn’t make their payments either. Most of the country is in a quarantine, a virtual lockdown. The streets are empty, businesses are boarded up, economic activity has been reduced to bare necessities. Stocks were overvalued even before this happened so how can they not be falling hard now?
In 2019 90% of our GDP was consumption based. The consumer holds up our economy, plain and simple. But suddenly, the consumer is tapped out and either can’t buy anything or won’t buy anything that is unnecessary. A majority of the buying public have already tapped out their credit cards and are unemployed. The paltry federal aid and unemployment benefits, all of which will run out by the end of the summer, are barely enough to pay rent and food.
When President Trump orders everyone back to work, will you go to a public restaurant or a movie or a concert or a sporting event or shop at a mall? I know I won’t and my children won’t. A majority of rational American’s will stay away from crowds until a proven vaccination is available and that will not happen until 2021, at minimum, and that assumes that one can even be developed. We still don’t have a vaccine for the common cold and most of the flu shots are only marginally effective. There still isn’t a vaccine for AIDS. It is easier said than done.
Under the most optimistic scenario, the economy will be a shadow of what it was in 2019 for years to come. And the band played on (at the closing bell on the exchange).
What does that mean for the stock market?
There are a couple of possibilities here. First, the 5,500-point bounce in the Dow, in the last 7 weeks, is a dead cat bounce and it will reverse soon and the second leg down will be even more severe than the first. Or, the Fed will ensure that the stock market holds up, in spite of the horrid fundamentals.
|
|
|
|
Rick Ackerman
Causing Stocks to Rise
|
|
|
|
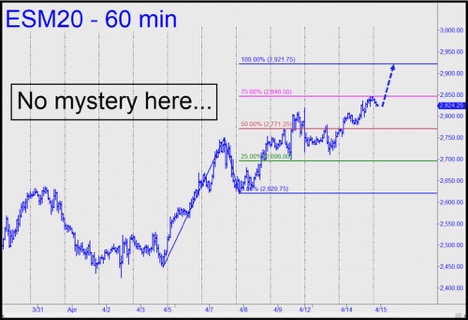
The stock market has been acting as though truckloads of oral vaccine will show up on supermarket shelves by the weekend. Of course, we know better than to attribute the robust uptrend of the last two weeks to careful or even rational calculation. The market after all is not a thinking creature, just a dumb beast that has been annoyed by a swarm of flies, or excited by pheromones washing over the olfactories. Far from thinking past the crisis, surging stocks are simply adjusting to the temporary exhaustion of sellers who bailed out when it seemed like the news couldn't get much worse.
There is little to encourage at this point, since we all understand that social distancing, with its ruinous effect on the economy, could continue indefinitely. So, do Warren Buffett, BlackRock's Laurence Fink, Bezos and other whales dive for cover, dumping their shares in a panic? A better question to ask is: To whom would they sell? Since there are no buyers big enough or dumb enough to take these Leviathans out of their positions, they will simply continue to moderate their offers as short-covering bears drive stocks further into the insanity zone. Big sellers dare not pounce, at least not yet, since this might frighten the herd back to its senses. But they will quietly distribute as much stock as they can before pulling the plug. The buyers will be mostly wrong-way bettors whose appetite for stocks has been stimulated by margin calls. DaBoyz will know when that appetite starts to wane, since they are literally making book on the game. Their touch is so light that the suckers enticed to do the buying no more feel the weight of distribution than someone living in Billings feels the swelling of the Yellowstone caldera.
|
|
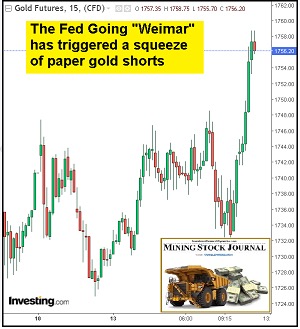
So, which is the false signal? The rising stock market, or rising gold?
They each point to a different outcome. I am of the strong opinion that gold is the real indicator. The global economy was slowing down before the Coronavirus shut everything down in an instant. I have said it often, and I will repeat it again, the Pandemic did not cause the economic collapse we are facing now, it was just the pin that popped the bubble. Actually, make that bubbles. The stock market, the bond market, the real estate market, all built on debt and low interest rates.
There will be winners and losers. The Fed’s response, and the response of all the world’s major central banks, has been to create trillions and trillions of dollars and pounds and euro and yen and yuan. This is the perfect set-up for Jim Sinclair’s “Reset.” And when it happens, gold will be the BIG winner. The losers will be everyone whose wealth is in paper investments.
|
|
For the last 35 years I have believed that at some point, the dollar would lose its reserve currency status and we would face severe inflation or even hyperinflation. I never wavered in my belief. The Fed, in the period of a week or two has guaranteed that outcome. Don’t focus on the stock market. It is an illusion, and it does not represent the economy. It is the result of trillions of dollars looking for a short-term return. Ask yourself this – when the Coronavirus is still with us next winter, and the economy never came back and countless more trillions have been thrown at the problem in an effort to keep a large portion of the population from taking to the streets, where do you think the stock market will be? Not that it matters. Where do you think gold will be?
|
|
A close friend told me “even a broken clock is right twice a day” to which I replied, yes, but THIS IS THE ONE TIME TO BE RIGHT. This could have happened at any time in the last 15 years, and almost did in 2008, but this is the time you do not want to be in dollar assets without a significant backing of gold and silver. You only need to be right one time and this is the time.
|
|
|
|
Frank Holmes
$10,000 gold isn’t crazy
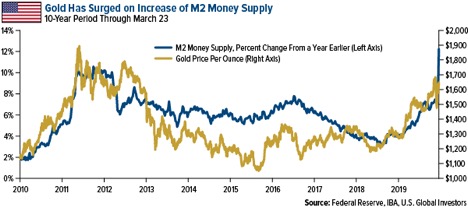
The U.S. economy is being flooded with excess money and liquidity right now. Compared to the same period a year ago, M2 money supply––which includes not just cash but also savings deposits, money market funds and other “near” money––has increased some 12 percent, the most in more than 10 years.
Money Supply Flowing Into Physical Gold
All this excess liquidity has to go somewhere, and historically it’s acted as Miracle-Gro for gold prices. Look at the chart below. There’s a clear correlation between the annual growth rate in M2 money supply and the price of the yellow metal. In the times when money supply surged from the same period a year earlier, gold prices followed.
|
|
|
|
Gold touched its all-time high of $1,900 an ounce in 2011 when M2 money supply growth soared above 10 percent year-over-year. With supply growth now at 12 percent––and likely headed higher––liquidity has flowed into physical gold as well as paper gold. On Monday, spot gold traded above $1,700 for the first time since December 2012. The next test, I believe, is $2,000, and as I’ve said before,
$10,000 gold isn’t crazy.
Gold is insurance against a broker financial system
|
|
|
|
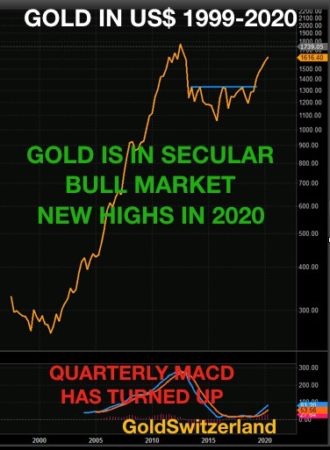
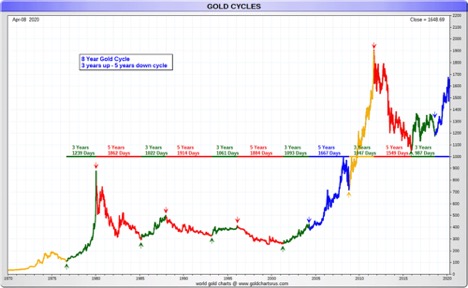
As the 20-year gold chart shows above, gold is in an extremely strong uptrend. In all currencies but US dollars, gold has surpassed the 2011 highs. The gold price in dollars has just broken out and is now likely to go to $1,700 on its way to the old high of $1,920 and thereafter much, much higher.
As I have expressed before, I have been standing on a soap box for 20 years in my attempt to inform investors of the critical importance of gold for wealth preservation purposes. Fortunately, many investors have listened but they still represent less than 0.5% of world financial assets. Since we started 18 years ago, gold is up 6-7X depending on the currency. That rise is insignificant compared to what is coming next.
But remember you are not holding gold to measure the gains in debased paper money. Instead you are holding physical gold as insurance against a broken financial system that is unlikely to be repaired for a very long time.
|
|
|
|
Ed Steer
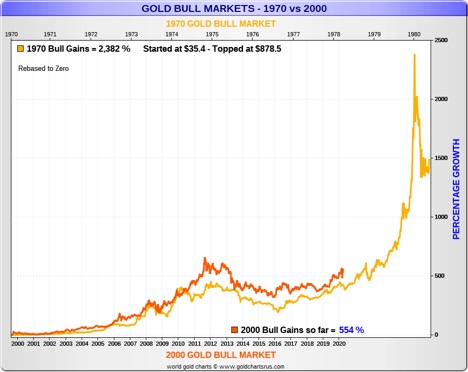
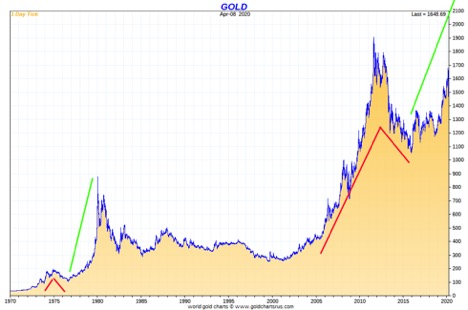
Potential gains of 400% are right in front of us.
Here are three charts that Nick Laird passed around late yesterday afternoon PDT...along with the comment that..."Potential gains of 4x are right in front of us." More than true enough, if JPMorgan et al. allow it. You should be able to follow along on all of them with no further commentary from me.
Click to enlarge
for all.
|
|
|
|
Egon von Greyerz
THE GREATEST FINANCIAL CRISIS & HYPERINFLATION
A Hyperinflationary Depression has always been the inevitable end to the biggest financial bubble in history. And this time it will be global. Hyperinflation will spread from country to country like Coronavirus. It could start anywhere but the most likely first countries are the US and the EU or ED (European Disunion) They will quickly be followed by many more like Japan and most developing countries. Like CV it will quickly jump from country to country with very few being spared.
CURRENT INTEREST RATES ARE A FALSE INDICATOR
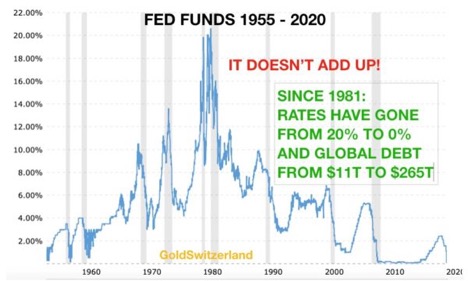
Ever since the last interest cycle peaked in 1981, there has been a 39-year downtrend in US and global rates from almost 20% to 0%. Since in a free market interest rates are a function of the demand for credit, this long downtrend points to a severe recession in the US and the rest of the world. The simple rules of supply and demand tell us that when the price of money is zero, nobody wants it. But instead debt has grown exponentially without putting any upside pressure on rates. The reason is simple. Central and commercial banks have created limitless amounts of credit out of thin air. In a fractional banking system banks can lend the same money 10 to 50 times. And central banks can just print infinite amounts.
|
|
|
|
Global debt in 1981 was $14 trillion. One would have assumed that with interest rates crashing there would not have been a major demand for debt. High demand would have led to high interest rates. But if we look at global debt in 2020 it is a staggering $265 trillion. So, debt has gone up 19X in the last 39 years and cost of debt has gone from 20% to 0% – Hmmm!
CORONAVIRUS IS THE CATALYST BUT NOT THE CAUSE
The crisis that the world is now encountering has not been caused by the Coronavirus. As I have stressed in many articles recently, CV is just the catalyst, albeit the most vicious one which could have hit the world. The real cause of the Greatest Financial Crisis in history is the Central Banks. They have been pouring fuel on the fire for 50 years by continuously reducing the cost of money until it became free in 2008 when rates were reduced to ZERO. Since then we have also seen negative rates around the world.
Negative rates are not just a total paradox but also absolute lunacy. Bankrupt sovereign nations around the world have been issuing debt at no cost or have even been paid for it. The whole purpose of interest is to be paid for the risk of lending money. As governments around the world have issued virtually unlimited debt which will never be repaid, the risk of lending to them has increased exponentially. But instead of much higher rates, to reflect the massive increase in debt plus severely elevated risk, central banks have got away with defying the laws of nature buy falsely manipulating rates..
FALSE MARKETS WITH NO REAL PRICES
Money is a commodity and the price should be a direct function of risk plus supply and demand. But since we currently have a false financial system with fake money and false markets, there are no real prices. So, through constant manipulation and intervention central banks together with a few accomplices can totally rig most markets and prices.
Therefore, the cost of money today neither reflects the risk nor the demand. All it represents is malicious manipulation to serve governments and their masters the central bankers. But like all fake markets, also this one will end, not just badly but catastrophically.
THE SITUATION IS DESPERATE FOR BUSINESSES AND INDIVIDUALS
As I discussed in last week’s article, we now have the perfect storm. Virtually every government in the world is now committing billions and trillions of dollars, euros etc. in fruitless attempts to save a collapsing world economy. In many countries, 50% or more of industry is shut. Most service industries are in a total lockdown and so is aviation, transport and most small businesses. Unemployment is approaching rates not seen since the 1930s depression. All businesses need assistance, from major corporations to small firms. The majority of individuals haven’t got savings for more than a couple of weeks living and for the ones who are now becoming unemployed, the situation is desperate.
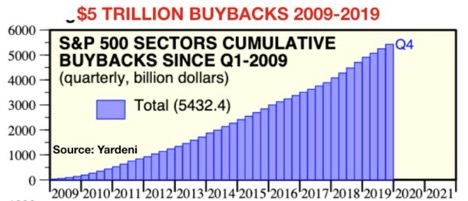
Many major US corporations need assistance from the government. Very few of these have put aside profits to reserves for a rainy day. Instead management has been too generously rewarded as well as the shareholders. Since 2009, S&P 500 companies have spent $5.4 trillion in share buybacks. Instead of asking government for assistance, management should pay back their bonuses and shareholders who have received major payouts should recapitalize the companies. But this will obviously not happen. Just like in 2006-9, profits are privatized and losses are socialized.
|
|
|
|
Businesses are hemorrhaging cash and so are individuals. All that becomes a vicious circle with bills not being paid including rents, mortgages and taxes. Estimates predict a 40-50% fall in Q2 2020 GDP in the US. The problem is that this is not a temporary crisis. This means that GDP will see permanent erosion of a major magnitude in most countries.
SECULAR DOWNTURN LEADING TO HYPERINFLATIONARY DEPRESSION
So, what we are experiencing is the start of a secular downturn which soon will become a hyperinflationary depression. This was always the inevitable end to this cycle as I have discussed in many articles for over 20 years.
A crisis of this magnitude is always a debt crisis. Very soon we will see debt around the world come under enormous pressure as borrowers start defaulting. This will lead to bonds crashing and rates surging. Central banks will then lose control of interest rates as long rates first go up and soon also pulling the shorter rates up. Rates can easily go to 15-20%. Many bonds will go to zero and rates to infinity. I have previously talked about paying 21% on my first mortgage in the UK in 1974. So, I have personal experience of high inflation but never hyperinflation.
Since the majority of the $1.5 quadrillion derivatives market is interest related, this market will also blow up. All this will lead to unlimited money printing and currencies crashing fast to their intrinsic value of ZERO. At that point the entire financial system will be unrecognizable and parts of it nonexistent. All of this could happen very quickly, possibly within the next 6 -18 months.
2006-9 WAS A REHEARSAL
Could my Cassandra forecast be wrong? Yes, of course it could. But let’s be clear that the rehearsal of what I am predicting took place in 2006-9. Nothing was resolved at that point, just temporarily deferred. This is now the real thing and whatever money central banks print this time will have no effect. So, I doubt very much that our banker “friends” can pull another trick out of the hat again. Because the only trick they know, to print more money, can never solve a debt problem.
MARKETS
Stock markets, in their first leg down of the new secular bear market, reached a 40% loss in most countries and that in less than 4 weeks. We are now seeing a typical correction that can go a bit higher. But when that is finished which could take 1-3 weeks, the next devastating down leg will start. Anyone trying to catch this falling knife will be slaughtered.
Bond markets might hold up for a bit longer with massive central bank manipulation and money printing. Junk bonds will first start crashing and constant downgrades will turn a lot of debt to junk. Much of corporate debt will go the same way and within 6-12 months also sovereign debt will come under attack.
Property markets are a major bubble and are already starting to disintegrate. Industrial, commercial, retail and residential, no sector will be spared. There will be no buyers, no financing and many forced sellers. A perfect recipe for a collapse.
Before the secular bear market has bottomed in these three markets, prices will be down 90-100% in real terms. And real terms means in constant purchasing power like gold.
We must remember that markets will bottom long before the economy. The likely development is first a hyperinflationary depression that could come and go very quickly within the next couple of years. Thereafter we will most probably see a deflationary implosion of all assets and a collapse of most of the financial system.
But we mustn’t believe that this is the end. It is just another phase in the world economy to correct excesses of the 100 or 300 years or even 2000 years. Once debt has imploded and all asset prices have come down from current fantasy valuations, a new system will emerge built on sound values and principles. And then the cycle starts all over again.
GOLD
There are currently severe pressures in both the paper gold market and the physical market. The Comex and LBMA are making noises that everything is under control. LBMA is giving the illusion that they have plenty of gold in their vaults. But virtually all of that gold is already committed. Comex, the gold futures exchange is under tremendous pressure since they can’t deliver more than a small fraction in physical when paper holders of gold demand delivery. And that day is not far away.
The 3 biggest refiners in the world based in Ticino, Switzerland have been closed for 2 1/2 weeks, representing at least 50% of world production. The refiners have just opened this week but at a very reduced capacity of 25-33%.
If we just take the Gold ETFs as an example, they increased their holdings by 93 tonnes in the last 4 weeks. That represents a total value of $5 billion
It is today virtually impossible to get hold of physical gold so you wonder where the ETFs have bought their gold.
The answer is of course simple. It was lent to them by LBMA banks which are custodians for the biggest gold ETF GLD. These banks also hold central bank gold and all they need to do is to lend the same gold yet one more time to the ETFs. So, if you hold a gold ETF, which you mustn’t, you know that it is unlikely to be backed by gold for more than a small portion of the fund total.
In a world where prices of most assets are about to implode, gold is life insurance and virtually the only asset that will maintain its value in real terms. Silver is also likely to do very well and will most probably outperform gold. But gold is safer and much less volatile.
|
|
Private Safe Deposit Boxes
|
|
Unencumbered / Segregated Storage
|
|
About Miles Franklin
Miles Franklin was founded in January, 1990 by David MILES Schectman. David's son, Andy Schectman, our CEO, joined Miles Franklin in 1991. Miles Franklin's primary focus from 1990 through 1998 was the Swiss Annuity and we were one of the two top firms in the industry. In November, 2000, we decided to de-emphasize our focus on off-shore investing and moved primarily into gold and silver, which we felt were about to enter into a long-term bull market cycle. Our timing and our new direction proved to be the right thing to do.
We are rated A+ by the BBB with zero complaints on our record. We are recommended by many prominent newsletter writers including Doug Casey, Jim Sinclair, David Morgan, Future Money Trends and the SGT Report.
For your protection, regardless of where you live, we are licensed, regulated, bonded and background checked per Minnesota State law.
|
|
Miles Franklin
801 Twelve Oaks Center Drive
Suite 834
Wayzata, MN 55391
1-800-822-8080
|
|
Copyright © 2020. All Rights Reserved.
|
|
|
|
|
|
|