August 11, 2025

older_couple_bowling_win.jpg

Retirement Realities


Predicting exactly what your retirement will be like is about as possible as a meteorologist predicting the weather correctly every single time. In fact, few retirees find their financial futures playing out precisely as they assumed.


Read More...

The Markets

U.S. companies have been hitting it out of the park!


Earnings season happens four times every year. It’s the period of time when publicly traded companies report how they performed during the previous quarter. So far, in aggregate, the companies in the Standard & Poor’s (S&P) 500 Index have delivered solid results for the second quarter of 2025.


“Overall, 66 [percent] of the companies in the S&P 500 have reported actual results for Q2 2025 to date. Of these companies, 82 [percent] have reported actual EPS [earnings per share] above estimates, which is above the 5-year average of 78 [percent] and above the 10-year average of 75 [percent]. If 82 [percent] is the final number for the quarter, it will mark the largest percentage of S&P 500 companies reporting a positive EPS surprise for a quarter since Q3 2021 (also 82 [percent]),” reported John Butters of FactSet.


While many U.S. companies had an excellent second quarter, economic clouds are shadowing investor optimism.


“Investors are struggling with a contradiction at the heart of the market as stocks move into their toughest months of the year. On the one hand, earnings have been strong. On the other, economic data are showing signs of weakness. How the two variables play out could determine whether the stock market can keep rallying to new highs—or stumbles into an end-of-summer selloff,” explained Martin Baccardax of Barron’s.


Recent economic data show a softening labor market and weaker consumer spending. (Consumer spending is the primary driver of U.S. economic growth.) In addition, activity in the manufacturing and service sectors slowed. Nazmul Ahasan of Bloomberg reported:


“The Institute for Supply Management’s index of services declined last month to 50.1, below all estimates in a Bloomberg survey of economists. Readings above 50 indicate expansion…The data, released Tuesday, paint a picture of a sluggish service economy wrestling with the fallout of higher tariffs, cautious consumers and [policy] uncertainty…The services sector is by far the largest in the U.S. economy, and has helped drive growth this year while the manufacturing industry contracted for five straight months.”


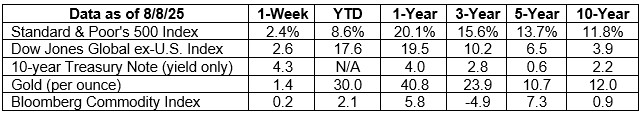
Last week, the major U.S. stock indexes rallied. The Nasdaq Composite Index closed at a record high, while the Standard & Poor’s 500 Index and Dow Jones Industrial Indexes finished the week close to new highs, reported Amalya Dubrovsky , Brett LoGiurato and Laura Bratton of Yahoo! Finance. U.S. Treasury yields generally moved higher. The 30-year Treasury bond yielding 4.85% at the end of last week.

patriotic-burger.jpg

Burgernomics: A Look At The Big Mac Index


During the first six months of 2025, the United States dollar delivered its worst performance since 1991. “The U.S. Dollar Index, which measures the value of the greenback against the world’s six most traded currencies, has lost almost 11 [percent] of its value…,” reported Valerio Baselli of Morningstar.


The drop in the U.S. dollar’s value hasn’t made as big a difference as some might have expected – at least when it comes to buying burgers abroad.


Since 1986, The Economist has been using the “Big Mac Index” as a lighthearted way to measure the relative value of currencies across the world. In theory, if currency exchange rates are properly aligned, a burger should cost the same no matter where it is purchased. (This is known as purchasing-power parity.) That’s rarely the case, so the index helps identify which countries’ currencies are overvalued or undervalued.


“Purchasing-power parity suggests that, with a Taiwanese Big Mac costing 78 Taiwanese dollars and an American one $6.01, the currencies’ exchange rate should be the ratio of the two prices. Hence $1 should buy NT$13 [new Taiwan dollars]. In reality, it buys NT$29. The Big Mac index therefore concludes that the Taiwanese dollar is greatly undervalued against the greenback, by some 56 [percent],” explained The Economist.


In July 2025, The Economist updated the Index, comparing the price of a burger in the U.S. to the price overseas. (The price of a burger in the United States rose from $5.79 in January to $6.01 in July.) After the decline in the U.S. dollar, currencies in many Asian countries remained significantly undervalued relative to the dollar. For example, a burger costs:


  • 49.8 percent less in Hong Kong than it does in the United States.
  • 41.2 percent less in Japan than it does in the United States.
  • 41.1 percent less in Indonesia than it does in the United States.
  • 38.5 percent less in India than it does in the United States.


In contrast, a burger costs:


  • 54.7 percent more in Switzerland than it does in the United States.
  • 39.0 percent more in Sweden than it does in the United States.
  • 36.1 percent more in the Euro than it does in the United States.
  • 31.1 percent more in Britain than it does in the United States.


Overall, European countries have seen their currencies become more expensive when compared to the U.S. dollar, while currencies in China, Japan, Singapore, South Korea, Taiwan and Vietnam remain undervalued relative to the U.S. dollar. “Most are now even cheaper,” according to The Economist.

Bruce Kuehl | 763.542.8884 | bruce.kuehl@avior.com

Investment management and financial planning services offered through Avior Wealth Management, LLC a registered investment advisor. Investments involve varying degrees of risk and there can be no assurance that the future performance of any investment or investment strategy will be profitable or equal past performance results. All investments subject to loss including the loss of principle. Nothing contained herein should be construed as tax advice. Specific, individual tax questions should be asked of your CPA or accountant.


Please remember to contact Avior, In writing, if there are any changes in your personal/financial situation or investment objectives for the purpose of reviewing/evaluating/revising our previous recommendations and/or services, or if you want to impose, add, or modify any reasonable restrictions to our investment advisory services. Unless, and until, you notify us, in writing, to the contrary, we shall continue to provide services as we do currently. Please advise us if you have not been receiving account statements (at least quarterly) from the account custodian. A copy of our current written disclosure Brochure and Form CRS (Customer Relationship Summary) discussing our advisory services and fees continues to remain available upon request or at www.aviorwealthmn.com.