|
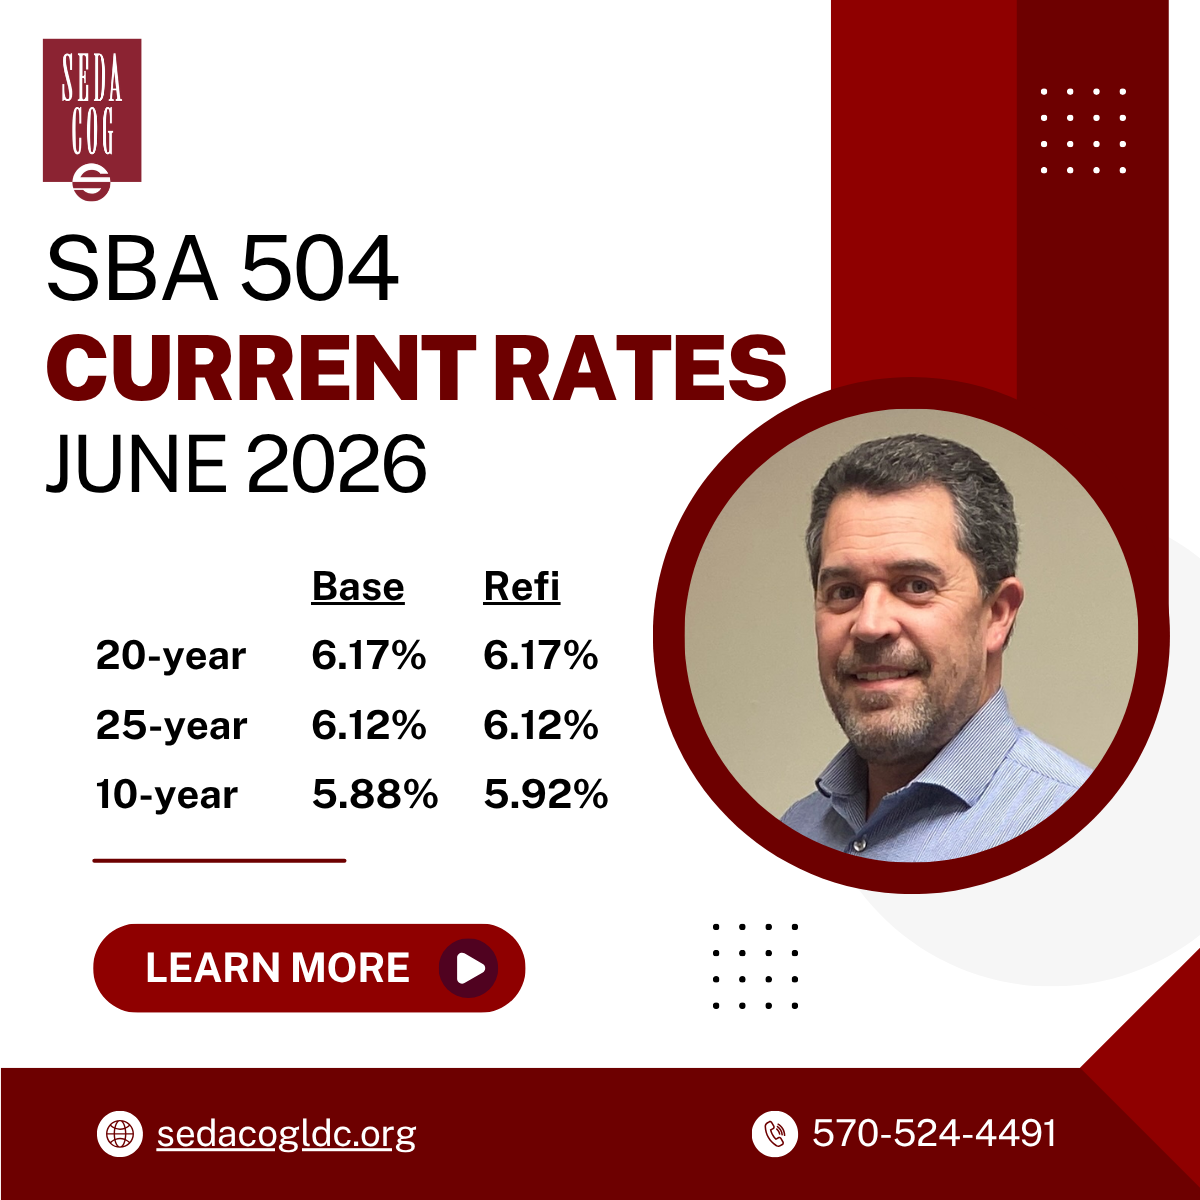
NADCO, the trade association for the nation's Certified Development Companies (CDCs), has released the SBA 504 fixed interest rates for June 2026. Eagle Compliance, the Fiscal Agent for the SBA 504 Loan Program, responsible for the marketing, pricing, and selling of the debentures sold to investors to fund the SBA 504 Loan Program, stated that June saw SBA interest rates rise due to strong job numbers, inflation, and a continued uncertainty surrounding the conflict in Iran.
According to Eagle Compliance, a week before the SBA bond sales:
Stronger Jobs Growth, Higher Yields, Weaker Stocks
Preliminary jobs data leading up to Friday’s Non-Farm Payroll report was positive, and then the report of 172,000 jobs for May blew past the consensus number of 85,000, triggering a selloff in equities and Treasuries. Not only was the May number strong, but March and April were revised upward by 93,000, resulting in a three-month average of 188,000 jobs, the best since May 2024. The Unemployment Rate remains at 4.3% as more people joined the workforce, with 61.8% of Americans now working or looking for work.
Treasuries sold off, led by the two-year Note, as that is the most sensitive security to any policy change, and at 4.16% it is yielding 41 bps more than the upper end of the Fed’s target range of 3.50%-3.75%, a clear indication that the market does not expect a rate cut anytime soon. What this means for the new Fed Chairman, Kevin Warsh, is that it will be more difficult to advocate for a dovish policy against a backdrop of higher inflation, strong job growth, and a stock market where 98% of S&P 500 companies have reported 1Q2026 earnings per share that are up 29%. His first meeting as Chairman is June 6-7, and the futures market predicts no change in policy but does assign a 50% chance of a rate hike to 3.75%-4.0% at its December 9 meeting. That is six months away, and still the current level of the two-year Note at 4.16% would still be higher than that upper band rate.
Further out, the curve of the ten-year benchmark Note is at 4.54%, 20 bps higher than when the 504 program priced its May debentures and offering less premium for investors vs. the two-year Note when measured by the slope of the Treasury curve. That spread, or difference between the 2-year and 10-year Treasury, is now +38 bps, its tightest level since shortly after the April 2, 2025, Liberation Day announcement of tariffs.
The Benefit of Lower Rates
US debt as a percentage of GDP is back to 1940’s levels, and interest payments are a big part of it. The cost to the Treasury has increased from 1.5% of GDP in 2021 to more than 3% today, and the US deficit is running at nearly 6% of GDP. It has been reported that the current $39 trillion debt burden increases by $1 trillion every 163 days and questions the sustainability of this trend. The Congressional Budget Office estimates that if deficits don’t decrease, the cost of debt to GDP will increase to 4.6% by 2036.
President Trump is aware of this, and that is the reason he advocates for rate cuts not just to promote economic growth but also to reduce government borrowing costs, but with solid job growth and robust corporate performance, rates are unlikely to come down until inflation does.
In Other Markets
Bitcoin has stumbled as retail investors have departed for the AI-driven stock market. Down as much as 5.5% on Thursday and 14% on the week, the crypto is at $61,500 after trading as high as $125,000 in October. Some recent pressure is the result of Strategy selling part of its holdings to fund payments to holders of its preferred stock.
Strategy, the world’s largest corporate Bitcoin treasury company, had raised $10.2 billion recently to finance Bitcoin purchases by selling a type of preferred perpetual stock known as Stretch that pays annual dividends of 11.5% but has no potential upside linked to the stock market.
Strategy has been a buyer of Bitcoin since 2020 with $6.4B in holdings, and this was just their second sale ever and consisted of just 32 bitcoins for a total of $2.5M. Not significant, but perhaps an indication of more sales, especially if funds are needed to pay holders of their stock. With an approximate cost of $67,000 to mine one Bitcoin, its market is upside down for now.
After declining 4% on Friday, the Nasdaq is preparing for SpaceX, Anthropic, and OpenAI to launch IPO’s, and SpaceX in particular will be massive with its self-evaluation amounting to $1.7 trillion.
Following the bond sales, Eagle Compliance reported:
Excellent Sale, Not Sure I Like That New Tone Of Yours!
As we moved toward the June SBAP sale, a distinct shift in the tone within the fixed income markets was noticeable. The recent Non-Farm Payrolls report had revealed significantly stronger-than-expected job gains, and prior month gains were also revised upward. Geo-political conflicts continued abroad with little hard or prolonged evidence of abating anytime soon. These factors led many to believe that the chance of an additional FOMC decrease in rates during 2026 was highly unlikely; in fact, the probability of an increase in rates during their October meeting was now at 51%, and at 70% for their December meeting. Soon-to-be-released economic indicators included the well-watched CPI (Wednesday) and PPI (Thursday) reports. From the prior month, U.S. Treasuries had increased significantly in yield across the curve. The 10-Year yield was 4.52%, up 18 bps month over month. The U.S. Treasury 2s/10s, 5/10s, and 10s/30s points on the yield curve had once again flattened month over month for a total of 9 bps, 9 bps, and 12 bps, respectively. Comparable ACMBS issues had maintained spread levels month over month, while corporate credit had improved mildly. With these factors in mind, it was decided that the suggested initial pricing spread on the 20-Year debenture and 25-Year debenture would be +48 bps to the 10-Yr. U.S. Treasury Note, the same levels used for the May pricing.
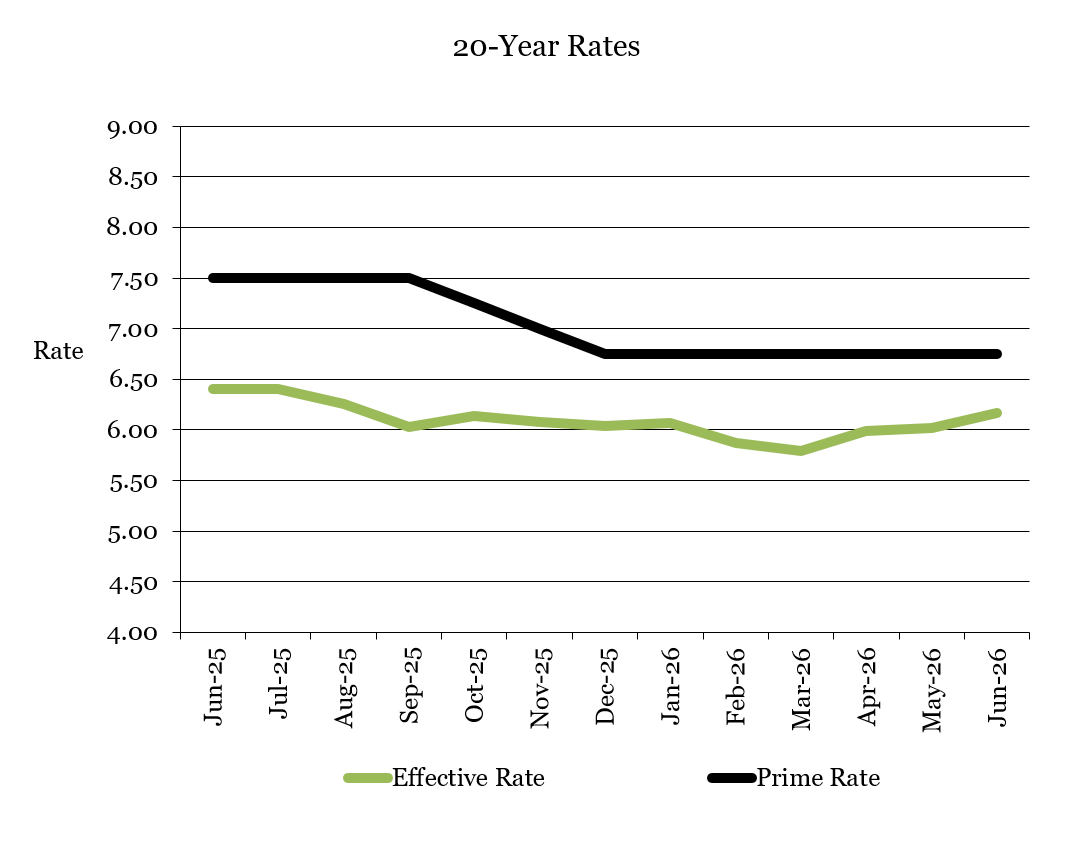
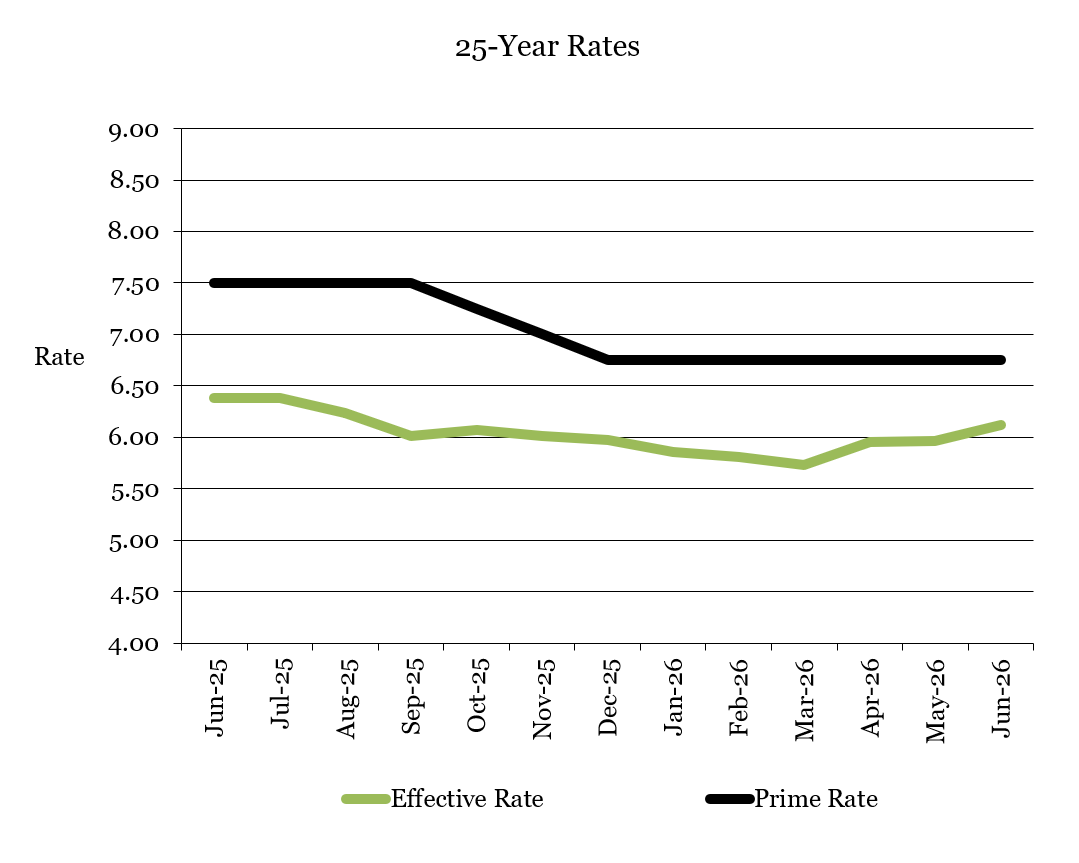
Investor response to the SBAP $28.046 million 20-Year was immediate and very positive; for the SBAP $564.461 million 25-Year, it was also very good. Each issue received investor interest (orders) well in excess of the par amounts offered. Given the very good reception on each issue, it was decided that the pricing spreads could be narrowed by 3 bps on the 20-Year and by 2 bps on the 25-Year. The 20-Year debenture was priced at a spread of +45 bps (lowest since February 2022), the 25-Year debenture was priced at a spread of +46 bps; each to the U.S. Treasury 10-Year (3 bps and 2 bps narrower on the 20-Year and 25-Year, respectively, from the May pricing). The June debenture rate for the 20-Year was 4.97%, and for the 25-Year it was 4.98% (15 bps and 16 bps higher, respectively, than the May pricing). The 25-Year rate is 37 bps under the program life average of 5.35%, and the spread over Treasury (+46) was 32 bps below its program life average of T+78.
On Wednesday, the CPI report revealed a 0.5% increase in May, which was expected; year-over-year, consumer prices jumped 4.2%, also as expected, marking the largest annual gain since April 2023. Excluding food and energy costs, the core CPI rose 0.2% in May; year-over-year, the core CPI climbed 2.9%. Thursday’s release of the PPI report revealed a 1.1% increase in May, well surpassing the 0.7% gain expected, which follows a similar rise the month prior; year-over-year, producer prices soared 6.5%, marking the largest increase since November 2022. Excluding food and energy costs, the core PPI rose 0.4% in May, a tenth of a percentage point less than expected; year-over-year, the core PPI climbed 4.9% for the second consecutive month. Fresh multi-year highs in consumer and producer prices underscore consumer pain resulting from disruptions in the global energy market. Although the American consumer has proven rather nimble and resilient thus far, such resilience is not indefinite. Eventually, higher prices will further slow and, if sustained, break the growth profile of the domestic economy.
Week over week, U.S. Treasury yields decreased slightly, with the UST 5-year and 10-year yields at 4.20% and 4.48%, respectively, down 7 and 4 basis points, respectively. Equity indices were relatively unchanged week over week. Next week, all eyes and ears will likely be focused on Wednesday’s FOMC announcement, which, as mentioned above, is not unlikely to result in any rate change. It will be Kevin Warsh’s 1st post meeting press conference as Chairman, which could prove interesting and perhaps revealing.
_________________________________________________________________
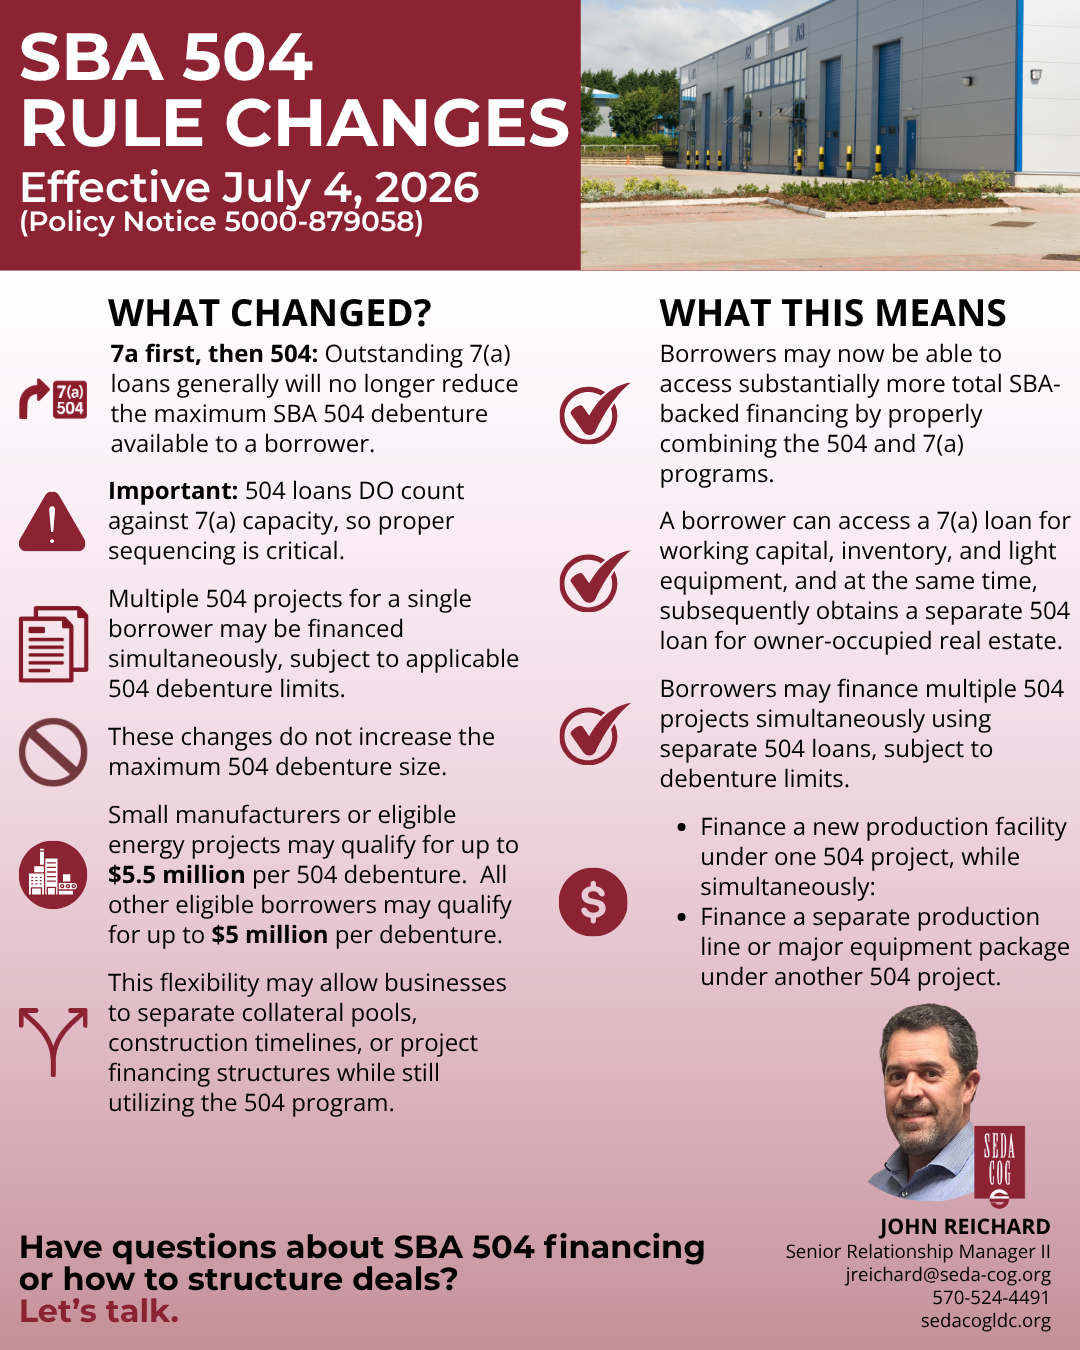
Despite the recent rising rates, SBA 504 loans continue to be very attractive, as it reduces the down payment on commercial real estate projects to as low as 10% and provide a 20 or 25-year fixed rate for up to 40% of the borrower's financing need.
For more information about the SBA 504 loan program, visit sedacogldc.org.
|