September 28, 2026

discuss_agreement.jpg

Top 5 Things To Tell Your Financial Professional


In order for our Avior advisors to help you along your financial journey, it is very helpful to keep in touch and let them know these 5 things.


Read More

The Markets

Keep your eye on your long-term goals.


Batters have one of the most difficult jobs in baseball: keeping their eyes on the ball. It seems straightforward, but there are always distractions, from a pitcher’s pacing to the fans’ heckling. As Crash Davis points out in Bull Durham, “Know what the difference between hitting .250 and .300 is? It's 25 hits - 25 hits in 500 at-bats is 50 points.”


An investor's job is difficult, too, especially during election season. For investors, the challenge is to stay calm and focus on their long-term goals. It isn’t easy amid the chaos of political noise when emotions are running high. It can help to remember that stocks have trended higher historically regardless of which party is in power or how the government is configured.


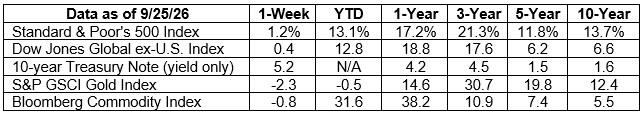
While you cannot invest directly in an index, the Standard & Poor’s 500 Index illustrates the point well. In January 1945, the Index was trading at 13.50. Last Friday, it finished at 7,743.40. There were a lot of ups and downs in between those years, but stocks trended higher overall.


Historical stock market performance doesn’t mean politics is irrelevant


The United States government sets policies and appoints officials that affect Americans’ lives every day. For the 2026 midterms, economic issues are top of mind for many voters, according to Pew Research. The economic issues Americans are thinking about include:


  • The cost of living. Most participants in a Pew Research survey said they were very concerned about the cost of healthcare, food, consumer goods, housing, gasoline, and electricity. They also were focused on the role of artificial intelligence in the economy and the difficulty many people are having finding work.


“By a wide margin, voters most want candidates running for Congress to talk about economic issues – with many specifically mentioning prices and affordability,” reported Andrew Daniller, Andy Cerda, Hannah Hartig and J. Baxter Oliphant of Pew.


  • Social Security funding. “A near-unanimous 97 percent of voters nationwide agree candidates should explain their plans to prevent automatic benefit cuts…this is an intergenerational issue: while current retirees will be impacted immediately by automatic cuts, current workers are paying into a system that will pay them less,” according to a survey conducted by the nonpartisan Peter G. Peterson Foundation.


Currently, payroll taxes collected to fund Social Security benefits do not cover the amount paid out each year. The difference is taken from the Old-Age, Survivors Insurance (OASI) Trust Fund. Projections suggest the trust fund will be depleted in 2032. Unless Congress acts soon, all program beneficiaries will see benefits cut by 22 percent, according to the 2026 Annual Trustees Report. The Committee for a Responsible Federal Budget puts the cut at about $16,900 per year for the average couple.


Americans also are concerned about non-economic issues, including government and leadership, immigration, and war in the Middle East, according to a September Gallup poll.


Just as hitters can be enticed into swinging at the wrong pitches, investors can be tempted to make portfolio changes at the wrong times. During this election season, remember to keep your eye on your long-term goals. If you have questions about your portfolio or feel a change may be warranted, please get in touch.


Last week, “was a rollercoaster of a week on Wall Street, but stocks closed Friday's session higher and managed to climb for the week despite the bond yields rising to multi-year highs,” reported Naomi Buchanan of Barron’s. The yield on the 30-year U.S. Treasury bond ended the week at 5.49 percent.

money_grass.jpg

What Do Salt, Cattle, Coins, and a Smartphone Have in Common?


At one time, each played a part in a payment system. In the ancient world, salt and cattle were forms of currency. Today, the wallet app on your phone can pay for your morning coffee. Find out what you know about the history of money by taking this brief quiz.


1.   In the late 1800s, some stores allowed well-heeled customers to charge purchases using a store token. The tokens included the store's name or logo, a customer identification number, and a small hole so the customer could string it on a key ring or necklace. The tokens were often shaped like the goods sold by the issuing store. What were these tokens called?

a.   Razzle dazzle

b.   Charge coins

c.    Credit chits

d.   Plunk downs


2.   In the 1930s, one industry embraced the idea of charge cards. The card offered customers a more convenient way to pay and provided a 15 percent discount on some sales. What did the industry call its card?

a.   The Rail Travel Card

b.   The Motion Picture Show Card

c.    The Air Travel Card

d.   The Coffee-House Card


3.   The first multi-purpose credit card was introduced in 1950. It could be used at 28 restaurants and two hotels, and the balance had to be paid off every month. What material was the card made of?

a.   Aluminum

b.   Plastic

c.    Cardboard

d.   Celluloid


4.   Today, contactless payment lets people pay with a debit or credit card by tapping the card, smartphone, or smartwatch on a payment terminal. Where was the technology first used?

a.   The United States

b.   South Korea

c.    China

d.   Canada


From salt and cattle to cardboard cards and contactless payments, the way we pay has changed dramatically over time. Who knows what will be in our wallets, or on our phones, a generation from now?

thinking_girl_idea.jpg

Weekly Focus - Think About It


“Money is, in some respects, like fire. It is a very excellent servant, but a terrible master.”

— P.T. Barnum, Entertainment Entrepreneur

Bruce Kuehl | 763.542.8884 | bruce.kuehl@avior.com

Answers: 1) b; 2) c; 3) c; 4) b

Investment management and financial planning services offered through Avior Wealth Management, LLC a registered investment advisor. Investments involve varying degrees of risk and there can be no assurance that the future performance of any investment or investment strategy will be profitable or equal past performance results. All investments subject to loss including the loss of principle. Nothing contained herein should be construed as tax advice. Specific, individual tax questions should be asked of your CPA or accountant.


Please remember to contact Avior, In writing, if there are any changes in your personal/financial situation or investment objectives for the purpose of reviewing/evaluating/revising our previous recommendations and/or services, or if you want to impose, add, or modify any reasonable restrictions to our investment advisory services. Unless, and until, you notify us, in writing, to the contrary, we shall continue to provide services as we do currently. Please advise us if you have not been receiving account statements (at least quarterly) from the account custodian. A copy of our current written disclosure Brochure and Form CRS (Customer Relationship Summary) discussing our advisory services and fees continues to remain available upon request or at www.aviorwealthmn.com.