|
Here is a list of the reasons somebody may consider a Reverse Mortgage
There are seniors who:
1) think they want to sell and rent but rentals are hard to find and require a major lifestyle adjustment, not to mention losing a big chunk of cash in their sale in costs and commissions with the inconvenience of moving.
While the sale proceeds from a home can be used to cover rent costs, they lose the potential future appreciated value of their home. Those that sold in the previous 2 years lost out on a significant non-taxable financial gain.
2)are homeowners who have a good pension or thought they had a good pension and there are also those who do not. They may realize that they are having a hard time keeping up with the higher cost of living and just getting by. They need extra non-taxable income.
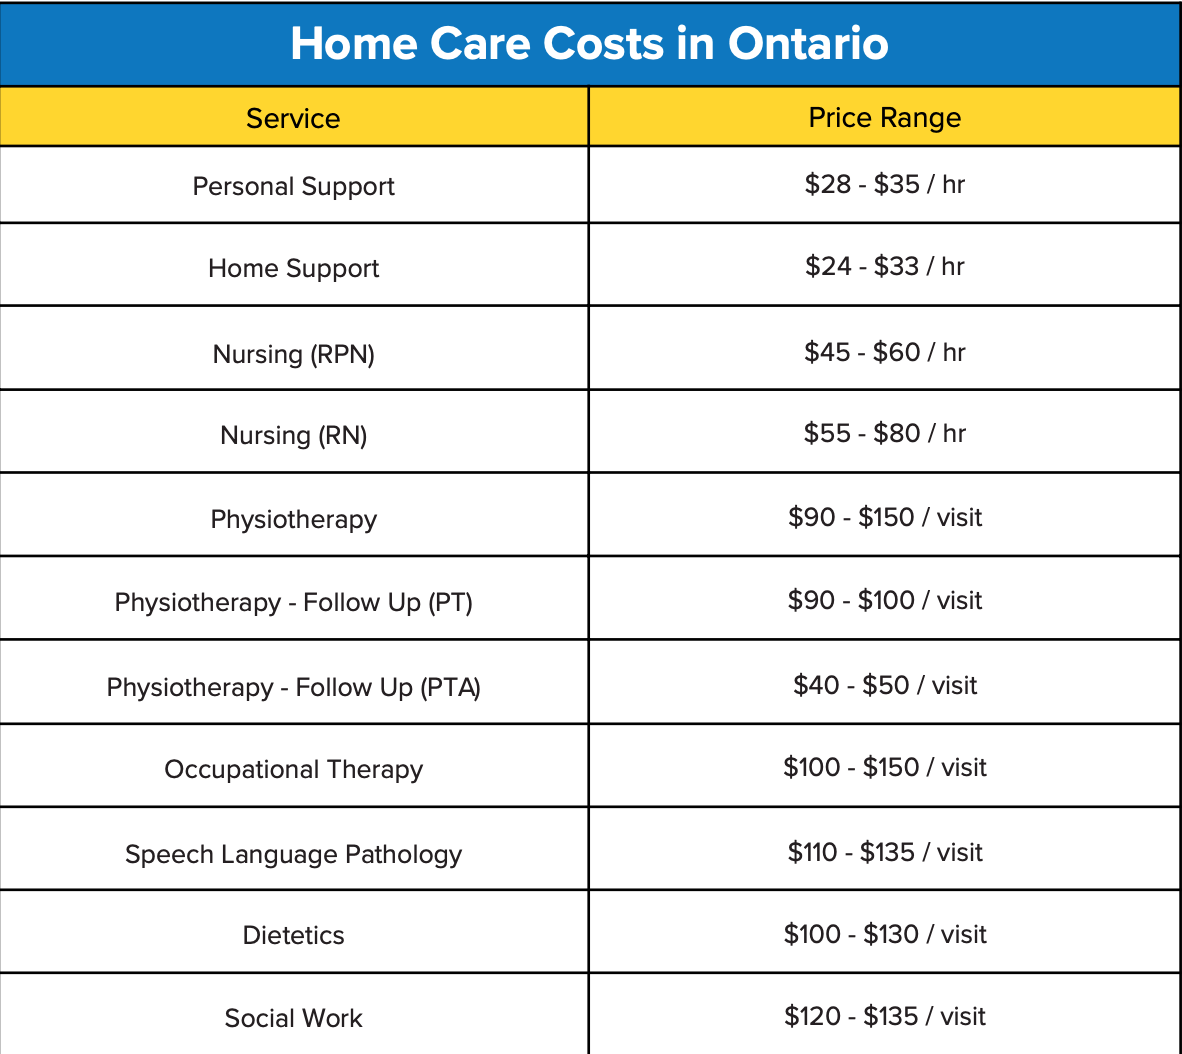
3)do not want to move into a retirement home, especially with the recent Covid impact on senior care. They are worried about how they will keep up with the maintenance and repairs on their home as they age, let alone the costs.
They don’t want to burden their family with the cost of maintaining them in their home as they age but want to stay in their home.
4)might want to give their family an early non- taxable inheritance but don’t want to deplete their savings or investments to do so.
It is an interesting time for first-time buyers trying to get their first home and for some, they need the “Bank of Mom and Dad” to make it a reality or help from their grandparents.
Any early inheritance from parents will be non-taxable whereas the residual value of the sale proceeds of their home may be taxed as part of their estate later on.
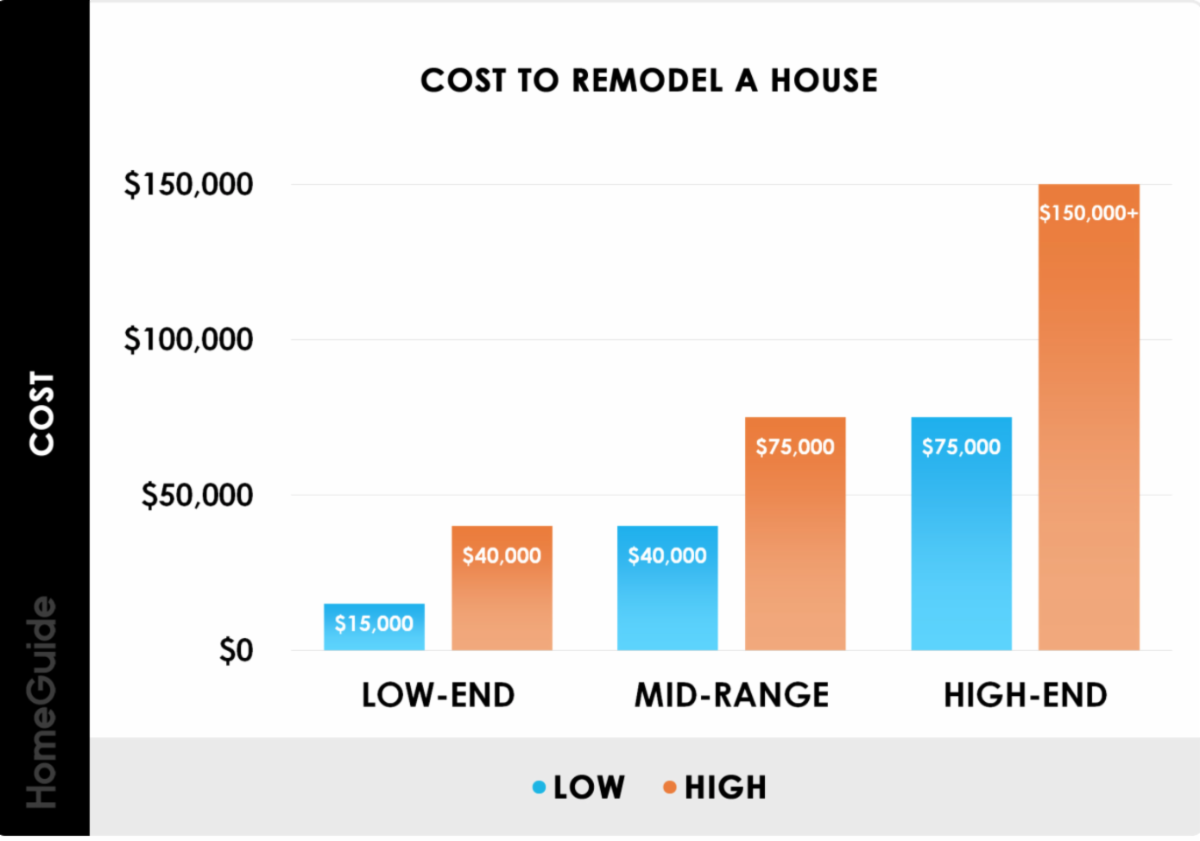
5)wish to renovate their home but don’t have the resources to do it, do not want to deplete their savings, or cannot qualify for regular mortgage financing.
6)could afford to pay for a Line of Credit payment to help them renovate or give them extra cash, but they can’t qualify due to government regulations or don’t want the payment on a tight budget.
With an incentive to stay in their home many seniors are making overdue repairs, renovating kitchens, bathrooms, and more to update their home and that is costly.
7)have debt payments, a mortgage, or a line of credit that are hard on their fixed income budget.
Eliminating those payments will give them so much more financial freedom. A Reverse mortgage can be used as a future "cash bank" or non-taxable income source.
8)would like to be living a better retirement lifestyle but they cannot afford to do so on their current budget.
The Reverse mortgage can provide a tax-free supplement to their monthly income! It can also be an effective tax planning tool for the future.
9)consider selling and paying more for a retirement residence and realize they would have to cash in investments or taxable investments to do so. They may not qualify for a Line of Credit or a regular mortgage or they may not want to have payments.
A Reverse Mortgage can also bridge the gap between what they received on the sale of their home and the cost of a new home.
Some people will also use a Reverse Mortgage when they will have little left between their sale and purchase. By using the Reverse Mortgage they can retain some of their equity for other purposes, such as renovations, a nontaxable income supplement, or other expenses.
They can downsize or move up without the worry of payments.
10)currently have a part-time job because they need the income to make ends meet.
A reverse mortgage can give them extra non-taxable income, so they don’t have to work to live.
11)may want to purchase a recreational property or a winter retreat down South. They may have some investments or cash that they can use but need a bit more to make it happen. They could use a line of credit on your home, which will give them up to 65% of their home's value and pay interest only at a lower rate than a Reverse mortgage or they may not want to have payments.
Typically, a Reverse Mortgage will give you approximately 35-40% of the value of your home depending on your age.
12)want to go South and rent for the winter. With Covid, travelling has been more limited for snowbirds but Covid has also been responsible for significant prices increases in rental accommodation as people still move to the sun in the winter. Longer stays of 1-3 months can be costly and in US dollars with a significant premium. Many people just don't have that money in their retirement budget but are still young enough to hit those 'bucket list" spots.
A Reverse Mortgage can provide funds to cover those expenses without the worry of making payments or paying off credit cards from their retirement income when they get home.
There are a lot of ways to enhance your retirement lifestyle but what is the risk?
The Reverse Mortgage provides the best peace of mind of any other mortgage product in the market.
I am 72,semi-retired and living the retirement lifestyle. I can 'walk the walk" and "talk the talk" about retirement issues. If we both agree that the Reverse Mortgage is a fit and I do my best to ensure you know what you are doing, you will get full disclosure on every detail but the lender will insist you obtain independent legal advice from your lawyer before you finalize. This is good protection for you to ensure you understand the process, costs, and the product and you have made the right decision for your particular circumstances.
I like that!
So that is a pretty extensive list of the reasons why, don't you think?
But then again these reasons may not fit your personal financial situation and you don't need a Reverse Mortgage but your parents might be able to use it. So don't stop now. Order "Part Four"-see below
|