News & Economic Updates

Oct. 1, 2026


Large-Cap Resilience in a 5% Yield Environment

202609

U.S. equities capped off the third quarter by continuing their upward march, underpinned by durable economic growth and resilient corporate fundamentals.

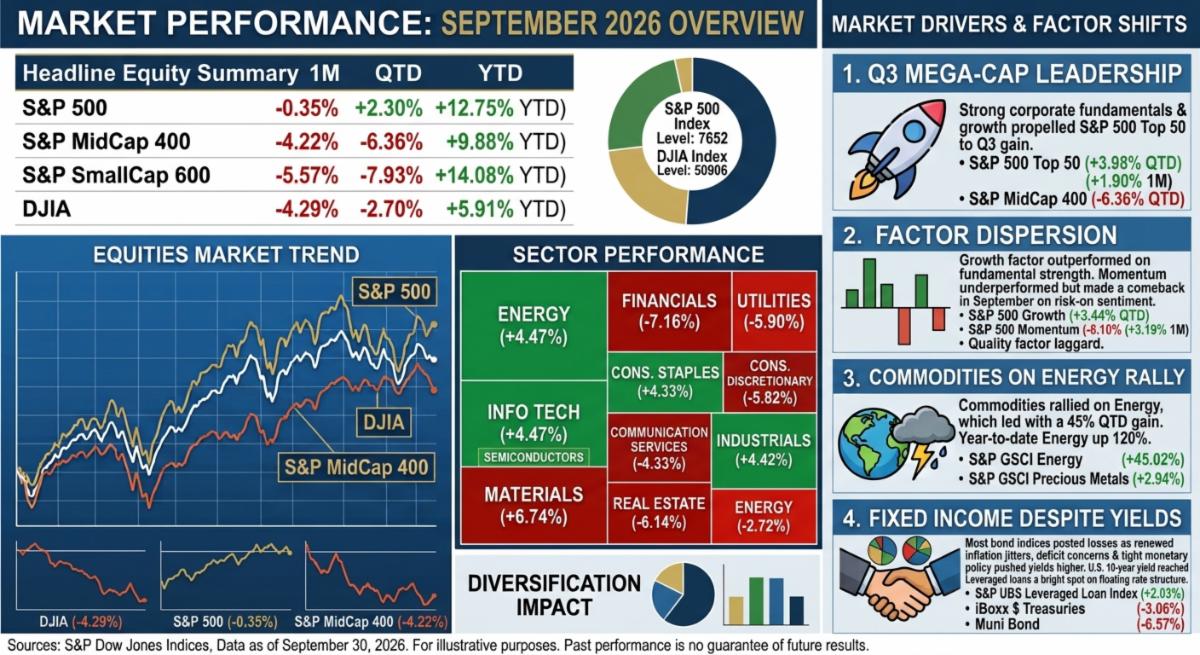
Even as long-term Treasury yields surged to multi-year highs—with the 10-year yield breaching 5% for the first time since 2007—and investors contended with ongoing Middle East geopolitical unrest and debate surrounding AI capital spending, the S&P 500 closed September essentially flat (-0.35% at 7,652) to secure a +2.30% gain for Q3.


While these results are encouraging, the underlying divergence reminds us that staying balanced and disciplined remains as crucial as ever. We will explain these trends in the next edition of the GRAnderson Wealth Monthly Economic Update, due to be posted by the end of this week. 

Large-Cap Dominance vs. Small-Cap Compression

Reversing the broader participation seen in the second quarter, mega-cap leadership reasserted itself throughout Q3. The S&P 500 Top 50 gained +1.90% in September and finished the quarter up +3.98%. In contrast, higher-for-longer borrowing costs placed significant pressure on smaller and mid-sized companies.


The S&P MidCap 400 fell -4.22% in September (-6.36% QTD), while the S&P SmallCap 600 dropped -5.57% (-7.93% QTD). This divergence underscores why disciplined, quality-focused diversification remains essential when navigating late-cycle interest rate pressures.


Sector Divergence: Tech and Energy Drive the Market

Sector returns diverged markedly across defensive and growth segments:


Information Technology & Communication Services: Technology led monthly index performance (+4.47% in September, +7.20% QTD), serving as the single largest contributor to the S&P 500’s Q3 advance (+2.72% sector contribution). Communication Services also rebounded with vigor (+4.33% in September, +3.64% QTD).  


Energy: Powered by an ongoing rally in crude oil, the Energy sector gained +17.23% in Q3, making it the top-performing sector of the quarter despite a mild -2.72% consolidation in September.  


Rate-Sensitive Sectors: The surge in Treasury yields weighed heavily on interest-rate-sensitive areas. Utilities dropped -5.90% in September (-12.39% in Q3), and Financials fell -7.16% for the month (-0.12% in Q3). Industrials (-4.42% 1M, -9.66% QTD) and Materials (-6.74% 1M, -2.81% QTD) also faced headwinds. 


Style leadership shifted over the course of the quarter:

  • Growth and Value Stability: Growth (+1.95% 1M, +3.44% QTD), Value (-3.10% 1M, +0.90% QTD), and Enhanced Value (-5.57% 1M, +0.58% QTD) were the only factor indices to finish the third quarter in positive territory.
  • Momentum Rebound: While Momentum trailed the S&P 500 for the full quarter (-6.10% QTD), it rebounded strongly in September (+3.19%), matching a concurrent rise in High Beta (+3.07%) as risk-on sentiment returned to technology and growth equities.
  • Dividend & Defensive Weakness: Dividend-oriented and lower-volatility strategies experienced notable pullbacks as cash alternatives and high bond yields drew capital away from traditional dividend payers. The S&P 500 Low Volatility High Dividend Index dropped -7.74% in September, and Dividend Aristocrats declined -6.04%.


See this month's GRAnderson Wealth Management Economic Update for details.


Greetings!
If this is your first exposure to the GRAnderson Wealth Monthly Update -- welcome! We hope you receive a valuable amount of information that will help with your investment decisions!
Sincerely,
Gregory Anderson
Founder and CEO
Click here to see the latest issue of the
New issues generally appear the 4th or 5th of every month.

Fixed Income: Navigating a 5% 10-Year Treasury Yield

Persistent inflation jitters, expanding fiscal deficit concerns, and expectations of tight monetary policy drove benchmark bond yields to levels not seen in nearly two decades.

  • The 10-Year U.S. Treasury yield reached 5%, creating substantial repricing across fixed-rate debt.
  • The broad S&P U.S. Aggregate Bond Index declined -2.27% in September (-3.03% in Q3), with the index yield rising to 5.49%. Municipal bonds (S&P National AMT-Free Muni Bond) fell -4.73% for the month (-6.57% in Q3; yield at 4.74%).
  • Floating-Rate Outperformance: Benefiting directly from higher base rates, senior secured loans provided strong capital preservation. The S&P UBS Leveraged Loan Index gained +0.26% in September (+2.03% QTD), offering a current yield of 9.60%.


Broad commodities continued their secular run, with the S&P GSCI advancing +4.79% in September and +25.10% over Q3.

  • Energy Commodities surged +11.82% in September and +45.02% across Q3, driving year-to-date energy commodity returns to an extraordinary +119.95%.
  • Precious Metals pulled back -6.60% in September (+2.94% QTD), as rising real bond yields and dollar strength placed near-term pressure on gold and silver.


Find details about these trends and other statistical categories in our latest Economic Update.

What we're watching at GRAnderson Wealth

Entering the final stretch of 2026, the macroeconomic landscape presents both substantial opportunity and distinct cross-currents. While large-cap corporate earnings continue to surprise to the upside, sustained 5% Treasury yields and elevated energy costs act as a tightening mechanism on consumers and smaller businesses alike.


Market swings can test investor emotions, but a sound financial foundation is built on perspective, not panic. By maintaining a well-diversified allocation, we help ensure your long-term life goals remain secure regardless of shifting macroeconomic currents.


In this environment, active portfolio oversight is paramount:

  1. Rebalancing & Cash Flow Management: Take advantage of high fixed income and short-duration yields to lock in predictable income streams without taking on undue duration risk.
  2. Selective Quality in Equities: Emphasize companies with healthy balance sheets, pricing power, and strong free cash flows that are insulated from high debt refinancing costs.
  3. Year-End Planning: The fourth quarter is an ideal time to review tax-loss harvesting opportunities, assess retirement distribution schedules, and optimize annual gifting or charitable strategies.


We welcome the opportunity to discuss your financial roadmap and portfolio positioning.

Please reach out if you would like to schedule a review:https://calendly.com/grandersonwealth/review


Founded in 2005, GRAnderson Wealth Management Group, Inc., is a registered investment advisory firm specializing in comprehensive financial planning and investment management services for clients with life goals. In addition to traditional investment solutions, value is added with alternative investments in direct ownership in energy, commercial real estate, managed futures and private equity.
GWMG specializes in investing and financial advising for individuals, business owners, 401(k) plans, pension and profit sharing plans, and personal family trusts. 

GRAnderson Wealth Management Group, Inc.
303-228-3160

Stay Disciplined. Stay Diversified.