Upcoming Industry Events

February 4-6

CUES Future Summit - Detroit, MI


February 4-5

The Roundtable 2025 - Horsehoe, Las Vegas


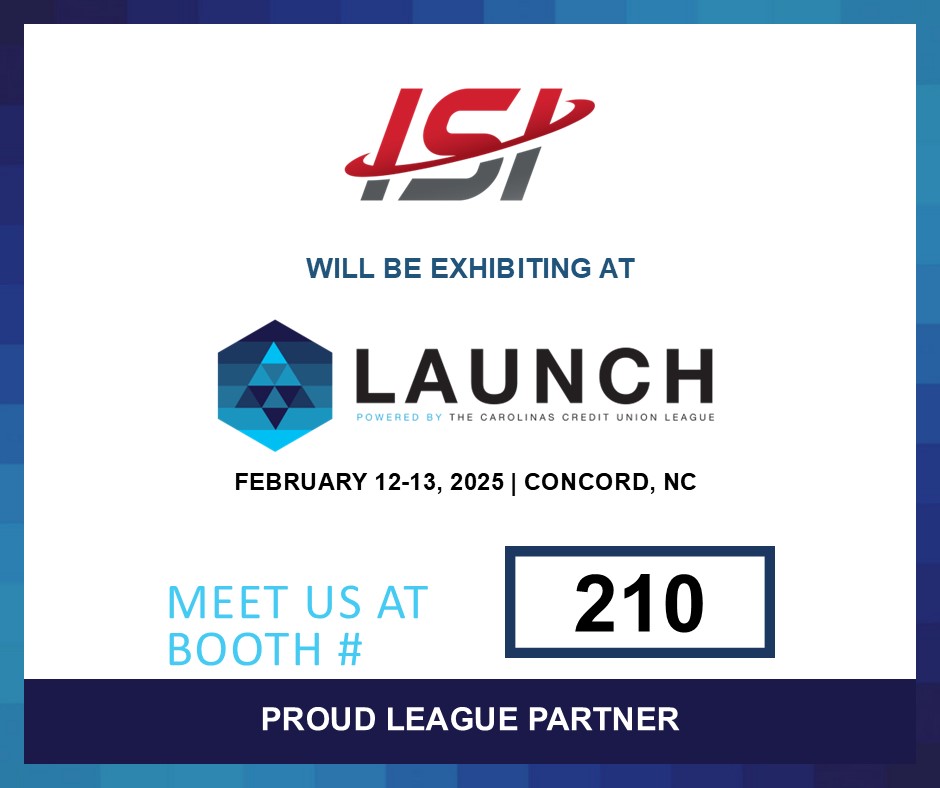
February 12-13

LAUNCH 2025 - Concord, NC

Industry News

Car Insurance Soars for Millions Across 5 States

Auto insurance rates have skyrocketed across the United States in recent years, with premiums rising sharply due to more expensive repairs, severe weather risks, urban congestion, and increasingly risky driving behavior. In 2024, Minnesota and Maryland led the nation with rate increases exceeding 50%, while states like California, Pennsylvania, and Virginia also experienced significant jumps. According to Insurify, full-coverage car insurance premiums rose by 15% in 2024 and have climbed 42% since 2022, outpacing wage growth and adding financial strain for many households. The Consumer Price Index data further revealed an 11.3% rise in car insurance costs over the past year, making it one of the fastest-growing expenses after essential goods like eggs.


Experts anticipate a slowdown in premium hikes in 2025, with projected increases of 5%-7.5%. However, the rising costs remain a concern, particularly in high-cost states like Nevada and Florida. Tariffs on imported car parts could exacerbate repair costs, leading to more expensive claims and potential future rate hikes. As premiums continue to climb, many fear that more drivers may be forced to drop coverage, increasing the number of uninsured vehicles on American roads and creating broader risks for public safety and financial stability.


Read Full Article

newsweek.com

California Wildfires Poised to Drive Up Property Insurance Costs, Moody's Reports

Moody’s analysis highlights the devastating financial impact of California’s recent wildfires, with insured property losses in Los Angeles County projected to reach up to $30 billion—more than double the losses from the 2018 Camp Fire. Uninsured property losses add billions more, emphasizing the state’s high exposure to climate risks. The FAIR plan, California’s insurance safety net, has seen its liability exposure surge from $153 billion in 2020 to $458 billion in 2024. However, its financial capacity remains uncertain, as reinsurance coverage begins only after $900 million in claims—far exceeding its current cash surplus.


To stabilize the market, insurers can now factor catastrophe modeling and reinsurance costs into premiums, including those under the FAIR plan. While this may help retain policies, Moody’s warns that severe wildfire risks may still discourage insurers. Proposed solutions include issuing bonds to cover FAIR plan deficits and introducing legislative oversight. However, rising insurance costs are expected to increase California’s cost of living, affecting property values, consumer spending, and population trends. Moody’s cautions that these measures may offer short-term relief but could undermine long-term economic stability.


Read Full Article

reinsurancene.ws

What Others Are Saying About ISI

"Responses are prompt. Representatives are knowledgeable and incredibly friendly. Any issue that we've ever had was resolved quickly and efficiently."


Grand Heritage Federal Credit Union


See what other Raving Fans are saying about ISI!

Celebrating Milestone Anniversaries This Month

We are thankful for our lender partners, who are essential to our continued success! Listed below are those celebrating milestone anniversaries with ISI this month!


Celebrating 5 Years

Secured Advantage Federal Credit Union


USPLK Employees Federal Credit Union


Celebrating 10 Years

Provident Federal Credit Union


Celebrating 15 Years

Foothills Federal Credit Union


Grove City Area Federal Credit Union


Sun Credit Union

Data/Industry Trends

Auto Loan Interest Rates Set to Fall in 2025, Offering Relief to Dealers and Consumers

Interest rates for new and used vehicle loans began declining in late 2024, with new car loan rates dropping to 6.6% by December from 7.6% in late 2023. Dealers report increased optimism for sales growth in 2025 as financing becomes more affordable. While some industry leaders seek deeper cuts, broader factors like lender competition and used vehicle values are also expected to influence loan rates.

Read Full Article

cbtnews.com

US New Home Sales Exceed Expectations, Rising Supply Curbs House Price Growth

U.S. single-family home sales rose 3.6% in December 2024, reaching 698,000 units, marking a 2.5% increase from 2023. Median prices increased by 2.1% to $427,000. Sales grew in the Northeast and West but fell in the South and Midwest. Despite high mortgage rates, tight inventory of existing homes supported new home sales. Builders are focusing on affordable homes but remain cautious due to rising completed home inventories and an unbuilt backlog.

Read Full Article

reuters.com

February Holidays, Fun Facts, and Folklore!

February is a month of love, reflection, and the gentle transition toward spring. See what this month holds with various holidays, recipes, and more!


Everything you need to know about February

almanac.com

Rising Insurance Premiums and Deductibles: Can Borrowers Afford the Cost?


While your borrower may have insurance, it’s crucial to pay attention to the deductible amounts on their policy. A higher deductible means the borrower will need to cover more out-of-pocket expenses to repair their collateral—be it a home, car, or boat—if it’s damaged. If they can’t afford to pay the deductible, the collateral may go unrepaired, even if insurance is in place. In cases of foreclosure or repossession, this could result in damaged property.


An increase in deductible is often a strategy borrowers use to lower their insurance premiums, which may indicate financial stress. With insurance premiums rising, higher deductibles are becoming more common, but they also point to financial hardships. Consider whether it might be necessary to raise your allowable deductible limit to accommodate these changes. However, it’s important to implement a process for reviewing loans with high deductibles to ensure that borrowers can afford them.

President

ISI

tmaccurdy@isicpi.com

704-957-5024

Connect with Us:
Facebook  Twitter  Instagram  Linkedin  

Contact Info:


Phone: 800-749-5440

Email: management@isicpi.com

Website: insurancesystemsincorporated.com

ISI is an administrator of Collateral Protection Insurance (CPI) and Blanket Lenders Single Interest (BLSI) for financial institutions. We provide insurance, lending, and marketing products to the financial institution marketplace. Our mission is to deliver the best products and services in the industry through responsive service, comprehensive coverage, and advanced technology. We combine the lender's vision and our proven plan to create a portfolio that matches the lender's needs for a successful program and partnership.