Greetings!


Highlights


  • September demand in Metro Vancouver was 25% below the ten year average.
  • Supply in Metro Vancouver in September was 24.3% above the ten year average.
  • Metro prices are down in all segments compared to September 2025.
  • Westside remains a buyers’ market overall.
  • Westside supply of 708 is almost at the ten year average of 703 units.
  • Demand is 22% below the ten year average and down 11% over last year.
  • Strategic pricing is critical for sellers as buyers are very price sensitive.


Market Snapshot


Westside sales Demand is down from the 10 year average by 22% for detached homes, down 24% for apartments and down 4% for townhomes.


Westside Supply is at the 10 year average for detached homes, up 7% for apartments, and 72% for townhomes.


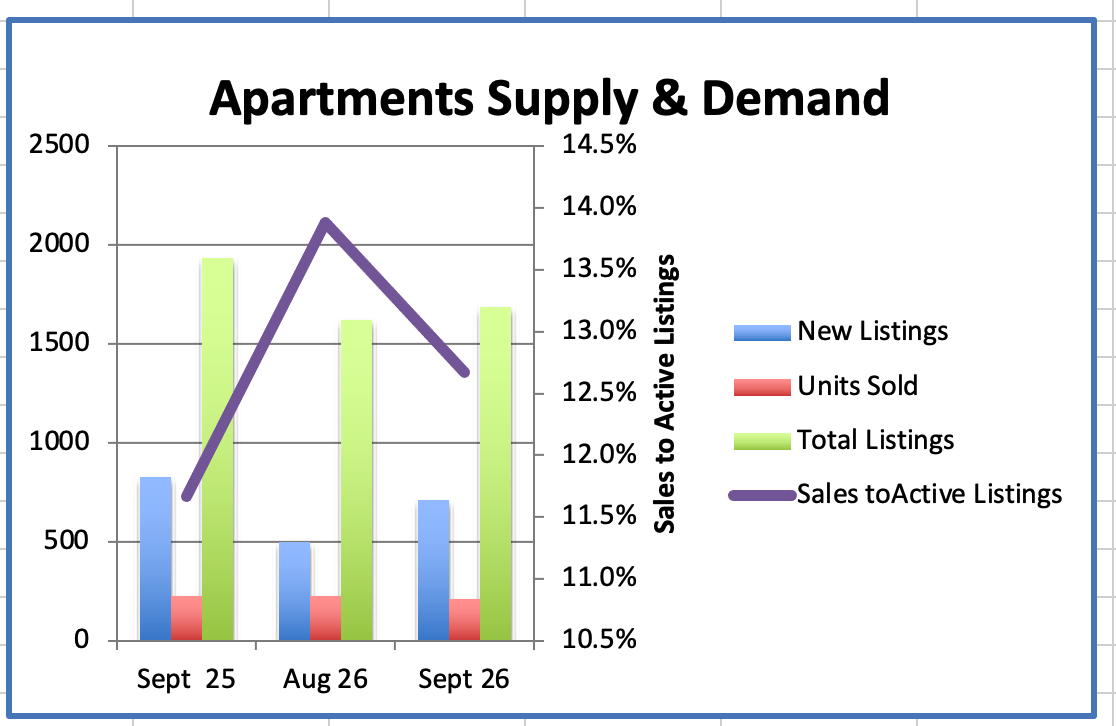
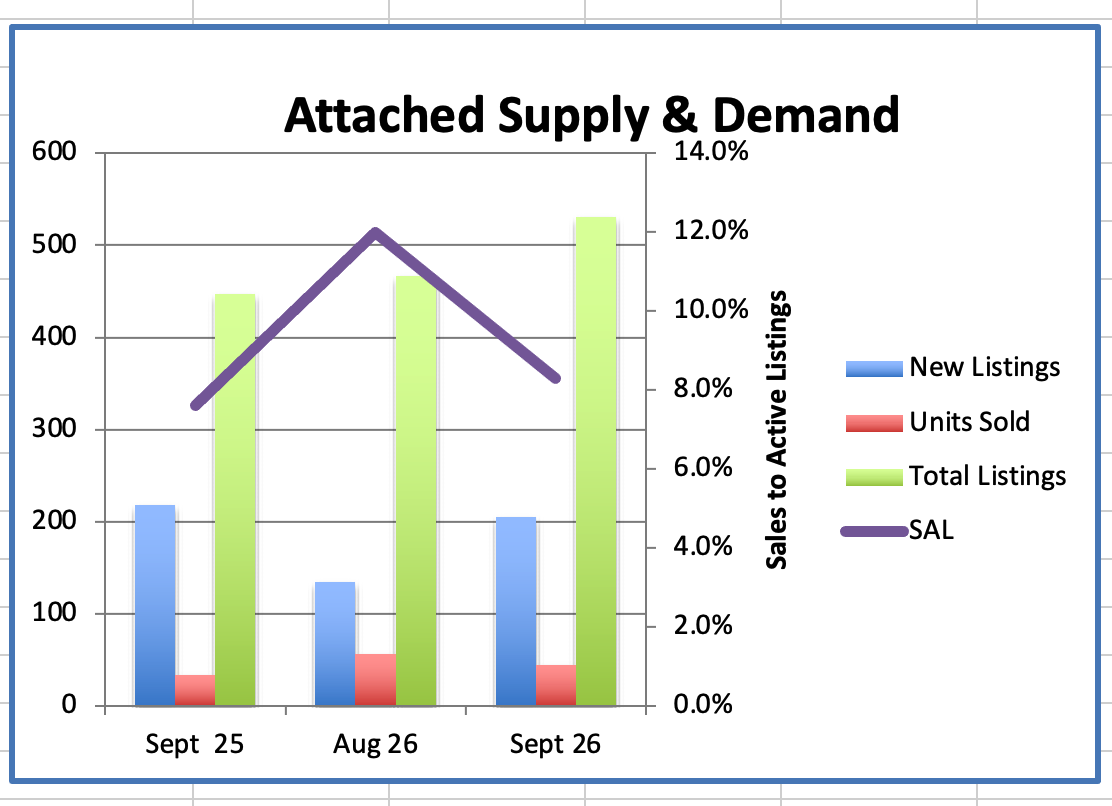
Year over year, Westside detached sales decreased to 48 (down 11%), apartments declined to 214 (down 5%), and attached homes increased to 44 (up 29%).


Pricing


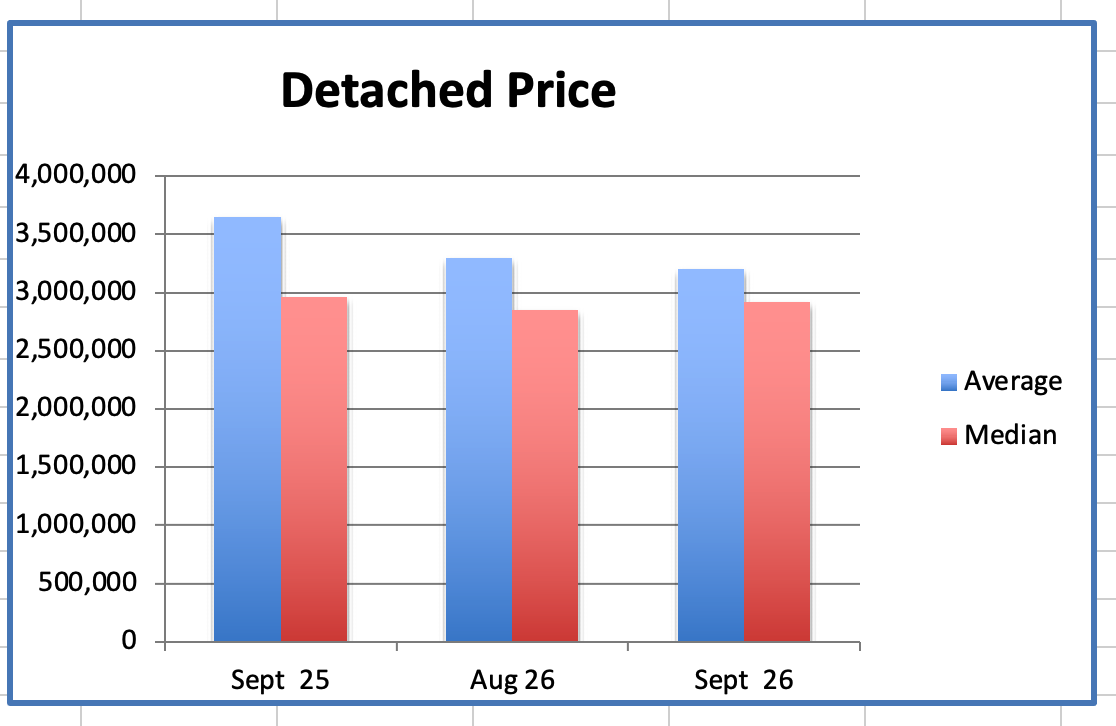
Detached house average price is $3.2M, down 33% from the 2023 peak.

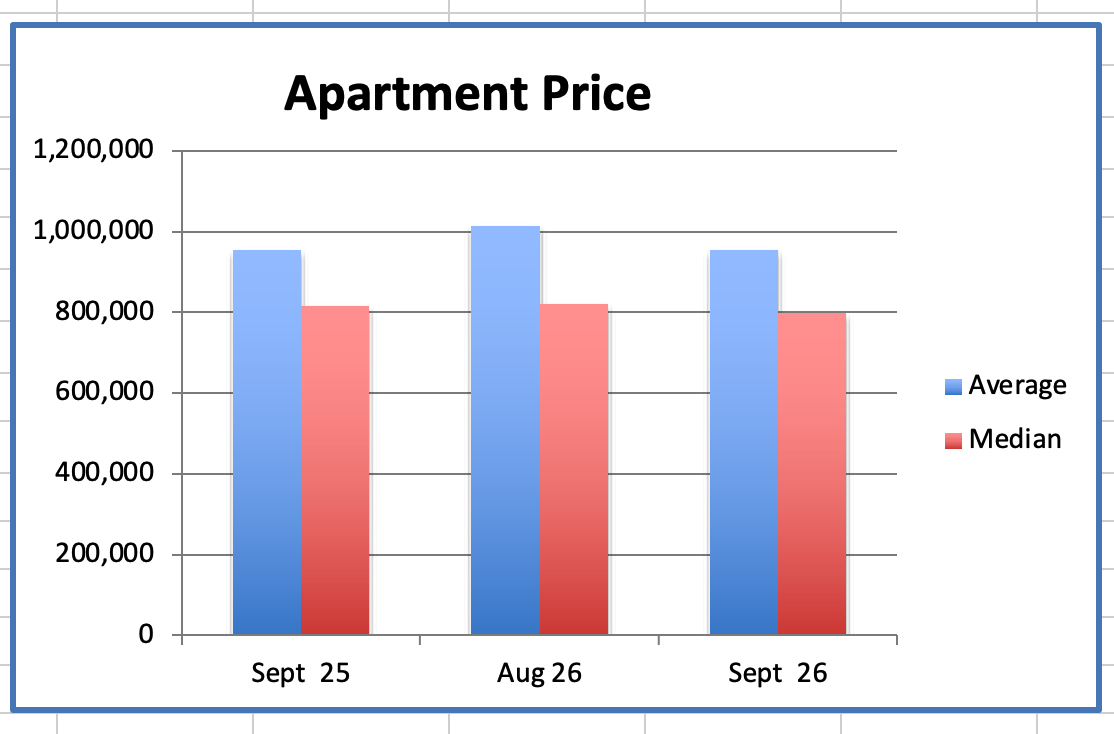
Apartments average price is $954K, down 20% from the 2018 peak.

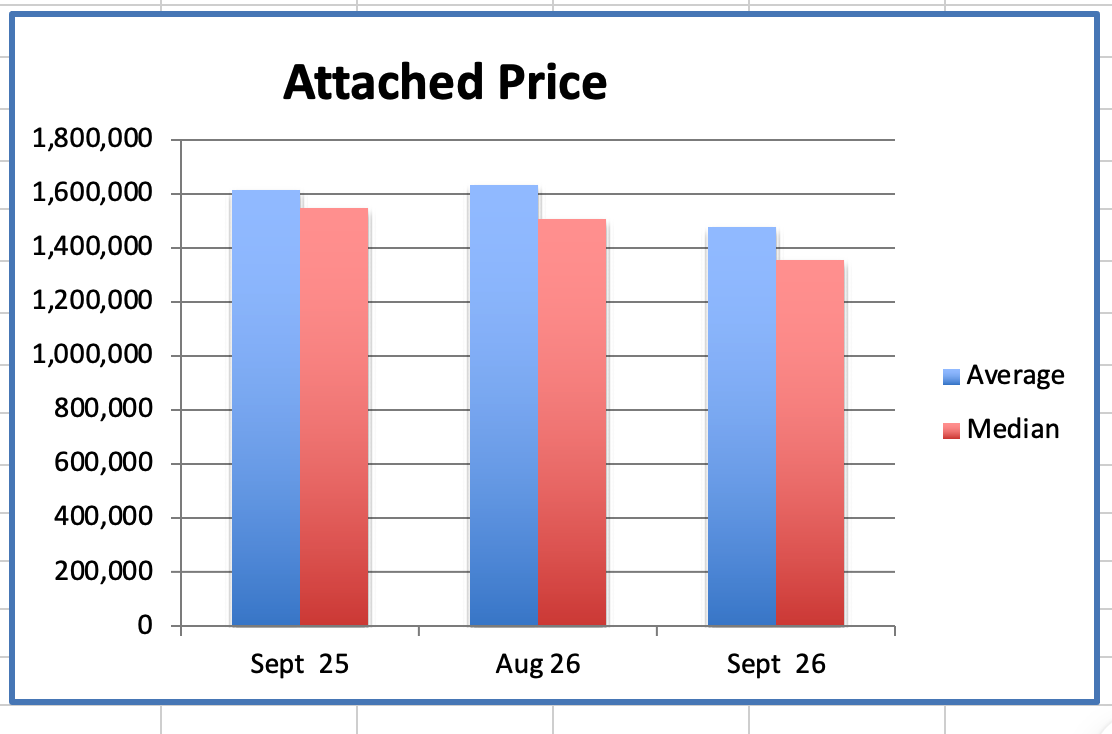
Attached homes average price is $1.48M, down 22% from the 2024 peak.


Market Balance


The West Side sales to active listings ratio shows all segments in decline:

  •  Detached at 6.8% (buyers’ market)
  •  Attached at 8.3% (buyers' market)
  • Apartments at 13% (balanced market)


The Sales to Active Listings ratio (SALR) is a key indicator of market balance and it helps determine whether the market favours Buyers or Sellers. The range between 12% and 20% is considered a balanced market and prices are sustained.


Downward pressure on home prices occurs when the SAL ratio dips below 12% for a period of time. Upward pressure on home prices occurs when the ratio trends up and particularly when it surpasses 20% over several months.


Currently the SAL ratio for westside detached homes is 6.8% allowing prices to decline. The SAL ratio for attached homes is 8%, not quite sustaining prices and the SAL ratio for apartments is level at 13%, balanced market territory, which is allowing prices to recover slightly from Dec & January.


Outlook


The lowest priced west side detached homes are being bought by investors and builders while most end users are competing for updated homes in move in condition.


Supply was up in September from August & Demand was flat in September so the SAL and prices continue to decline, creating good opportunities for buyers. Successful sellers are pricing sharply!   


Apartment supply is also up in September and demand is down and that is turning prices from a slow rise in the spring to to a peak in August and off again this September. Fewer new strata apartment projects are coming to market as foreign buyer restrictions and zoning incentives favour rental construction. This is increasing rental supply, but it is resulting in a decline in the supply of apartments for sale. So while rents may need to adjust down to compete with the increase in rental supply, the decrease in β€œFor Sale" inventory should strengthen prices for apartment resales in the future.


Westside Townhouse supply also took a jump in September, up 19% over September last year and up 14% over last month, while demand is up 29% from September 2025 but down 21% from last month. The end result is that the SAL ratio is down which is causing prices to decline. The new R1-1 zoning is encouraging builders to create the many half duplex and Multi development units that are now on the market giving buyers more options.


Affordability remains a key driver. Buyers are focused on well priced homes that offer real value, with less emphasis on speculation. Sellers who need to move are pricing sharply to meet the market and are selling within 2 - 3 weeks. Builders are buying land value properties for conversion to new multi, duplex and single family homes with revenue suites & laneway homes.


Many of these units are sitting as the prices are not generating the anticipated profits for builders and Premier Eby is now contemplating a tax on these vacant and unsold units which will not help stimulate more building.


ο»ΏClick here for Westside Report


Buyer Takeaways


  • This is a buyers' market and a good opportunity to get into a home or to move up.
  • The market sales volume seems to have peaked in June and has come off as is typical in July & August which is a sign for buyers to get buying.


Seller Takeaways


  • To sell successfully, be the best value in your category
  • Prepare your home properly: Declutter, Paint & Repair and Clean, Clean, Clean!
  • Price strategically from the start!


Thinking of Buying or Selling? Let’s Talk!


πŸ“ž Call me today to discuss your options and make the most of the upcoming selling season.


Happy Thanksgiving! πŸπŸ¦ƒπŸ½πŸ₯§πŸˆ


Best regards


Stuart β›³ 🎾

Detailed information on the Westside detached (freehold) homes market in September. Here's a summary of the key points:


  • Supply:
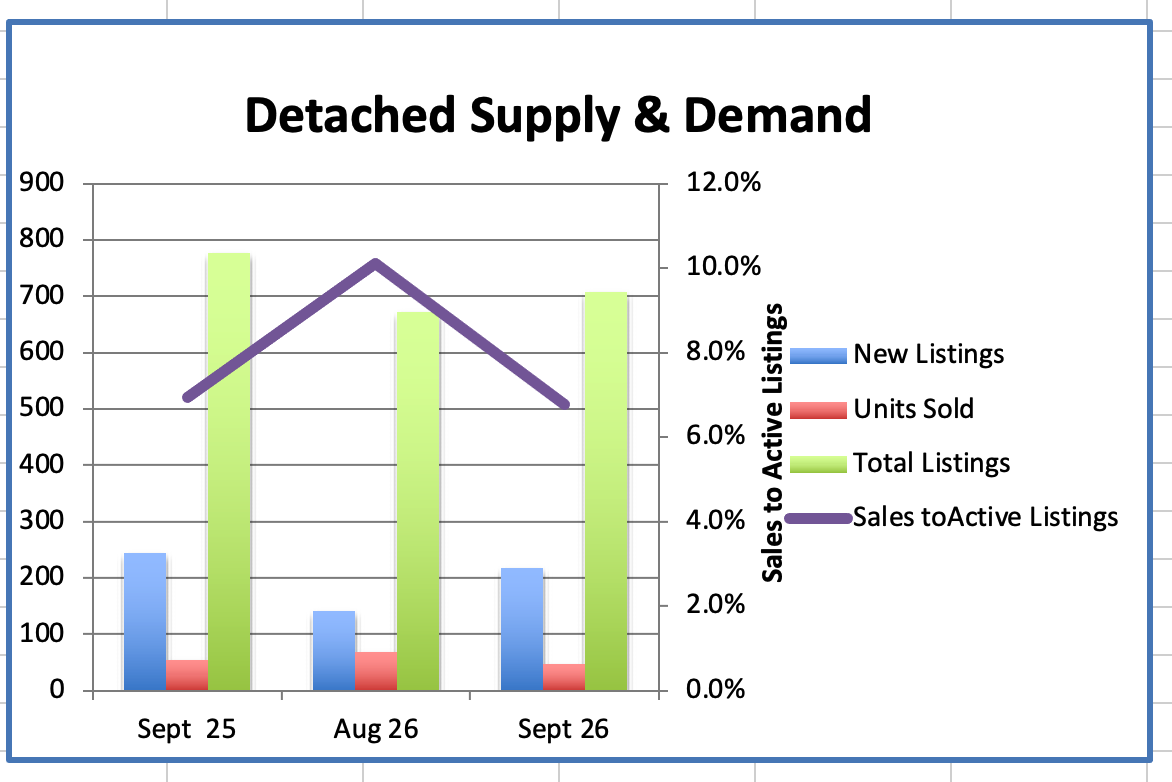
  • In September, the supply of Westside detached homes increased 5.4% compared to August, with a total of 708 homes available, up from 672.
  • This is down 9% compared to September 2025 when there were 777 homes on the market.
  • Demand:
  • Sales of Westside detached homes in September. were down 29% from August, with 48 homes sold.
  • Sales were down 11% compared to September. 2025, which had 54 sales.
  • The number of sales remains 22% lower than the ten-year average of 61 sales.
  • Sales to Active Listings Ratio (SAL):
  • The SAL in September decreased by 33% from the previous month, with a current SAL of 6.8% compared to 10% in August.
  • This is a decrease of 2% from the SAL of 6.9% in September 2025.
  • An SAL between 12% to 20% is typically considered a balanced market, where prices tend to remain relatively stable.
  • Pricing:
  • The average detached home price in September decreased 32% and median decreased 31% from August 2023's peak.
  • The average price is $3.2 million, and the median price is $2.9 million.
  • Current prices are down 3% average and up 2% on median from last month.
  • High and Low Sale Prices:
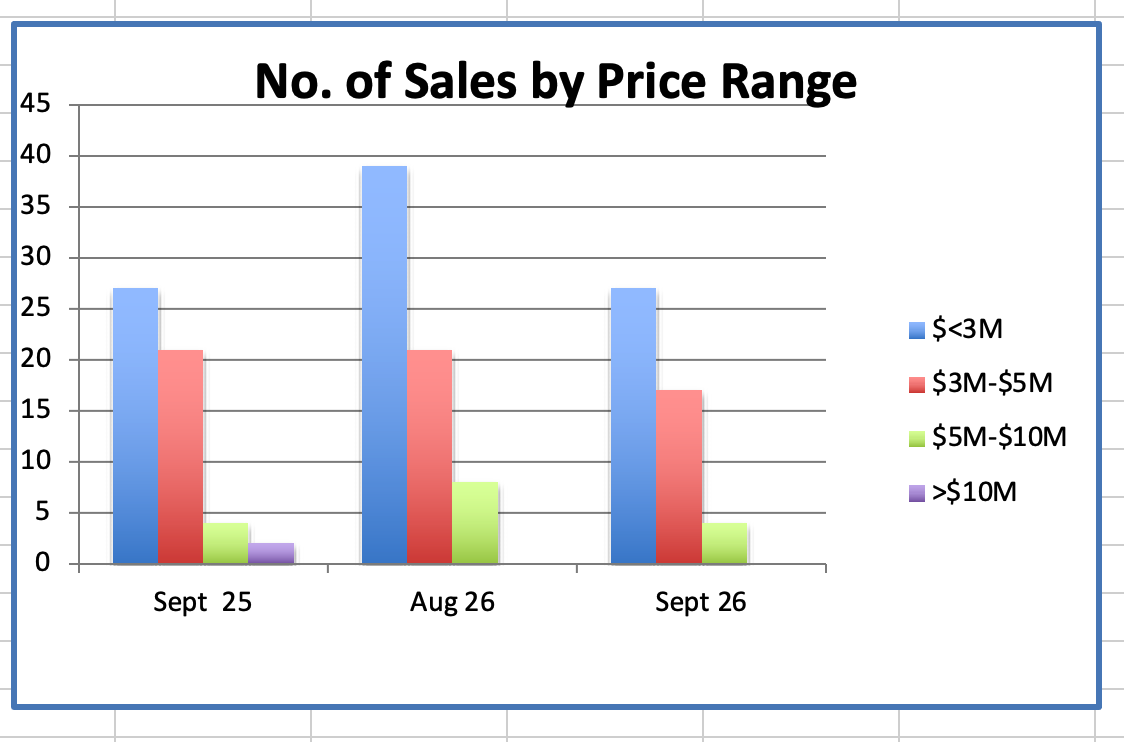
  • Westside detached home sales in September ranged from a low of $1.75million to a high of $6.25 million. The most expensive property took 6 days to sell, while the least expensive took 165 days.
  • Of the 48 homes sold, only 2 sold at or above their asking price, indicating a buyer's market.


These statistics provide a comprehensive overview of the Westside detached homes market in September shedding light on changes in supply, demand, pricing, and notable sale prices.

Detailed information on the Westside apartment market in September. Here's a summary of the key points:

  • Supply:
  • In September, the supply of Westside apartments was up 4% compared to August, with a total of 1,689 apartments available for sale.
  • This number is down by 13% from September 2025.
  • Demand:
  • Demand for Westside apartments was down 5% in September with 214 sales compared to 225 in August.
  • The number of sales in September was down 5% from the same month last year, which had 226 sales.
  • Apartment sales are down 24% from the ten-year average of 280 sales.
  • Sales to Active Listings (SAL):
  • The SAL in September decreased 9% compared to August, to 12.7%.
  • This is up 9% from the SAL of 11.7% in September 2025.
  • An SAL between 12% to 20% is typically considered a balanced market, where prices tend to remain relatively stable.
  • Prices:
  • The average price of Westside apartments in September was down 6% from August, with the average price at $956K v $1013K.
  • It was relatively unchanged from September 2025 ($955K).
  • The median price was down 3% at $799K and is down 2% from September 2025.
  • Average prices are down 20% below the peak of $1,199,000 in January 2018, and median prices down 10% below the peak of June 2024.

These statistics provide a comprehensive picture of the Westside apartment market in September, highlighting changes in supply, demand, pricing, and their respective trends over time.

Detailed information on the Westside townhouse market in September. Here's a summary of the key points:

  • Supply:
  • In September, the supply of Westside townhouses was up 14% compared to August, with a total of 531 townhouses available for sale.
  • The supply was up 19% from September 2025, which had 447 townhouses on the market.
  • Demand:
  • The demand for townhouses in September decreased 21% from last month with 44 sales.
  • The number of sales in September increased 29% from the same month last year, which had 34 sales.
  • Attached home sales are 4% below the ten-year average of 46 sales.
  • Sales to Active Listings (SAL):
  • With an increase in supply and an decrease in demand since last month, the current SAL for townhouses decreased by 31%, to 8.3%
  • This is 9% higher than the SAL of 7.6% in September 2025.
  • An SAL between 12% to 20% is typically considered a balanced market, where prices tend to remain relatively stable.
  • Prices:
  • The average price of townhouses in September was $1.48 million, down 10% from August at $1.63 million.
  • It was down 9% from September 2025 when the average price was $1.61 million.
  • The median price in September was $1.355 million, down 10% from August and down 12% from September 2025.
  • Average prices for townhouses are down 22% from its peak. Median prices down 27% from its peak. The average peak of $1.885 million in Dec 2024, and the median peak of $1.855 million in Dec 2024.


These statistics provide a comprehensive overview of the Westside townhouse market in September, indicating changes in supply, demand, pricing, and their respective trends over time.

Facebook  Twitter  Linkedin