|
Step 1 – Determine Total Super Balance (TSB)
Total super balance of all funds of an individual at 30 June each year.
Generally, it will be the amount that shows on your superannuation member statement each year (or adding up several member statements if you have super in multiple funds)
Step 2 – Determine Realised Earnings
Start with the fund’s taxable investment income, i.e. all the things a fund would normally pay tax on – rent, interest, dividends (including franking credits), capital gains (discounted where relevant) less tax-deductible investment expenses.
Concessional contributions are not included in the calculation because Division 296 tax is about taxing investment earnings, not contributions.
Also:
- For Division 296 calculations, adjustments to taxable income to account for the fund paying pensions are ignored.
- Division 296 fund earnings can never be negative.
When it comes to selling assets and realising capital gains:
- Capital gains and losses are treated in the normal way – i.e., capital losses (including those carried forward before 1 July 2026) are offset against capital gains and only the net amount (less a 1/3rd discount for assets owned by the fund for more than 12 months) is included.
- Capital gains are included in Division 296 fund earnings in the same year they’re included in the fund’s taxable income. Unlike the Government’s original proposal, however, there is no tax on unrealised capital gains.
- There are also special rules for funds that have substantial unrealised gains on assets they haven’t sold yet at 30 June 2026– this is explained later.
Step 3 – Calculate Proportion Above Threshold
Proportion above $3M
= (TSB – $3,000,000) / TSB
There is a special rule for the first year, 2026/27.
Only the end of year TSB will be taken into account when calculating the proportion.
This means if your balance is less than $3m in super at 30 June 2027 you will not pay Division 296 tax for 2026/27 no matter how much you had in super at the start of the year.
Step 4 – Apply Additional Tax
Division 296 Tax = Relevant earnings × proportion above threshold × tax rate
Tax rates:
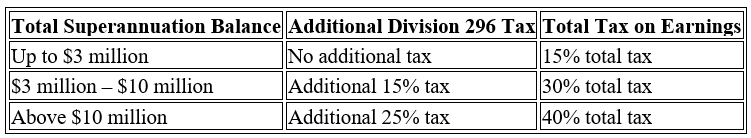
- 15% for balances between $3M and $10M
- 25% for balances exceeding $10M
Capital Gains Relief at 1 July 2026
There is special relief to protect the historical growth in asset values from Division 296 tax when working out how much of the fund’s capital gains should be included in Division 296 fund earnings.
The treatment is different for SMSFs compared to other funds such as industry and retail funds.
SMSF Cost Base Adjustment
For SMSF’s there is a special adjustment to the cost base of all the assets that are owned at 30 June 2026 i.e., a reset to market value at 30 June 2026 rather than original purchase price.
For example, a property it purchased in 2017 for $1.2 million. At 30 June 2026 it’s worth $2.2 million. It’s sold in 2028 for $3 million.
The SMSF will pay income tax on all of the capital gain (less the 1/3rd discount). The amount subject to tax would be $1.2 million ($3 million less $1.2 million, discounted by 1/3rd).
No changes to previous treatment.
For Division 296 tax, the amount included in earnings is reduced. The gross capital gain is calculated as the $3 million less an adjusted cost base of $2.2 million, being the value of the property at 30 June 2026. With the 1/3rd discount applied, this amounts to a net capital gain of $533,333, which is included in the Division 296 fund earnings rather than $1.2 million.
The relief will not be automatic; the fund will have to specifically opt in before it’s 2026/27 tax return is due.
If you choose to opt into the adjusted cost base rules it is an “all inn” scenario, i.e. you cannot use the adjusted cost base for a particular asset (e.g. property) and not others (e.g. shares).
If your fund has certain assets in a loss position at 30 June 2026 you will need to consider whether the relief is worthwhile before making the decision.
For example, an investment in a managed fund was acquired in 2019 for $1.5 Million. At 30 June 2026 it is worth $900,000. The managed fund is then sold in 2029 for $1.5 Million.
If you choose to opt in, then for the purposes of Division 296 your gross capital gain is calculated as the $1.5 million less an adjusted cost base of $900,000, being the value of the managed fund at 30 June 2026. With the 1/3rd discount applied, this amounts to a net capital gain of $400,000.
If you chose not to opt in, for the purposes of Division 296 there would be no capital gain as the sale price of $1.5 Million is equal to the original purchase of $1.5 Million.
Other funds (Non SMSF e.g. AustralianSuper, Hesta or Cbus)
Non SMSFs will not adjust cost bases of existing assets or make other adjustments that are specific to the actual investments held at 30 June 2026.
Instead, for the first 4 years (2026/27 – 2029/30 inclusive) there will be an arbitrary reduction (to be set out in the regulations) in the fund’s net capital gains. More detail will be provided in the regulations.
Case Studies
|