August 13, 2026 | BWE Arizona | Putting clients first. Trusted to be part of their future. | | | Agency
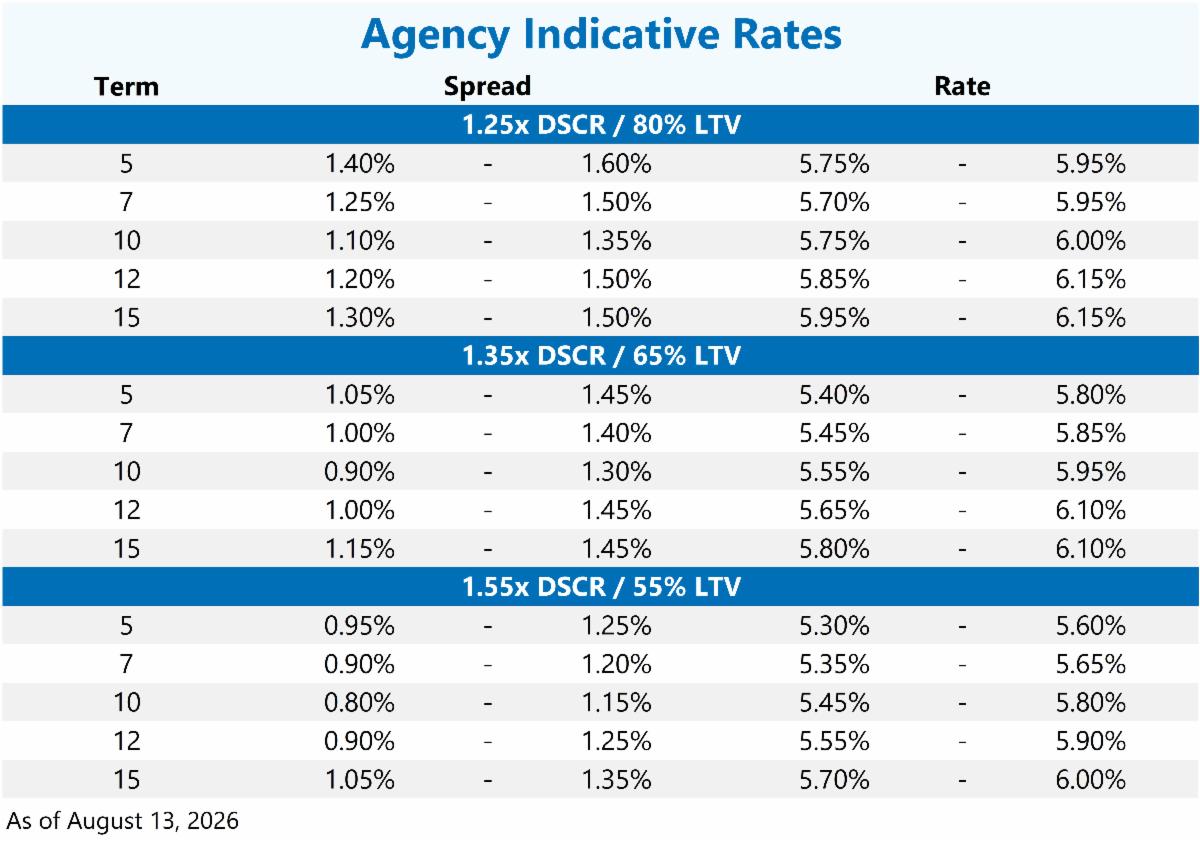
5.45%
0.80% + 10yr UST
Low leverage multifamily refinance | Life Company
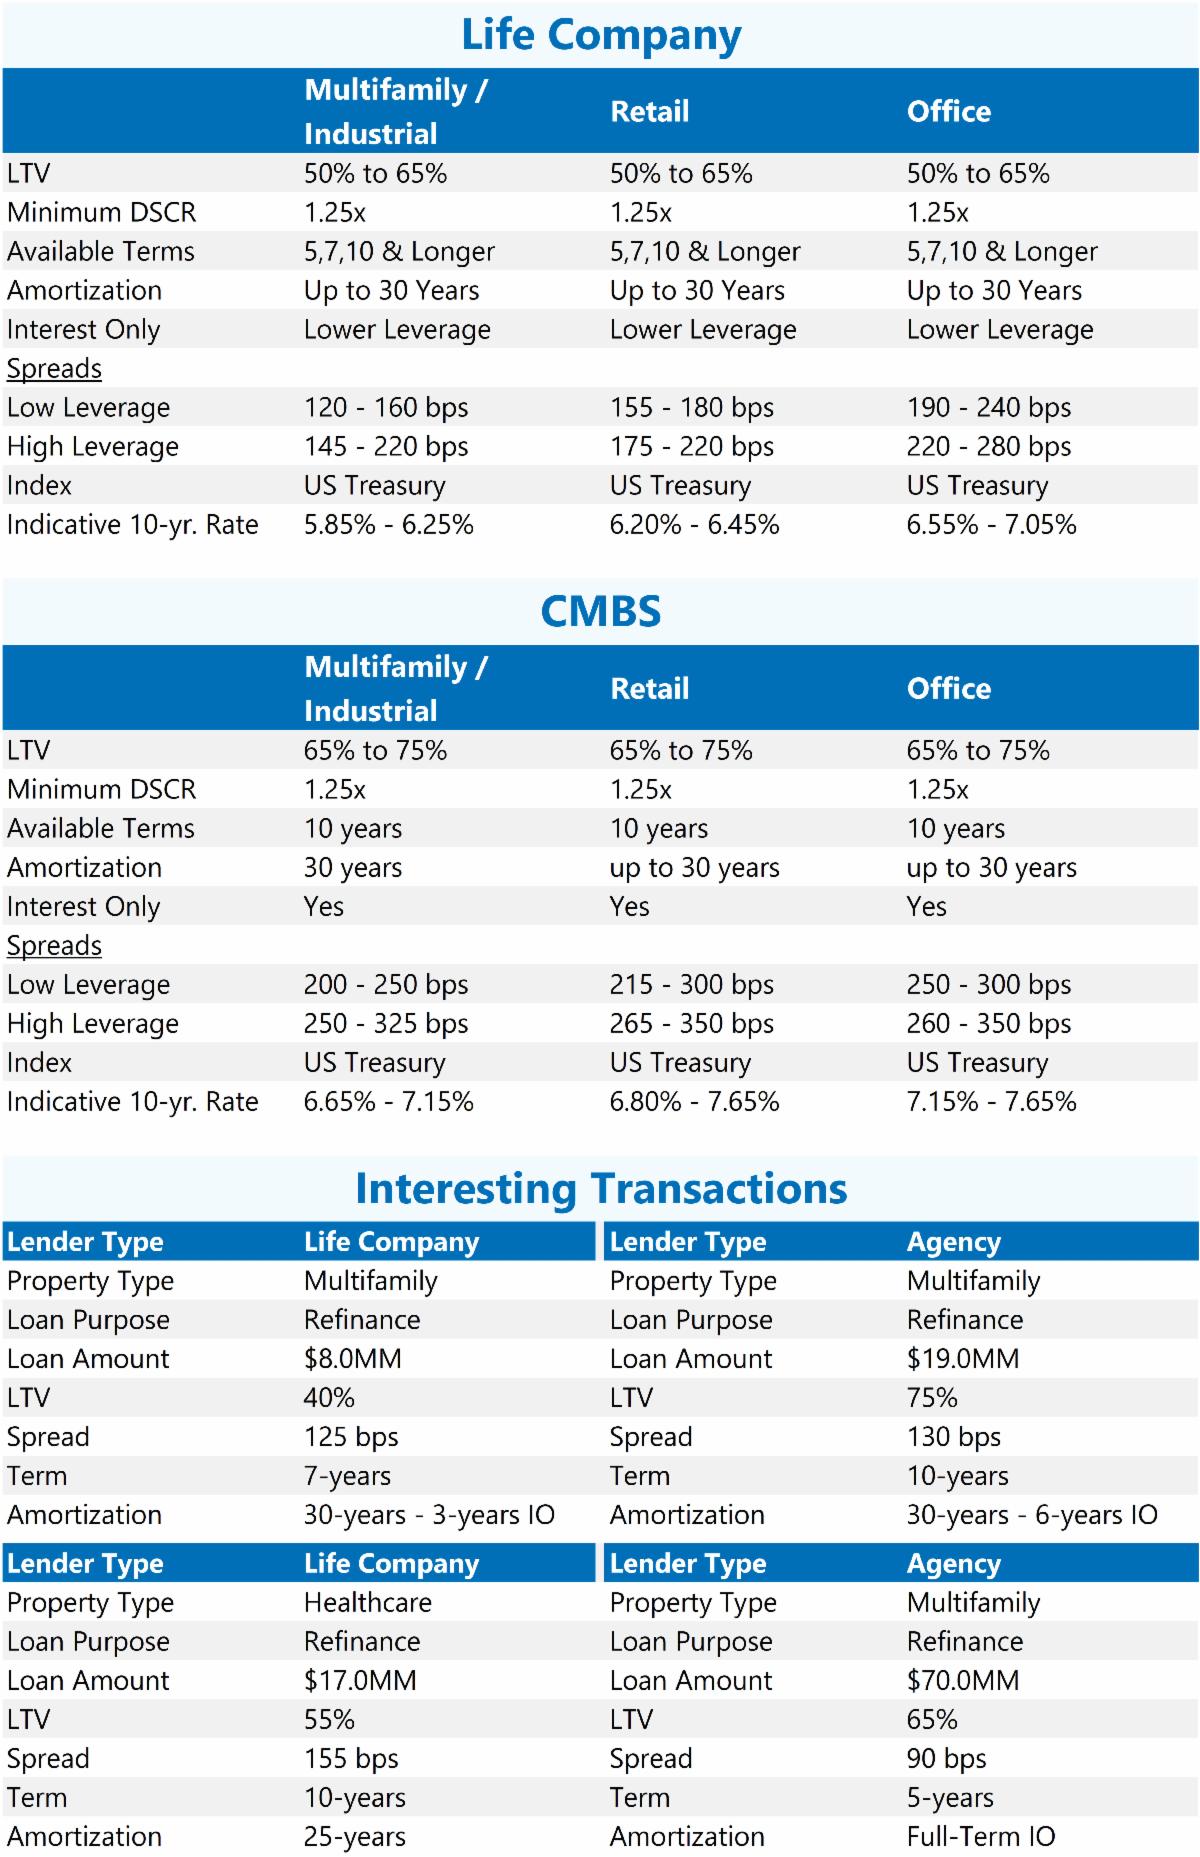
5.85%
1.20% + 10yr UST
Low leverage multifamily refinance | | | |
Key takeaways
- Moderating inflation data this week has extended the Fed's perceived runway before implementing potential rate hikes, with swap markets now pricing in only a 33% probability of a September FOMC rate increase—down sharply from 70% at month-end.
- The week reflects a constructive inflation narrative that has pulled forward expectations for Fed patience, albeit with ongoing vigilance toward labor market resilience and the durability of demand trends into late summer.
Inflation & Monetary Policy
CPI report (July)
- Headline CPI: +0.1% monthly, +3.4% annualized—both aligned with expectations
- Energy prices provided relief with a 1.5% monthly decline in the energy index
- Core CPI (ex-food, energy): +0.2% monthly, +2.5% annually—matching its slowest pace since March 2021
- Takeaway: Fed officials have breathing room to balance disinflation progress against recent labor market softening
PPI report (July)
- Headline PPI: Flat month-over-month (vs. +0.2% expected) and 4.7% annualized (vs. 4.9% expected)
- Core PPI also beat expectations on a monthly basis
- Takeaway: Broad-based softening in producer-side inflation pressures
Fed rate expectations
- September rate hike odds have collapsed to ~33% from ~70% at end of July
- FOMC Meeting Minutes (July 29) will be released Wednesday, August 19 at 2:00 PM EST
Fixed income and Treasury markets
- Treasury yields rallied modestly yesterday after CPI, then gave back gains before recovering this morning
- 10-year benchmark yield trading near 4.61%–4.73% range (currently at lower end)
- MOVE Index (bond volatility) approaching one-year average; moderately down from July end-of-month
- Strong investor demand for 3-year and 10-year auction paper; 30-year $25B auction scheduled for this afternoon
Geopolitical risk factor
- Markets will continue monitoring Iran/Strait of Hormuz developments, though escalation risk appears contained for now. The coming week's data—particularly retail sales, jobless claims, and PMI readings—will test whether recent disinflation progress is durable or temporary.
| | |
Agency CMBS activity was slow last week. New issue Fannie Mae DUS/MBS recorded approximately $600 million in rate lock transaction volume, below the $741 million four-week moving average. Rate lock volumes were split evenly between 5-, 7-, and 10-year standard, liquid structures. Investors continue to prefer plain vanilla structures, larger loan sizes of $25 million or greater, full-term interest only, and loans featuring an interest rate buydown.
Investors have also started to show some preference for longer duration loans of 10 years or more. Fannie Mae DUS/MBS investor spreads were flat over the week. Freddie Mac issued approximately $600 million in Participation Certificates, a notch below its average weekly pace. It priced its ML-36 $357 million Tax-Exempt CMBS. Corporate investment-grade issuance was robust last week at nearly $80 billion compared to $50 billion anticipated. That single week nearly matched the roughly $95 billion that August has averaged in full since 2019. This volume was buoyed by heavy AI infrastructure issuance. Corporate credit spreads were relatively flat week over week despite the heavy volume.
Quick hits
- Last week, $267MM of Fannie floaters traded in the market, demonstrating a growing interest in floating rate loans in the current environment.
- Freddie Mac’s published pricing grids show 5.44%–5.64% note rates on floaters versus 5.77%–5.97% on 5-year fixed. While these grids do not consider property and borrower specifics, it generally shows there is some arbitrage between floating and their shortest duration fixed term at the base pricing level.
- Demand is largely driven by flexibility offered by the floating rate loan, the ability to refinance into fixed-rate debt at a more attractive point in the cycle without being tied to a long-term prepayment structure. Agency floaters remain competitive with bank and bridge executions, allowing borrowers similar flexibility while accessing Agency capital.
- Proceeds are sized to the fixed-rate equivalent; prepay is generally locked out in year 1, then 1.00% thereafter.
- Freddie Mac remains the most aggressive of the Agencies on acquisition financing opportunities as well as stabilized loans.
- Fannie Mae enhances the Near Stabilized Program with a “Pre” Stabilized Execution allowing borrowers to rate lock and close even earlier in the stabilization process.
- Contact BWE to determine if your project is a fit as this is very much a pilot program. Only a small amount of loans has been executed through this more aggressive structure. This is not an official program offering at this point, but something Fannie is willing to do and BWE is pursuing for its borrowers.
- 12 months allowed for the timeframe between rate lock and stabilization in Pre Stab versus 4 months in the current Near Stab program.
Loan highlights
Freddie Mac multifamily acquisition in Falls Church, VA
- $33.5 million (sponsor's first Agency loan)
- 55% LTV / 1.35x DSCR
- 7-yr term / FTIO
- 102 bps spread with no buydown
Fannie Mae new construction takeout in Westerville, OH
- $70 million (under Near Stab program)
- 65% LTV / 1.35x DSCR
- 10-yr term / FTIO / 30-yr amort
- 90 bps spread inclusive of 2% buydown
| | Life Company lenders have reported a steady stream of loan request activity, albeit a little slower due to the summer season and the continued impact of the volatile U.S. Treasuries. Capital remains plentiful for short- and long-term durations. Indicative spreads remain unchanged, generally landing in the range of 150-180 bps, with outlier pricing down to the low 100s for highly desirable opportunities. Lenders have shown they can tighten their spreads by 5-10 bps to “win the deal,” especially on loan requests with lower leverage and higher debt service coverage and debt yields. | | |
U.S. CMBS issuance has slowed in recent weeks and now totals approximately $76.7 billion YTD, in line with the $74.0 billion level at this point last year. Conduit spreads have been largely range-bound, with 10‑year AAA spreads currently at 72 bps over Treasuries, consistent with the trailing 12‑month average of approximately 76 bps.
Over the past several months, borrower spreads remained range‑bound. Ten‑year CMBS loans are generally pricing at 200-225 bps over Treasuries, while 5‑year CMBS loans are pricing in the low‑to‑mid 200 basis point range. For high‑quality, low‑leverage transactions, pricing can be as low as 150 bps over Treasuries.
Multifamily assets continue to attract strong lender demand with CMBS lenders still willing to offer full‑term, interest‑only structures. These loans allow borrowers to maximize proceeds with underwriting typically supporting a 1.25x DSCR on an interest‑only basis. In addition, several CMBS lenders have secured dedicated B‑buyers for multifamily‑only securitizations, enabling the introduction of “stretch senior” executions. These loans are generally priced at 180-225 bps over Treasuries and can be sized down to a 1.20x DSCR on an interest‑only basis.
Other property types including office have benefited from the availability of full‑term, interest‑only financing. However, these transactions are subject to more conservative leverage constraints, higher debt yield requirements, and tighter overall underwriting standards compared to multifamily loans.
| | |
About BWE
Bellwether Enterprise (BWE) is one of the nation's largest privately-owned real estate financing companies. Its trusted advisors combine innovation, extensive experience and strong lender relationships to optimize a loan's capital stack for commercial and multifamily investors, developers and property owners. For more information, visit BWE.com.
| | |
Opinions, estimates, forecasts and all other information contained in this document are those of Bellwether Enterprise Real Estate Capital, LLC (“Bellwether”) and should not be construed as indicating Bellwether’s business prospects or expected results. Although Bellwether attempts to provide reliable, useful information, it does not guarantee that the information or other content in this document is accurate, current, or suitable for any particular purpose. All content is provided on an “as is” basis, with no warranties of any kind whatsoever and is subject to change at any time without notice. Information in this document may not be used without permission from Bellwether. This document is not intended to be an offer to buy or sell or a solicitation of an offer to buy or sell securities, if any, referred to herein.
Bellwether Enterprise Real Estate Capital, LLC (BWE) conducts business through Bellwether Enterprise Mortgage Investments, LLC – Mortgage Banker license #BK-1007784 – the Department of Financial Institutions State of AZ (Fannie Mae transactions), as well as Bellwether Enterprise Real Estate Capital, LLC – Mortgage Banker License #BK-1007825 – the Department of Financial Institutions State of AZ (all other transactions).
| | | | |