|
Weekly Fannie Mae DUS/MBS rate lock volumes jumped to approximately $2 billion amid heightened market volatility, with Agency CMBS borrowers securing financing on their loans before quarter-end. The week marked the highest level of activity for new issue DUS locks this year, with approximately $1.15 billion attributed to four large block transactions. Fannie Mae DUS/MBS investor spreads drifted slightly wider over the week, though held in well relative to other investment-grade assets.
Freddie Mac was active last week as well, with the sale of $750 million of Participation Certificates and a $1.3 billion K-178 10-yr K-loan week that was priced slightly softer than preliminary guidance.
Ginnie Mae's new issue activity continued to be light heading into quarter-end, as its corresponding spreads held steady. In the broader investment-grade (IG) debt market, despite March issuance is on track to be the second busiest on record. Bloomberg reported Thursday that stresses from private credit's concentrated exposure to the software sector, which has been vulnerable to AI disruption, along with renewed inflation pressure from the Iran war, are starting to bleed into IG credit markets.
Some syndicate desks were advising corporate borrowers to wait another week as credit conditions deteriorated further last week. Bloomberg’s Single-A Industrials 10-yr and CDX IG 5-yr Indices were wider by 3-5 basis points by the end of the week. Despite marginal widening these past few weeks, Agency CMBS spreads have held up better than other fixed-income products such as single-family MBS. The outperformance reflects Agency CMBS's prepayment protection, which gives investors more predictable cash flow through yield maintenance provisions that discourage early prepayments, unlike residential mortgages.
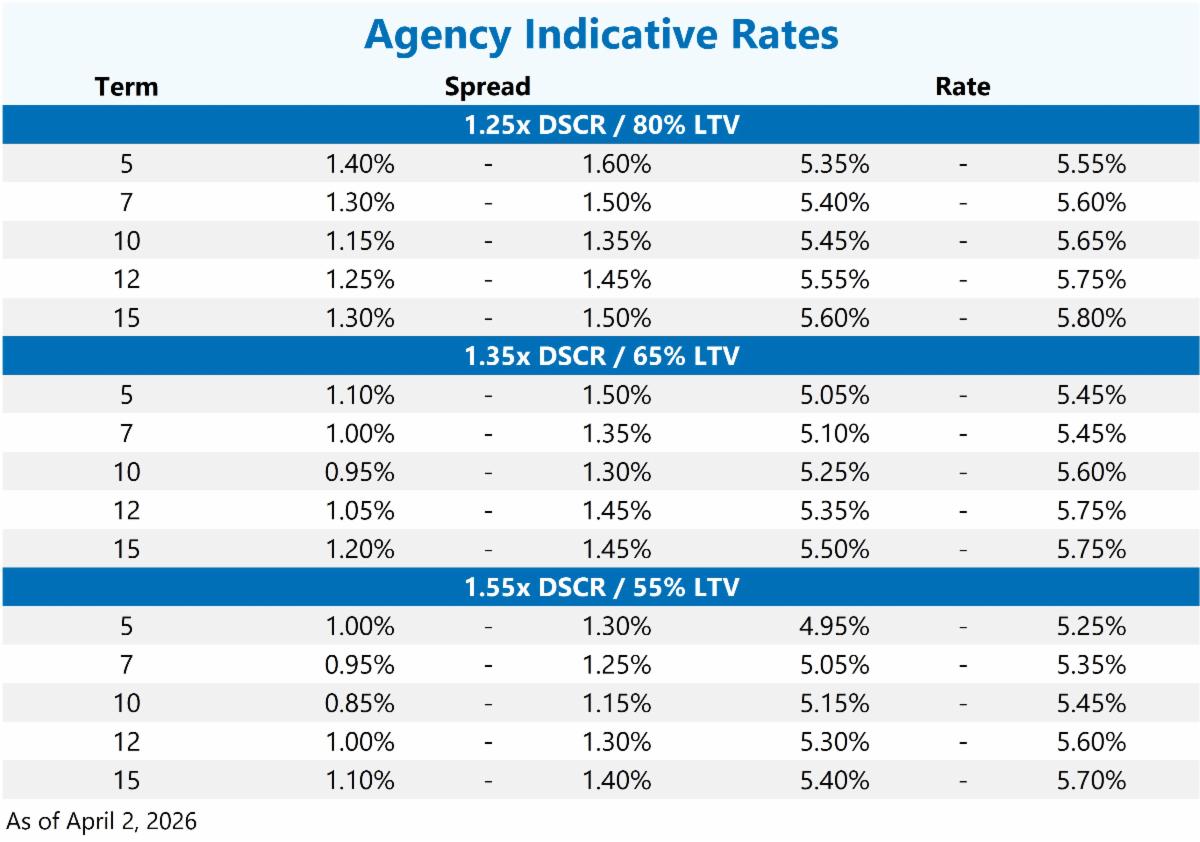
Agency 5-year loans remain in favor
- Over 50% of agency loan volume has originated through 5-year terms. Investors in Agency loans remain most interested in 10-year terms as there has been a flight to safety provided by the Agency secondary investment market during the volatility resulting from the Iran conflict.
Dynamic” nature of Fannie pricing
- Historically, affordability was the primary driver to pricing reductions with Fannie Mae.
- Fannie remains focused on winning business, but less focused on affordability.
- For borrowers, this means…
- Reductions from the top of the pricing grid could change week to week,
- Varying reductions between leverage tiers, and
- Daily communications with Fannie Mae to identify the best quote scenario week to week.
Loan highlights
Fannie Mae Near Stabilization/Construction Take Out – Davenport, FL
- $60.5 million
- 65% LTV
- 135 bps spread with 1% buydown
- 7-yr term / FTIO
Freddie Mac Floating Rate – Boston, MA
- $34.8 million
- 65% LTV
- 129 bps spread
- 5-yr floating / 2 yrs IO
|