September 22, 2025

Last Week's Portfolio Trades


Last Thursday we processed a trade for most of our clients who own IRA accounts. We locked in some very nice gains in our Berkshire Hathaway position and reinvested the proceeds into the Brandes International Equity Fund. We have been adding to our international positions this year as we have seen this asset class strengthening.

The Markets

The bulls were running.


Last week, investors rejoiced after the Federal Reserve Open Market Committee (FOMC) lowered the federal funds rate by a quarter percentage point. Major U.S. stock indexes set new record highs.


FOMC projections for the future suggested more rate cuts could be ahead. “The updated ‘dot plot’ forecasts three cuts in 2025, up from two in June, but the outlook reveals deep uncertainty among policymakers. The median forecast masks a razor-thin 10-9 split among the 19 participants, what economists call a ‘soft median’ that suggests little consensus about the path ahead, reported Nicole Goodkind of Barron’s.


During a press conference, Federal Reserve (Fed) Chair Jerome Powell explained that the rate cut was a response to extraordinary economic circumstances.


“I think you could think of this, in a way, as a risk management cut...it is such an unusual situation. Ordinarily when the labor market is weak, inflation is low; and when the labor market is strong, that’s when you got to be careful about inflation. So, we have a situation where we have two-sided risk, and that means there’s no risk-free path. And so, it’s quite a difficult situation for policymakers.”


U.S. Treasury markets were less confident than stock markets following the Fed rate cut. The yield on the benchmark 10-year Treasury note dipped below 4 percent before moving higher again, reported Martin Baccardax of Barron’s. Rates moved higher because bond investors are concerned that inflation might accelerate. Rising inflation reduces the current value of interest payments, as well as the value of invested principal.


Prospective home buyers won’t be happy about the bond market’s response. The 10-year Treasury is the benchmark for mortgage rates. “Rising 10-year yields are also an issue for the housing market, which remains stuck in low gear amid record-high prices, slow new construction and mortgage rates that keep homeowners reluctant to sell and refinance,” reported Baccardax.


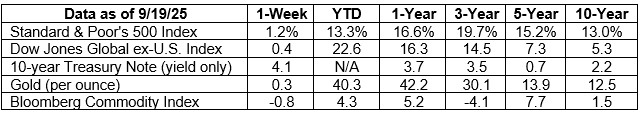
Last week, major U.S. stock indexes finished higher. Treasuries were mixed, with yields on shorter maturities moving lower and yields on longer maturities moving higher.

lunch_suit_soup.jpg

The Alphabet Soup Of Economic Recovery


Economists find the alphabet to be a handy tool for describing economic recoveries. For instance, there are V-shaped recoveries and U-shaped recoveries. The primary difference between the two is the length of the recession. When the economy recovers, enters another recession and recovers again, the recovery is shaped like a W. The dreaded L-shaped recovery occurs when an economy takes years to return to previous levels of growth.


Since the COVID-19 recession ended, the economic recovery in the United States has been K-shaped. One group of Americans has recovered from recession and is doing relatively well. The other has yet to recover fully from the recession. The prongs of the letter “K” represents the split in their economic experiences.


“One way to think about the post-rate-hike economy is as a bifurcation between haves and have-nots as rising underemployment, sticky inflation and higher interest rates hit lower-income households more. Small businesses have also suffered disproportionately from high interest rates and tariffs. High-income households are basically keeping the economy afloat…,” reported Edward Harrison of Bloomberg.


Last week, the FICO Credit Score Report for the second quarter of 2025 reflected the K-shaped economy. The number of people in the highest and lowest credit ranges both increased, and there were 11 percent fewer people in the mid-range. In addition, the report found:


  • U.S. credit scores fell. The average credit score was two points lower than it was in the previous year, largely because of rising credit card use and a surge in missed payments as student loan delinquency reporting resumed.
  • Young people were struggling. The group with the biggest decline in credit scores was 18- to 29-year-olds. This group typically has more student loan debt than older populations.
  • Loan delinquencies were up.
  • Auto loans were paid first. When Americans must decide what to pay first, they typically choose car loans. Next up is the mortgage, followed by credit cards and student loans.


The K-shaped economy reflects uneven economic progress since the pandemic.

big_family_again.jpg

Wise Social Security Planning Seminar


Join us to enhance your understanding of Social Security and build your confidence on potential income strategies.


What you'll learn:

  • Changes happening to SS with the new One Big Beautiful Bill
  • File correctly the first time: "The 12 month window" ruling
  • Navigating strategies to help you capture more income
  • And more!


Dates are Tuesday, October 7th or Wednesday, October 8th at 6:00. We will be meeting in the Eclipse Training Center on the 2nd floor. You can RSVP by clicking on the link below, email pam.huston@avior.com or call (763) 542-8884.


RSVP - Website

thinking_girl_idea.jpg

Weekly Focus - Think About It


“Human greatness does not lie in wealth or power, but in character and goodness. People are just people, and all people have faults and shortcomings, but all of us are born with a basic goodness.”


– Anne Frank, Diarist

Bruce Kuehl | 763.542.8884 | bruce.kuehl@avior.com

Investment management and financial planning services offered through Avior Wealth Management, LLC a registered investment advisor. Investments involve varying degrees of risk and there can be no assurance that the future performance of any investment or investment strategy will be profitable or equal past performance results. All investments subject to loss including the loss of principle. Nothing contained herein should be construed as tax advice. Specific, individual tax questions should be asked of your CPA or accountant.


Please remember to contact Avior, In writing, if there are any changes in your personal/financial situation or investment objectives for the purpose of reviewing/evaluating/revising our previous recommendations and/or services, or if you want to impose, add, or modify any reasonable restrictions to our investment advisory services. Unless, and until, you notify us, in writing, to the contrary, we shall continue to provide services as we do currently. Please advise us if you have not been receiving account statements (at least quarterly) from the account custodian. A copy of our current written disclosure Brochure and Form CRS (Customer Relationship Summary) discussing our advisory services and fees continues to remain available upon request or at www.aviorwealthmn.com.