|
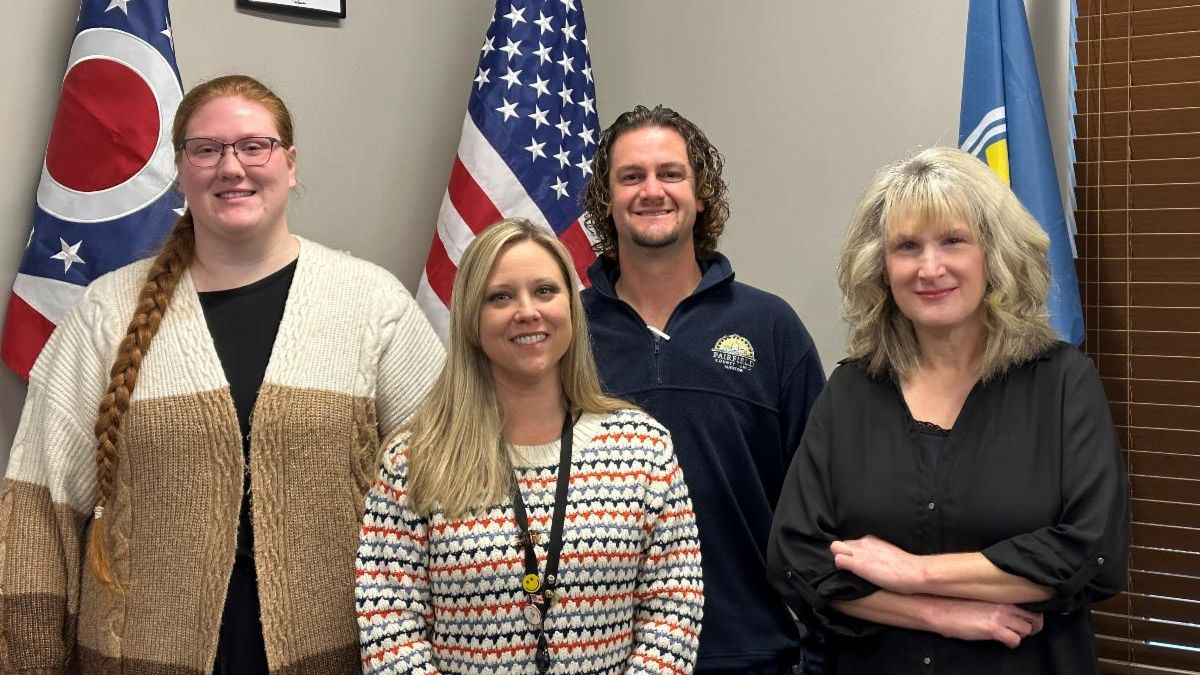
The Board of Revision has completed its hearings for the year. Key members of the Board of Revision Administrative team are pictured to the left. Makala Finley, Crystal Walker, Josh Harper, and Linda O'Toole (author of this article) are the keys to the Board of Revision process running smoothly.
The Fairfield County Board of Revision (BOR) received 45 Complaints Against the Valuation of Real Property for tax year 2023. The BOR began hearing cases on April 10, 2024, and concluded the season on May 29, 2024. The BOR continues to adapt to changes in statutory law which have been implemented as a result of H.B. 126. This year, the board heard several motions filed by the parties due to these statutory changes.
The BOR process begins with the filing of a BOR Complaint. The Ohio Revised Code sets forth those individuals and/or entities that have standing (legal ability) to file a Complaint. Complaint forms can be found on the Auditor’s website. The submission period for filing a Complaint typically begins on January 1 and Complaints must be received by March 31. A United States Mail postmark dated March 31, or earlier, is proof of a timely filing. Complaints filed after this date will be dismissed by the BOR as set forth in the Ohio Revised Code. Complaints are submitted for the prior tax year. For example, a Complaint filed on January 14, 2025, must pertain to the 2024 tax year. A Countercomplaint may be filed within 30 days of the date the Complaint was filed (or post marked by that date) by those persons or entities that are permitted to do so as set forth in the Ohio Revised Code. While some county Boards of Revision may require in-person attendance, the Fairfield County Board of Revision permits participants to attend in-person or virtually so long as advanced notice is provided.
A formal BOR hearing in Fairfield County is recorded and begins with the introduction of the case and exhibits. The parties or their attorneys are asked to introduce themselves and attorneys are asked to formally enter their appearances as a part of the record. The Complainant(s), or Complainant’s counsel, is/are given an opportunity to make a statement or present evidence and/or testimony regarding their opinion of market value of the subject property. The Countercomplainant, or their counsel, if applicable, is/are then provided with the same opportunity to present their statement, evidence and/or testimony. All testimony is made under oath and all witnesses are sworn in by the BOR Administrator prior to their testimony. Parties are given an opportunity to question witnesses for the opposing side. In many instances, the BOR Administrator will also question the witnesses, the parties and/or their respective counsel. Board Members may also pose questions. When the evidence is concluded, the BOR Administrator advises the parties of their appeal rights, if applicable. The BOR issues a decision within 30 days of the date the hearing was held. The decision is emailed or mailed to the parties, or their respective counsel.
In general, examples of sufficient forms of evidence from an owner include documentation of a sale between unrelated parties (sheriffs’ sales generally do not qualify) which occurred within 24 months of the tax lien date (January 1 of the tax year at issue) and/or a formal appraisal prepared by a licensed appraiser who visited and evaluated the property for the specific purpose of determining market value as of the tax lien date. While all evidence accepted into the hearing record is considered by the Board of Revision, including Appraisal Reports, an Appraisal Report without the testimony of the Appraiser who evaluated the property may or may not be deemed sufficient by the Board Members, depending upon the specific circumstances and information provided.
Evidence that is generally insufficient to support an owner’s opinion of value includes: comparable sales data without a formal appraisal; descriptions of poor economic conditions; a listing price of an unsold property; descriptions of negative property characteristics without documentation or a formal appraisal; and a general statement of under or over valuation without an appraisal.
BOR voting members include the County Auditor, the County Treasurer (or his designee), and the President of the Board of County Commissioners (or his designee). The County Auditor, as part of formal responsibilities, has organized a BOR administrative team.
Special thanks to Dr. Carri Brown, the Board of Revision Secretary and County Auditor, for her ongoing leadership and vision, which have contributed to the continued efficiency of the BOR hearing process. Thanks to all BOR Members for their time and input this season as well as the the BOR team members (Dave Burgei, Real Estate Assessment Director; Josh Harper, Real Estate Manager; and Crystal Walker and Makala Finley, Appraisal Assistants) for their hard work, dedication and efficiency. A great deal of organization, preparation and technical expertise is required in order to make each BOR hearing day a successful one.
If you disagree with the Auditor’s market value of your property and have standing to file a Complaint, please remember that the deadline for filing is Monday, March 31, 2025, for the 2024 tax year.
|