|
Taking the Job Market's Pulse
Greetings!
If it seems like there is a new jobs report every few days, you’re not imagining it. Economists use several reports to understand the labor market, and this week brought the Bureau of Labor Statistics’ Job Openings and Labor Turnover Survey (JOLTS) and payroll-processing company Automatic Data Processing (ADP), with the government’s closely watched Employment Situation arriving Friday. Each tells a different part of the story.
JOLTS looks at job openings, hiring, quits and layoffs. July job openings edged up to 7.27 million, while layoffs remained historically low. The bigger concern is hiring. Employers do not appear eager to cut workers, but they are not rushing to add them.
That’s why the labor market is often described as “slow to hire, slow to fire.”
Fed Chair Kevin Warsh offered one explanation recently, saying low turnover partly reflects the “significant rematching between employers and employees” that occurred after the pandemic. In other words, many workers and employers may simply be better matched than they were a few years ago.
Not everyone sees the picture as stable. Andy Challenger, a workplace expert with outplacement firm Challenger, Gray & Christmas, said economists would like to see more hiring alongside low layoffs, adding that companies appear to be having difficulty filling planned positions.
Hiring Remains the Weak Spot
The latest ADP report reinforces that concern. Private employers added just 38,000 jobs in August, the weakest gain since January and below economists’ expectations. ADP is useful as an early look at private-sector hiring, but economists do not treat it as a preview of the government’s payroll number because the two reports can differ substantially from month to month.
That makes Friday’s Employment Situation the big test. It will tell us how many jobs the economy added, where unemployment stands and whether wage growth is accelerating or cooling.
The Fed will be watching closely. A weaker labor market could reduce pressure to keep interest rates high. But with inflation still above the Fed’s 2% target, Warsh has said price stability remains the Fed’s predominant concern. Even softer employment data may not immediately translate into lower borrowing costs.
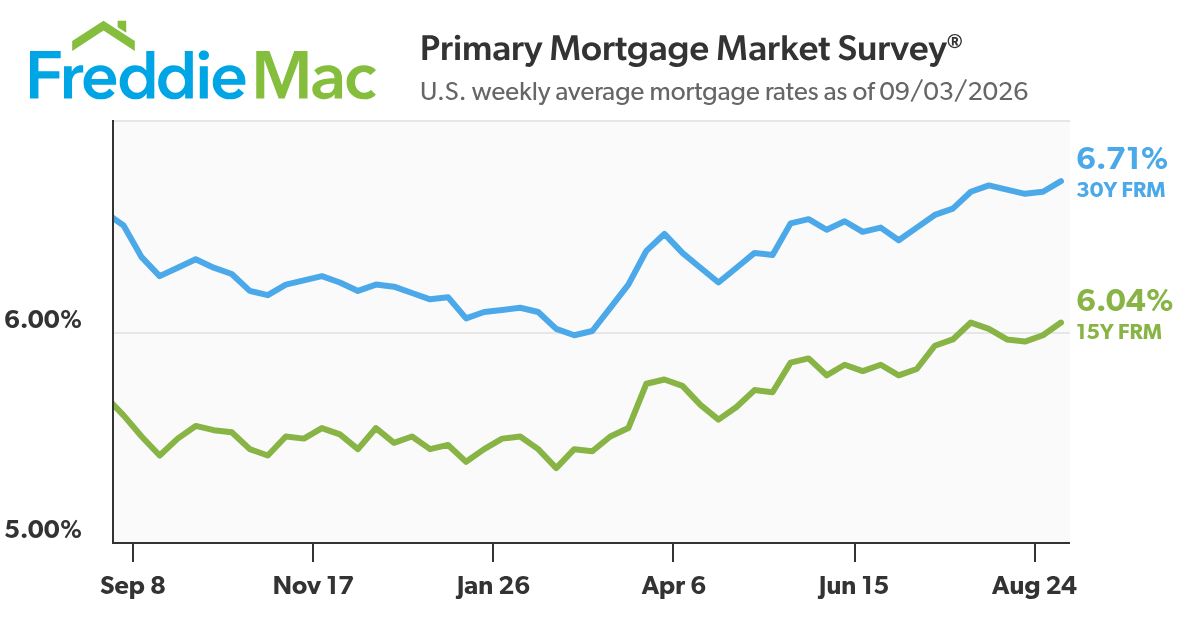
For homebuyers and homeowners, Friday’s report could matter well beyond the job market. A stronger or weaker reading could influence expectations for interest rates and, in turn, mortgage costs in the months ahead.
With the job market sending mixed signals and the Fed watching closely, we’re here to help you make sense of what the latest data could mean for your plans to buy, sell, or refinance. Feel free to reach out anytime—or forward this newsletter to someone who might benefit from the insight.
|