June 8, 2026

The Markets

There was some good news and some bad news last week.


Let’s start with the good news: Employment gains exceeded expectations last month.


Employers in the United States added 172,000 new jobs in May, similar to April’s 179,000 new jobs. The unemployment rate remained steady at 4.3 percent, the average work-week length was about 34 hours, and wages rose.


“The strong payroll growth, steady unemployment rate, and broad-based job gains are unambiguously good news, but Friday's data did show the labor market still has some weak spots…Those who are out of work are also still finding it difficult to get a job. The share of unemployed workers who have been out of work for 27 weeks or more rose to 27.5 [percent] in May, up from 25.3 [percent] in April and 20.4 [percent] a year ago,” reported Megan Leonhardt of Barron’s.


Here’s the bad news: The Federal Reserve probably won’t lower the federal (fed) funds rate this year. It might raise the rate. (The fed funds rate is the interest rate at which banks lend money to each other. Other interest rates often move in the direction the fed funds rate moves, increasing or lowering borrowing costs.)


The Fed’s two main jobs are to keep employment high and inflation low. Employment is healthy. The long-term average unemployment rate in the U.S. is about 5.7 percent, and the current rate is at 4.3 percent. Inflation, on the other hand, is rising faster than the Fed would like and, in recent months, has accelerated. As a result, the Fed is less concerned about supporting employment and more focused on reducing inflation.


One way for the Fed to fight inflation is to raise the federal funds rate. The move typically pushes other interest rates higher, increasing the cost of borrowing. Higher borrowing costs can slow consumer spending. In addition, higher borrowing costs can reduce company profits. When financial analysts anticipate lower corporate profits, they reassess stock valuations, and stock prices sometimes move lower.


While strong employment numbers are good news for people looking for work, they signal to the Fed that the economy doesn't need the support lower rates might provide. Instead, inflation become the Fed’s primary focus. Historically, higher rates are a tool the Fed has used to bring prices down.


The possibility of higher rates hit financial markets hard last week.


“Wall Street’s historic weekly run came to a halt, with stocks hit by a tech selloff and higher bond yields after a solid jobs report added to bets the Federal Reserve’s next interest-rate move will be a hike. That repricing of the Fed outlook coincided with a swoon in the artificial-intelligence shares that had led a surge from this year’s lows,” reported Rita Nazareth of Bloomberg.


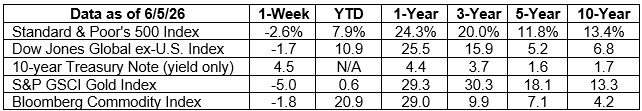
By the end of the day on Friday, major U.S. stock indexes were lower, and yields on all but the shortest maturities of U.S. Treasuries were higher.

Searching For A Social Security Solution


In 2025, the trustees of the Social Security trust fund reported that the fund, “will be able to pay 100 percent of total scheduled benefits until 2033…At that time, the fund’s reserves will become depleted and continuing program income will be sufficient to pay 77 percent of total scheduled benefits.”


As a result, policymakers, researchers, and advocacy groups have been discussing ways to strengthen the program's long-term finances. While there is broad agreement that Social Security's finances should be addressed, there is much less agreement about the best way to address it. As a result, a variety of proposals have emerged, each designed to approach the challenge from a different angle. For example, lawmakers could:


Increase program funding. Increasing the amount of money flowing into the program could help preserve scheduled benefits and improve Social Security's long-term finances. The Peter G. Peterson Foundation highlighted two ways this could be accomplished, including:


  • Increasing the payroll tax rate.
  • Raising or eliminating the cap on earnings subject to Social Security taxes to include income above $176,100.


Slow the growth of program costs. Another approach is to slow the growth of future program costs. Rather than bringing more money into the system, these proposals seek to reduce future obligations. Among the ideas that have been discussed are:


  • Gradually increasing the full retirement age for future retirees.
  • Reducing benefits for higher-income retirees or taxing benefits received by higher-income households.


Consider different investment approaches. A third option is to invest the trust funds differently. One recently discussed proposal would create a fund that invests a portion of Social Security's assets in a diversified portfolio of stocks. The idea is that a diversified investment portfolio could generate higher long-term returns than government bonds alone, potentially strengthening the program's finances over time.


At this point, most experts are not focusing on a single solution. Instead, they are evaluating which combinations of solutions might work because a series of modest changes may be easier to implement than one large change. While there is no consensus yet, a solution that combines various ideas could strengthen Social Security's long-term financial health.

thinking_girl_idea.jpg

Weekly Focus - Think About It


“A nation’s greatness lies in its possibility of achievement in the present, and nothing helps it more than the consciousness of achievement in the past.”  

― Theodore Roosevelt, Former U.S. President

Bruce Kuehl | 763.542.8884 | bruce.kuehl@avior.com

Please feel free to forward this commentary to family, friends or colleagues. If you would like us to add them to the list, please reply to this email with their email address and we will ask for their permission to be added.

Investment management and financial planning services offered through Avior Wealth Management, LLC a registered investment advisor. Investments involve varying degrees of risk and there can be no assurance that the future performance of any investment or investment strategy will be profitable or equal past performance results. All investments subject to loss including the loss of principle. Nothing contained herein should be construed as tax advice. Specific, individual tax questions should be asked of your CPA or accountant.


Please remember to contact Avior, In writing, if there are any changes in your personal/financial situation or investment objectives for the purpose of reviewing/evaluating/revising our previous recommendations and/or services, or if you want to impose, add, or modify any reasonable restrictions to our investment advisory services. Unless, and until, you notify us, in writing, to the contrary, we shall continue to provide services as we do currently. Please advise us if you have not been receiving account statements (at least quarterly) from the account custodian. A copy of our current written disclosure Brochure and Form CRS (Customer Relationship Summary) discussing our advisory services and fees continues to remain available upon request or at www.aviorwealthmn.com.