August 31, 2026

Avior Compliance Letter


In the coming weeks, you will receive a communication from Avior Compliance regarding an amendment to your Investment Management Agreement (IMA).


This update reflects a change in wording only — it does not affect your fee schedule.


As your fiduciary advisor, we believe it's important to keep clients informed whenever changes like this occur. When we joined Avior a few years ago, one of our priorities was ensuring fee schedules remained unchanged while adding access to additional resources for our clients. This update continues that commitment.


No action is needed on your part when you receive this communication.


As always, please reach out with any questions.

happy-couple-sm.jpg

Taxes In Retirement & Medicare Planning Meeting


You should have recently received a mailing with an invite to our planning meeting on Thursday, September 17th at 6:30 pm in our office building. We will have local experts from Avior and from Twin Cities Health Insurance Solutions.


Guests are welcome. Seating is limited, so reserve your spot soon.


RSVP

The Markets

Artificial intelligence (AI) is driving the market and the economy.


Last week, markets experienced a burst of AI enthusiasm after a leading chip manufacturer’s earnings report exceeded expectations. The company anticipates revenue will grow by 70 percent over the coming year. Its shares advanced, as did shares of other AI-related stocks.


“The S&P 500 Index ended the session 0.7 percent higher…Meanwhile, the equal-weight version of the benchmark declined 0.3 percent, a reflection of the number of stocks falling despite tech’s strength,” reported Geoffrey Morgan of Bloomberg.


While investors cheered AI growth expectations, the Federal Reserve (Fed) considered what it means for inflation. Prices continue to increase faster than the Fed’s two percent per year target. Strong economic growth could make it harder to bring prices under control. In a speech last week, Fed Chair Warsh stated,


“Business capital expenditures—the seed corn of future economic growth—are rising rapidly… For firms in the S&P 500, profits have grown by more than 20 percent over the past year…But on the price-stability side of our mandate, the numbers are more concerning. The Fed's preferred measure of inflation, the 12-month change in the PCE price index, stands at 3.7 percent, while the six-month change is 4.1 percent…Inflation is running above our 2 percent target. So the Fed's predominant focus right now should be on prices.”


That commitment complicates the outlook for interest rates. AI is contributing to a surge in business investment, fueling economic growth. Faster growth is good for the economy overall, but it can make the Fed’s job of keeping prices stable more difficult. To bring inflation lower, the Fed may have to raise the federal funds rate. “As a rule of thumb, interest rates often need to be high enough to limit borrowing and spending to cool inflation,” reported Christopher Rugaber of the AP.


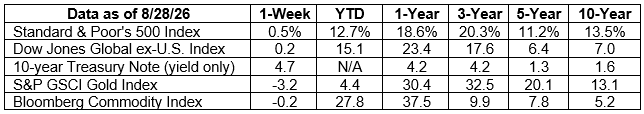
Last week, major U.S. stock indexes finished higher, although they gave back some gains late in the week. Yields on shorter maturities of U.S. Treasuries rose “in anticipation of rate increases as soon as next month,” reported Reuters. In contrast, yields on longer maturities moved lower.

elder-picnic.jpg

How Far Will Your Retirement Savings Take You?


All vehicles are not created equal. A tank of gas will take a fuel-efficient or hybrid vehicle a lot further than it will take a gas guzzler. Retirement savings work in a similar way. Two people can retire with identical amounts of savings, yet the income they generate (and how long that income lasts) may be quite different.


A key issue is taxes.


“Millions of Americans spend decades saving for retirement only to trip over tax bills at the finish line. The shift from earning a paycheck to living off savings creates a new problem: figuring out how to turn assets into income without handing more than necessary to the IRS,” reported Suzanne Woolley of Bloomberg.


Fortunately, there are strategies that can help improve your tax efficiency. (Tax efficiency is making financial decisions that minimize your taxes.) Here are some points to consider:


  • Your retirement income strategy should reflect you. Your strategy should be tailored to you. It will depend on the amount of savings you’ve accumulated, the types of accounts you have (taxable, tax-deferred, and tax-free), and the amount of income you need each year in retirement.


  • Different types of accounts have different tax consequences. Your retirement savings may be in traditional retirement accounts (401ks and IRAs), Roth accounts, and taxable investment accounts. The tax consequences of withdrawals vary by account type, so retirees’ decisions about where to take income directly affect the amount of tax owed. Making thoughtful decisions about withdrawals can help reduce the amount of taxes paid in retirement.


  • Roth accounts deliver tax-free income. Retirees may want to consider converting traditional retirement accounts to Roth IRAs. Income from Roth accounts is typically tax-free, as long as certain conditions are met. In contrast, income from traditional 401(k) and IRA accounts is usually taxable. In addition, when assets are in a Roth IRA, any future growth may be tax-free.


If an account owner moves money from a traditional account to a Roth IRA, the amount converted is generally taxed as ordinary income. Consequently, it’s important to consider whether the amount will push the taxpayer into a higher tax bracket. In general, Roth conversions are most beneficial during years when account owners are in lower tax brackets.


  • Withdrawals from retirement accounts are required in your 70s. At age 73, the IRS requires Americans to begin taking required minimum distributions (RMDs) from traditional retirement accounts. (The age is 75 if you were born in 1960 or later.)


In some cases, RMDs exceed the amount retirees need for income during the year. When that happens, these distributions can be invested or donated to a qualified charity. The amount donated counts toward the RMD, but it isn’t included in taxable income.


The goal of retirement income planning is to have your savings provide income for as long as you may need it. If you have any questions, please get in touch.


This article has been prepared for informational purposes only. It is not intended to provide tax, legal or accounting advice. You should talk with your tax, legal and accounting advisors before engaging in any transaction.

thinking_girl_idea.jpg

Weekly Focus - Think About It


“Old age is like everything else. To make a success of it, you've got to start young.”

― Theodore Roosevelt, 26th President of the United States

Bruce Kuehl | 763.542.8884 | bruce.kuehl@avior.com

Investment management and financial planning services offered through Avior Wealth Management, LLC a registered investment advisor. Investments involve varying degrees of risk and there can be no assurance that the future performance of any investment or investment strategy will be profitable or equal past performance results. All investments subject to loss including the loss of principle. Nothing contained herein should be construed as tax advice. Specific, individual tax questions should be asked of your CPA or accountant.


Please remember to contact Avior, In writing, if there are any changes in your personal/financial situation or investment objectives for the purpose of reviewing/evaluating/revising our previous recommendations and/or services, or if you want to impose, add, or modify any reasonable restrictions to our investment advisory services. Unless, and until, you notify us, in writing, to the contrary, we shall continue to provide services as we do currently. Please advise us if you have not been receiving account statements (at least quarterly) from the account custodian. A copy of our current written disclosure Brochure and Form CRS (Customer Relationship Summary) discussing our advisory services and fees continues to remain available upon request or at www.aviorwealthmn.com.