|
1) What Hit This Morning
-
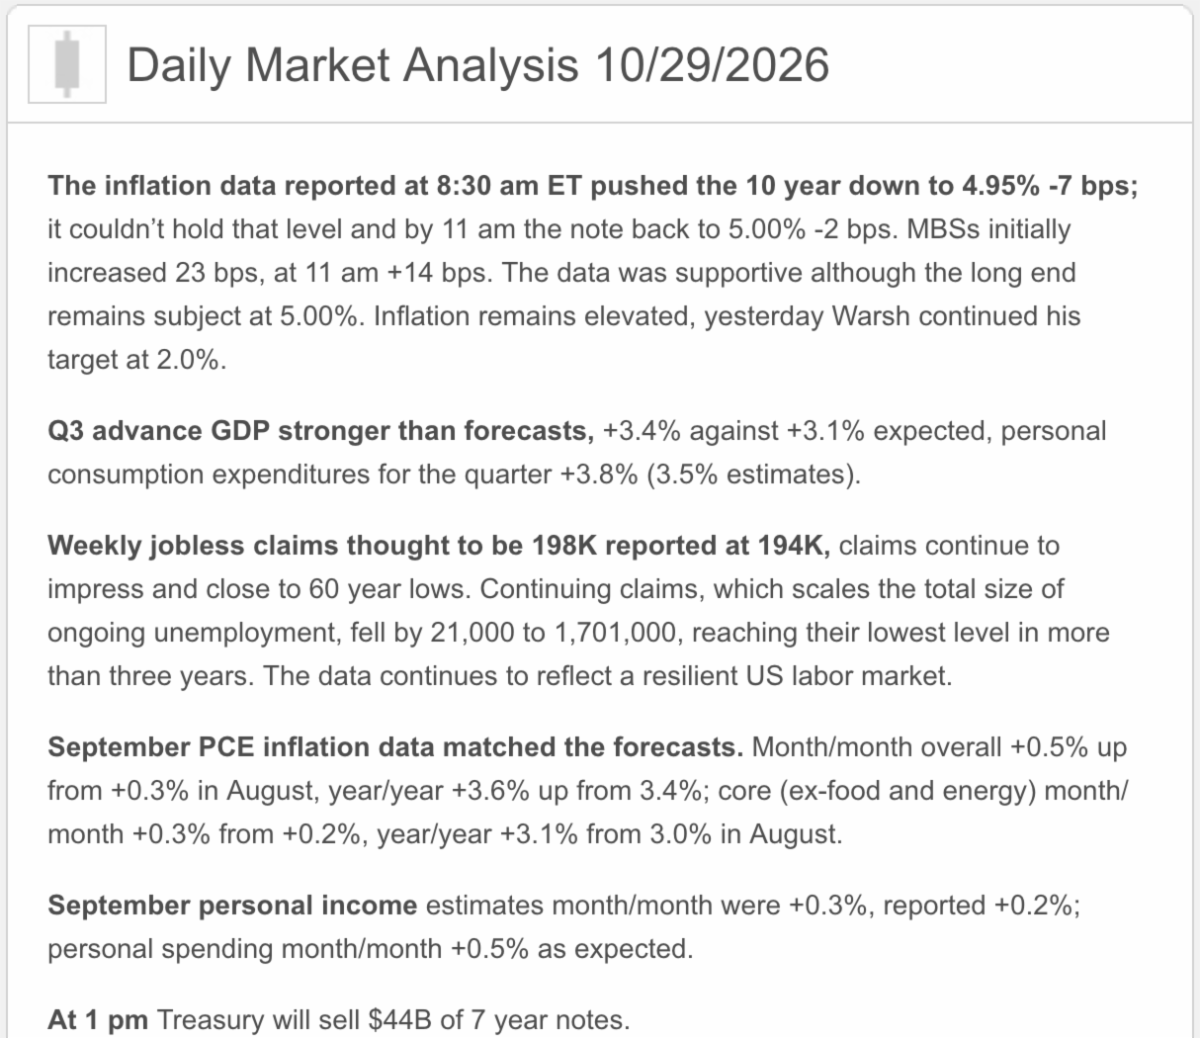
Growth: Third-quarter real GDP rose 3.4% annualized, up from 2.2% in Q2. This is the advance estimate, subject to revision. [2]
-
Inflation: September PCE prices rose 0.5% monthly and 3.6% annually. Core PCE, excluding food and energy, increased 0.3% monthly and 3.1% annually. [3]
-
Jobs: Initial unemployment claims fell to 194,000 for the week ending October 24, down 1,000 from the revised prior week. [4]
Real consumer spending was essentially flat in September despite a 0.5% nominal increase. [3] My read: the economy has momentum, but higher prices are absorbing part of households' spending.
2) Fed Watch
The Fed held its target range at 3.75%–4.00% in a 10–2 vote. Lisa Cook and Beth Hammack preferred a quarter-point increase. Officials described strong economic activity and continued elevated inflation. [5]
This was a pause, not a declaration that inflation is solved. Future decisions remain dependent on incoming evidence.
3) Where Mortgage Rates Actually Are
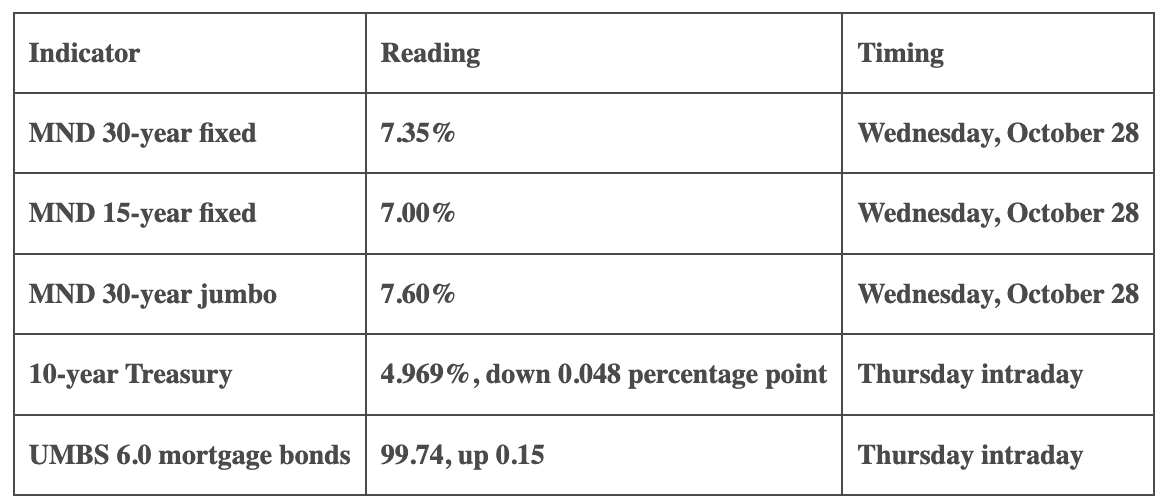
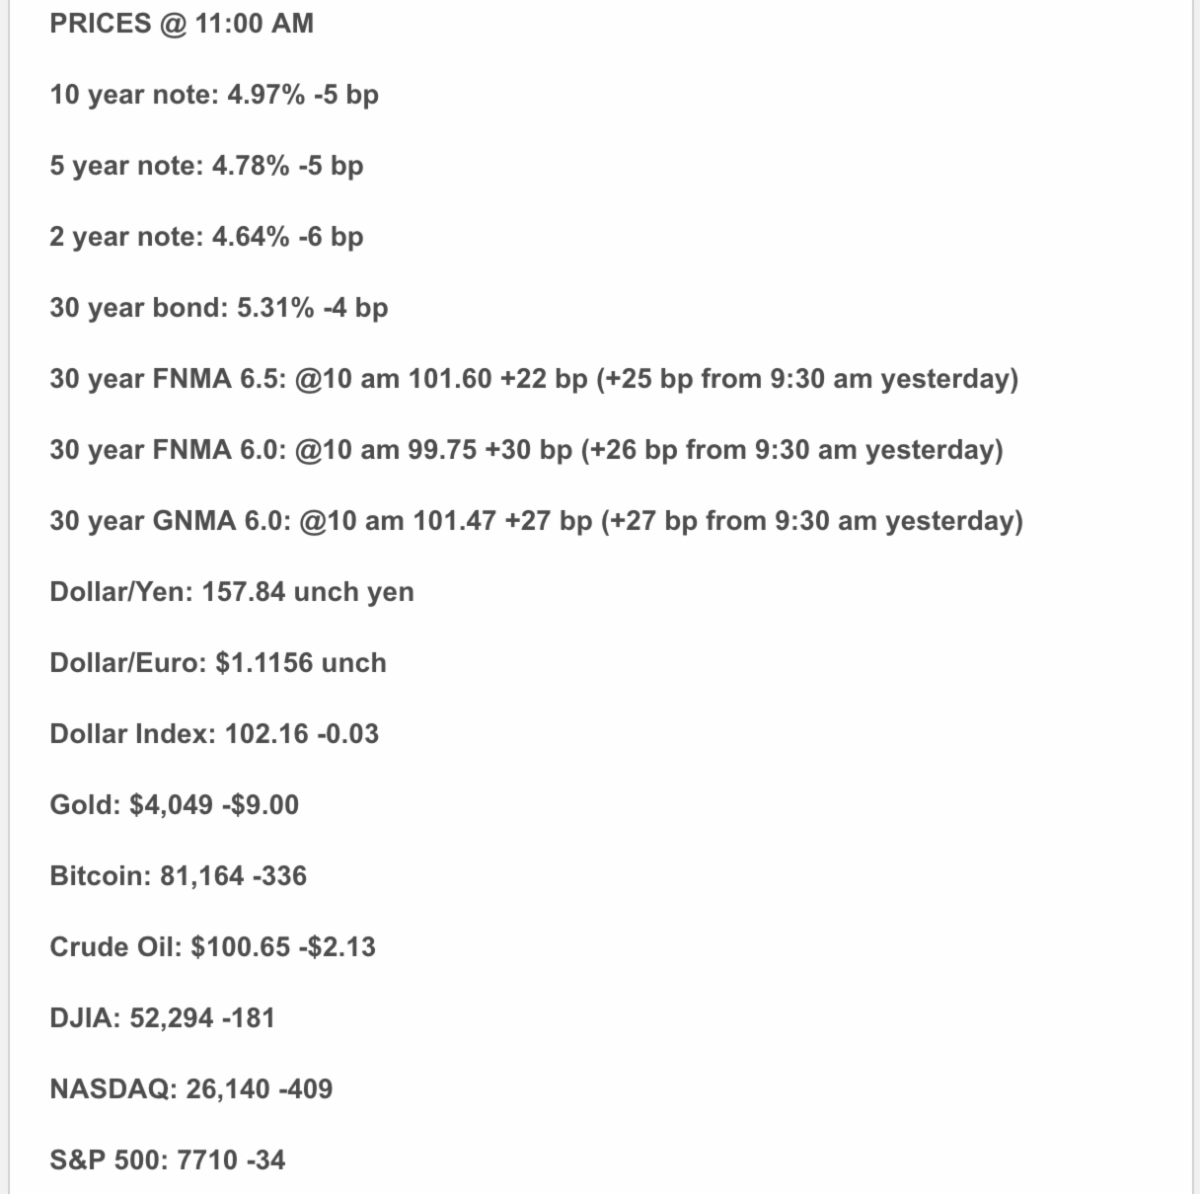
Wednesday's 30-year MND benchmark increased two basis points to 7.35%. Today's stronger mortgage bonds may help pricing, but a lender's actual quote still needs confirmation. [1]
Today's PCE readings matched Reuters' consensus. [7] MND also linked stronger bonds to this morning's technology-stock selloff, led by Alphabet. [9]
A high inflation reading can coexist with bond gains when it does not exceed expectations. The Fed rate and your mortgage rate are related—but they are not twins.
4) Housing Market Check
Tuesday's Census release showed 8.4 months of new-home supply in September, with 476,000 homes for sale across construction stages. [6] That national figure includes unfinished homes; it does not describe every Las Vegas neighborhood.
For buyers and agents, compare a price reduction with eligible seller credits and buydowns. Evaluate cash to close, the full payment and how long the benefit lasts.
5) Political Backdrop & Fed Independence
With the November 3 midterms approaching, inflation and household costs remain central political issues. Treasury Secretary Scott Bessent said Thursday that the administration retains confidence in Warsh's ability to balance inflation control and growth, Reuters reported. [8]
The practical distinction: political commentary can influence sentiment, but it does not set mortgage pricing. Judge policy by the evidence and explanation; election timing alone does not prove motive.
6) Rate Scenarios — Possibilities, Not Predictions
|